




Download the Policybazaar app
to manage all your insurance needs.
Term insurance for housewife can ensure extra family financial security by covering the rising education and marriage costs, as well as healthcare expenses. There are a number of ups and downs in life, which a family should be prepared for. It is not only the absence of a male breadwinner that can affect a family’s finances.


Housewives play an equally important role in running the household and caring for loved ones, and losing them can bring both financial and emotional strain. Their absence in the family can give rise to financial and emotional struggles. Therefore, a term insurance plan is worth considering for every housewife.
Secure Your Family Future Today
₹1 CRORE
Term Plan Starting @
Get an online discount of upto 15%#
Compare 40+ plans from 15 Insurers
Term insurance for a housewife is a type of life insurance plan that pays a death benefit to her family if she passes away during the policy term. It is a pure protection plan that gives the family a financial safety net. In return, the policyholder pays regular premiums for the chosen premium payment term.
This term life insurance plan offers substantial life cover at an affordable premium, helping the family manage essential financial obligations in the absence of the insured housewife.
The following are the best term insurance plans for housewives available in India in {{CURRENTYEAR}}. You can compare the term insurance plan for housewife based on their premiums, sum assured, benefits offered, or the requirement of your husband’s income proof to find the right term insurance plan without income proof for yourself.
˜The insurers/plans mentioned are arranged in order of highest to lowest Sum Assured(SA) offered by Policybazaar’s insurer partners offering term insurance plans on our platform, as per ‘first year premium of life insurers as at 31.03.2025 report’ published by IRDAI.Policybazaar does not endorse, rate or recommend any particular insurer or insurance product offered by any insurer. For complete list of insurers in India refer to the IRDAI website www.irdai.gov.in

Term Plans
A housewife’s work has financial value, even without a direct income. In her absence, the family may need to pay for household support and childcare. Term insurance can provide a lump sum to help cover these expenses.
Health risks also matter when planning financial protection, as breast and cervical cancer are among the most common cancers affecting women in India, according to ICMR’s cancer registry data.
Several insurers offer benefits designed for women, while some insurers also provide health management services such as health checkups that include cancer screenings, diabetes, thyroid, and lipid profile tests; OPD consultations; nutrition, diet, and psychologist consultations; and medicine network discounts.
The best term insurance plan for a housewife gives her nominee a guaranteed lump sum, which the family can use for expenses such as existing loans and children’s education.
According to the Time Use Survey 2024 data released by the National Statistics Office (MoSPI), women who do unpaid domestic work spend 289 minutes a day on it, compared with 88 minutes for men. Over a year, that comes to about 1,750 hours of household work. If a housewife were no longer there, her family would either have to pay for that work or share it among other members.
| Measure (Time Use Survey 2024) | Women | Men |
| Daily time on unpaid domestic services (per participant, aged 6 and above) | 289 min | 88 min |
| Daily time on unpaid caregiving for household members | 137 min | 75 min |
| Share who take part in unpaid domestic services | 81.5% | 27.1% |
| Share who take part in unpaid caregiving | 34% | 17.9% |
According to the same survey, only 25% of women aged 15 to 59 were employed or engaged in related activities on a given day, compared with 75% of men.
As per the National Cancer Registry Programme Report 2020 by ICMR-NCDIR, India had an estimated 2 lakh breast cancer cases in 2020, or 14.8% of all cancer cases, and about 75,000 cervical cancer cases (5.4%). The report also notes that breast cancer incidence is rising. Term insurance cannot replace a housewife’s work, but it can help the family pay for the support they would need without her.
These steps can help you choose the best term insurance for housewife:
Choose the right sum assured: Your life cover is the amount your family receives if you are not around, so it should be enough to meet their needs. Add up your family’s loans, your children’s education costs and monthly household expenses before you decide.
Compare premiums: Different insurers charge different premiums for the same cover. Compare a few plans to find the most cover at a premium your family can comfortably pay.
Look at the policy term: A housewife often looks after children and elderly parents for many years. Choose a policy term that lasts as long as your family depends on you.
Add riders if you need them: Many plans offer riders such as critical illness, accidental death benefit and waiver of premium. Each one adds protection for a specific situation, at a small extra cost.
Decide between a pure term plan and a return-of-premium plan: A pure term plan has the lowest premium and pays out only on the insured's death. A term Insurance with return of premium plan costs more, but refunds the premiums you paid if you survive the policy term.
Check the claim settlement ratio: The Claim Settlement Ratio (CSR) is the number of death claims an insurer settled divided by the total claims it received. A higher CSR generally shows the insurer pays claims reliably.
There is no fixed sum assured for a housewife’s term insurance. The maximum cover depends on her age, lifestyle and the working spouse’s income, and it varies from one insurer to another. Some plans offer a high sum assured or list no upper limit, but the cover approved for a non-earning applicant can be lower than the plan’s maximum.
These factors affect how much cover a housewife can get:
Spouse’s Income: Insurers use the husband’s income and the household’s financial profile to judge how much cover suits a non-earning spouse.
Existing Life Cover: Some insurers also link the cover to the husband's existing life cover, often as a percentage of it. For example, if the husband’s sum assured is ₹1 crore and the limit is 50%, the wife could be covered for up to ₹50 lakh.
Family’s Financial Needs: Think about outstanding loans, children’s education, household expenses, and what it would cost to pay for domestic help or childcare if the housewife were no longer there.
Add up the family’s outstanding loans and the cost of household support, childcare and other needs over the coming years. A common guide for a housewife’s cover is 3 to 5 times the working spouse’s annual income. Use the term insurance calculator to estimate the cover you need, then confirm the sum assured you are eligible for with the insurer.
Below mentioned are some of the benefits of term insurance for housewives:
Fixed Sum Assured: A housewife does a lot of work at home that never shows up as income. If she were no longer there, the family would have to pay for cooking, cleaning and childcare, and those costs add up quickly. A term plan for a housewife pays her family a fixed sum in her absence, which they can use to cover these costs and stay on track with their future goals.
Financial Safety for family: A housewife may not bring in a salary, but the household depends on her in many ways. The death benefit from her term plan gives the family money to fall back on if she passes away. It can pay for daily expenses, and it can be used to clear loans so the family is not left with unpaid debt.
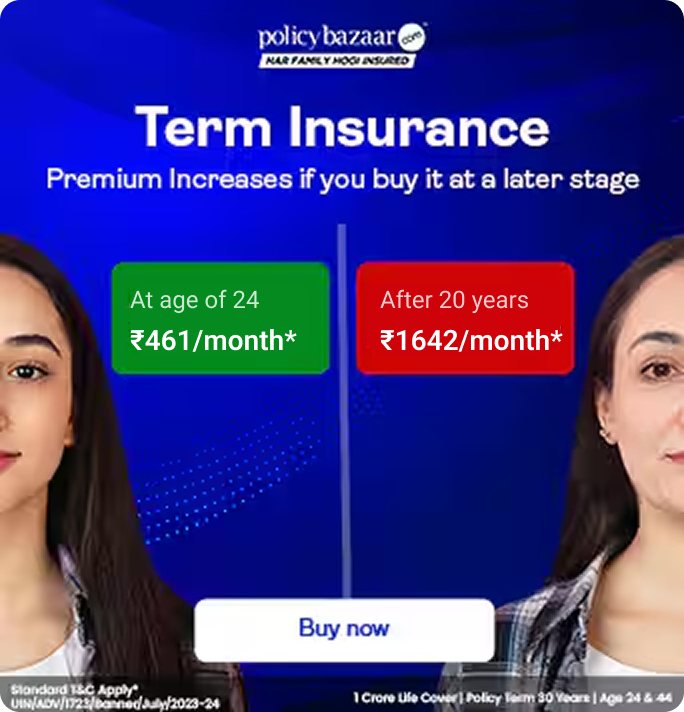
Affordable premiums: Term insurance is one of the lowest-cost ways to buy a large life cover. For example, the indicative premium for a 25-year-old non-smoking woman with ₹50 lakh cover till age 60 is ₹401 per month. Actual premium varies by insurer and underwriting.
Life Stage Cover Enhancements: Some term plans for housewives let you raise the cover as your family grows. A new child or a bigger household brings new costs, such as school fees and, later, marriage. Increasing the sum assured at these points keeps your cover in step with those costs and with inflation.
Critical Illness Coverage: Heart disease, cancer and kidney failure can lead to very high medical bills. With a critical illness rider added to the term plan, you receive a lump sum if you are diagnosed with a covered illness. Some riders also cover illnesses that affect women, such as cervical and breast cancer.
Flexibility: You can shape the plan around your budget. Premiums can be paid as a single payment, for a limited period or for the full term, and on a monthly, quarterly, half-yearly or yearly basis. You can also choose how the payout is received: as a lump sum, as monthly income, as monthly income plus a lump sum, or as a growing monthly income.
Tax Benefits: You can claim tax benefits on term insurance under Section 80C and Section 10(10D) of the Income Tax Act, 1961. From 1 April {{CURRENTYEAR}}, the corresponding provisions are Section 123 and Section 11 (Schedule II) of the Income-tax Act, 2025. The 80C deduction is available only under the old tax regime. Consult a tax advisor to see what applies to you.
Benefits for Children: The financial benefit from the term insurance plan for housewife can be helpful in planning for the future of their child, including their marriage, higher education, and other expenses. This will guarantee a stress free life from financial constraints for her children.
The payout from a housewife’s term plan goes to her nominee, usually the husband or the children. Here is what the family can use it for.
| Family need | How the payout helps |
| Household expenses | Keeps day-to-day costs such as groceries, bills and school transport covered while the family settles into a new routine. |
| Household help and childcare | Pays for a cook, domestic help, tuition or a caregiver for children and elderly parents, work that a housewife often handles herself. |
| Loans and dues | Can be used to repay a home loan or other debts, so the family is not left with the burden. |
| Children’s goals | Keeps plans for school, college and marriage on track. |
| The husband’s long-term plans | Eases the pressure on the earning spouse, so he can keep saving for goals such as retirement. |
Some plans can pay the benefit as a monthly income instead of a lump sum, which suits families that prefer a steady amount each month. To set the sum assured, add up the needs above.
There is no single best term policy for a housewife. The right one depends on how much your family needs, what it spends today, and what it plans for later. Pick a plan whose cover can pay off the home loan, fund your children’s school fees and cover medical bills and other future costs. Then compare premiums, riders and claim settlement ratios across insurers.
No single policy is best for every non-earning housewife. Start with what your family would have to pay for without you: school fees, healthcare and daily living costs. Then choose a term plan whose sum assured covers those costs for the years your family would depend on you.
Look at what she does for the household and what it would cost to replace it. Add any joint debts, such as a home loan, and your family’s future goals. The cover should be large enough to replace her contribution and let the family keep its lifestyle.
Here are some of the features of the term plan for housewife:
High Life Cover
You can purchase a high sum assured amount at very low premium rates. This is mainly because a term plan for housewife is a pure protection policy with no component of investment. The entire premium amount is used to provide the life cover that is paid to the nominee upon demise during the policy tenure.
Option to Increase Cover
Some plans let you raise your sum assured at key life stages, such as marriage or the birth of a child, without a fresh medical check, subject to the insurer’s rules and an age limit. Check whether your chosen plan offers this option, as it is not available with every insurer.
Waiver of Premium
Another benefit that most of the life insurers provide is waiver of premium. This feature waives off the premium payment if the policyholder becomes critically ill, injured, or physically impaired. These are the situations in which the policyholder will not be required to pay the premium amount.
Return of Premium Feature
Some insurers offer a return of premium (ROP) variant. If you survive the policy term, the insurer refunds the premiums paid, subject to the plan’s terms. Because of this refund, ROP plans cost noticeably more than pure term plans, so compare both before choosing
Long Term financial protection
The term plan for housewife can easily be bought for a longer policy term, ensuring family’s financial protection at any time.
Online Accessibility
An individual can now easily access various term plans, assess their features and choose the best term insurance for housewife. In addition to this, buying a term plan, paying a premium amount, submitting a claim, and other processes are quite easy and cost-effective.
Choosing the right life cover (sum assured) in your term plan is important for your family's financial protection. This amount provides important protection in case of unforeseen circumstances, providing you peace of mind. A high amount makes sure your family are supported very well, covering debts/loans, income replacement, and education costs. Choosing the right amount is important to make sure their family’s future is secure. To check the best term life insurance plans, you can find the right sum assured for your financial needs by clicking on the below options.
Terminal Illness: Terminal illness payout, or accelerated death payout, is offered by insurance companies when the life assured is diagnosed with a condition likely to lead to death within 6 months from the date of diagnosis during the policy term. However, if the diagnosis occurs within the last 12-18 months of the policy, early payout may be excluded since death could happen after the policy ends. In such cases, death benefits are still provided to the family, but an early payout isn't an option.
Waiver of Premium: Another benefit offered by numerous life insurance companies in India is the waiver of premium riders. This feature, as the name suggests, waives all the remaining premiums in case of a critical illness or permanent disability. In other words, there are circumstances where the policyholder is not obligated to make premium payments. This becomes relevant when an accident or disability prevents the policyholder from meeting premium obligations.
Critical Illness Rider: If the policyholder is diagnosed with a critical illness, such as a heart attack or cancer, the critical illness rider offers an additional or accelerated payout that helps the policyholder pay for the treatment costs or medical expenses. This is an optional benefit that can be added to the base plan at nominal premiums.
Accidental Death Benefit: A housewife can add extra riders to her term life insurance policy to protect against death caused by accidents. The policyholder can add the accidental death benefit rider to the base term plan to get more coverage. If the policyholder dies in an accident, the term insurance rider will pay out more money.
The term insurance plan for a housewife is necessary to bring financial security to the family in the event of her untimely death. A housewife’s contribution to the family may not be financial, but it is irreplaceable. The term insurance plan also recognizes the contribution made by a housewife. Here are the reasons why term insurance plan for a housewife is important:
Financial Security for the Family
In the absence of a housewife, handling household expenses, children, etc., becomes a challenging task. Term insurance for housewives is very essential in ensuring that the family is in a position to cope with the challenges.
Covers Non Monetary Contributions
Housewives play an important role in managing the home, raising children, and supporting the family. While these contributions cannot be financially measured, term insurance compensates for their value, making sure that the family can afford professional help if needed.
Affordable Premiums for High Cover
Housewives can benefit by obtaining large sum assured at low premium costs, with easier planning of adding term insurance to the budget, ensuring that the women enjoy long-term cover without putting a burden on the budget of the family.
Here is a step-by-step guide on how to buy a term plan for housewife from Policybazaar:
Step 1: Visit Policybazaar and go to their term insurance for housewife page.
Step 2: Fill in all the required details like name, contact number, and date of birth. Then, click on ‘View Plans’.
Step 3: Answer the basic questions about occupation type, annual income, educational qualification, and smoking habits.
Step 4: After submitting all this information, a list of all available term insurance plans for housewife will be displayed
Step 5: Select the term insurance plan for housewife and then proceed to pay.
The proposer (usually the husband) and the life insured (the housewife) provide most of the documents. The exact list varies by insurer, but it usually includes:
Identity Proof: Aadhaar, PAN, passport or voter ID of the housewife.
Address Proof: Aadhaar, a utility bill or a bank statement not older than 3 months.
Age Proof: Birth certificate, passport or school leaving certificate.
Husband’s Income Proof: Salary slips, Form 16 or an income tax return of the earning spouse.
Existing Policy Details: Details of the life cover the husband already holds, which some insurers may ask for.
Photographs: Recent passport-size photographs of the housewife.
Medical Reports: Needed only if the insurer asks for them based on age, sum assured or health.
Here are some of the things you should look into before buying a housewife term insurance:
Make sure the life cover chosen is adequate: Check that the sum assured is enough to support your family if something happens to you. Insurers limit the cover for a housewife based on her husband’s income, so check the maximum before you apply.
Consider your expenses: Add up your children’s education plans, loans and other liabilities, and your family’s regular expenses before you decide the life cover.
A Housewife Can Use Her Husband’s Income Proof: If you do not earn, most insurers accept your husband’s income proof. A working wife can use her own income proof and the other documents the insurer asks for.
Current medical condition: Think about your own health and your family’s medical history to decide whether a health rider is worth adding.
Keep the Type of Term Plan in Mind: Term plans for housewives come in different types, such as pure term, return of premium, and increasing or decreasing cover. Their features differ, so choose the one that fits your needs.
Compare Plans Before You Buy: A term insurance comparison tool lets you compare plans side by side and check the premium, the sum assured limits, the riders, the claim settlement ratio and the policy term. The same cover can cost different amounts from different insurers, and the cover offered to a housewife can also differ from one plan to another.
Yes, in most cases a housewife should have a term plan of her own. Her work keeps the household running, and the family would have to pay for it if she were no longer there. Health is part of the reason too. As per the National Cancer Registry Programme Report 2020 by ICMR-NCDIR, breast and cervical cancer are the most common cancers among women in India. As per the National Family Health Survey (NFHS-5, 2019-21) by the Ministry of Health and Family Welfare, about 21% of women aged 15 and above have hypertension. A family cannot predict these risks, but it can plan for what they would cost.
A term plan gives the family a lump sum if the worst happens, and a critical illness rider adds a payout if she is diagnosed with a covered illness. Before you buy, work out the cover you need, compare a few plans on premium, riders and claim settlement ratio, and answer every health question honestly. Buying early also keeps the premium lower.
˜The insurers/plans mentioned are arranged in order of highest to lowest Sum Assured(SA) offered by Policybazaar’s insurer partners offering term insurance plans on our platform, as per ‘first year premium of life insurers as at 31.03.2025 report’ published by IRDAI.
Policybazaar Insurance Brokers Private Limited does not endorse, rate or recommend any particular insurer or insurance product offered by any insurer. For complete list of insurers in India refer to the IRDAI website www.irdai.gov.in
+On the basis of your profile
+Rs. 410/month is starting price for a 1 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age, rounded off to nearest 10
+Rs. 410/month (Rs.14/day) is starting price for a 1 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age rounded off to nearest 10
+Rs. 245 is starting price for a 50 lakhs term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 8/day is starting price for a 50 lakhs term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age, rounded off to nearest 10
+Rs. 15/day is starting price for a 75 lakhs term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age, rounded off to nearest 10
+Rs. 504/month is starting price for a 1.5 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 494/month is starting price for a 2 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 636/month is starting price for a 3 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 918/month is starting price for a 5 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 1,286/month is starting price for a 7 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 453/month is starting price for a 1 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs.582/month is starting price for a 2 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 786/month is starting price for a 3 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 1,374/month is starting price for a 5 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 1,592/month is starting price for a 7 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 525/month is the starting price for a 1 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 68 years of age.
+Rs. 668/month is starting price for a 2 crore term life insurance for an 25 year-old male, non-smoker, with no pre-existing diseases, cover upto 45 years of age.
+Rs. 1,200/month is starting price for a 2 crore term life insurance for an 35 year-old male, non-smoker, with no pre-existing diseases, cover upto 55 years of age.
+Rs. 410/month is starting price for a 1 crore term life insurance for an 18 year-old Female, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 577/month is starting price for a 1 crore term life insurance for an 18 year-old Male, self employed, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
*The full refund of premium is available on availing the one-time option of refund of premium. Total premium paid for policy (paid for add-ons) will be the special exit value, payable on availing the one-time option of refund of premium if you wish to completely exit the policy.
+Rs. ₹361/month is the starting price for a ₹1 crore loan cover with an 8% interest rate for an 18-year-old male, non-smoker, with no pre-existing diseases, loan tenure up to 20 years, rounded off to the nearest 10
Prices offered by the insurer are as per the approved insurance plans | #All savings and online discounts are provided by insurers as per IRDAI approved insurance plans | Standard Terms and Conditions Apply | **Tax Benefits are subject to changes in tax laws.| Policybazaar Insurance Brokers Private Limited
We will respond in the first instance within 30 minutes of the customers contacting us. 30-minute claim support service is for the purpose of giving reasonable assistance to the policyholder in pursuance of the claim. Settlement of claim (including cashless claim) is the responsibility of the insurer as per policy terms and conditions. The 30-minute claim support is subject to our operations not being impacted by a system failure or force majeure event or for reasons beyond our control. For further details, 24x7 Claims Support Helpline can be reached out at 1800-258-5881
For more details on risk factors, terms and conditions, please read the sales brochure carefully before concluding a sale
Policybazaar Insurance Brokers Private Limited | CIN: U74999HR2014PTC053454 | Registered Office - Plot No.119, Sector - 44, Gurgaon, Haryana – 122001 | Registration No. 742, Valid till 09/06/2027, License category- Composite Broker Visitors are hereby informed that their information submitted on the website may be shared with insurers. Product information is authentic and solely based on the information received from the insurers.
© Copyright 2008-2026 policybazaar.com. All Rights Reserved
˜ Policybazaar Promise reflects the guarantee offered by insurers. Price assurance is based on certifications shared by insurers with us.
ABSLI Life Shield Plan Premium starts
Read more
ABSLI Life Shield Plan Premium starts
Read more
ABSLI Life Shield Plan Premium starts
Read more
ABSLI Life Shield Plan Premium starts
Read more
ABSLI Life Shield Plan Premium starts
Read moreInsurance
Calculators
Payment Methods


Secured With

Follow us on


