₹ 20,000
Download the Policybazaar app
to manage all your insurance needs.
Planning for retirement is a critical step that cannot be deferred, especially for mid-career professionals aged between 45 and 55 years. A 10-year retirement plan offers a strategic, medium-term horizon that balances growth potential with manageable risk, making it an ideal choice for those who want to secure their financial future without relying solely on short-term instruments or excessively long-term commitments.
Peaceful Post-Retirement Life
Tax Free Regular Income
Wealth Generation to beat Inflation

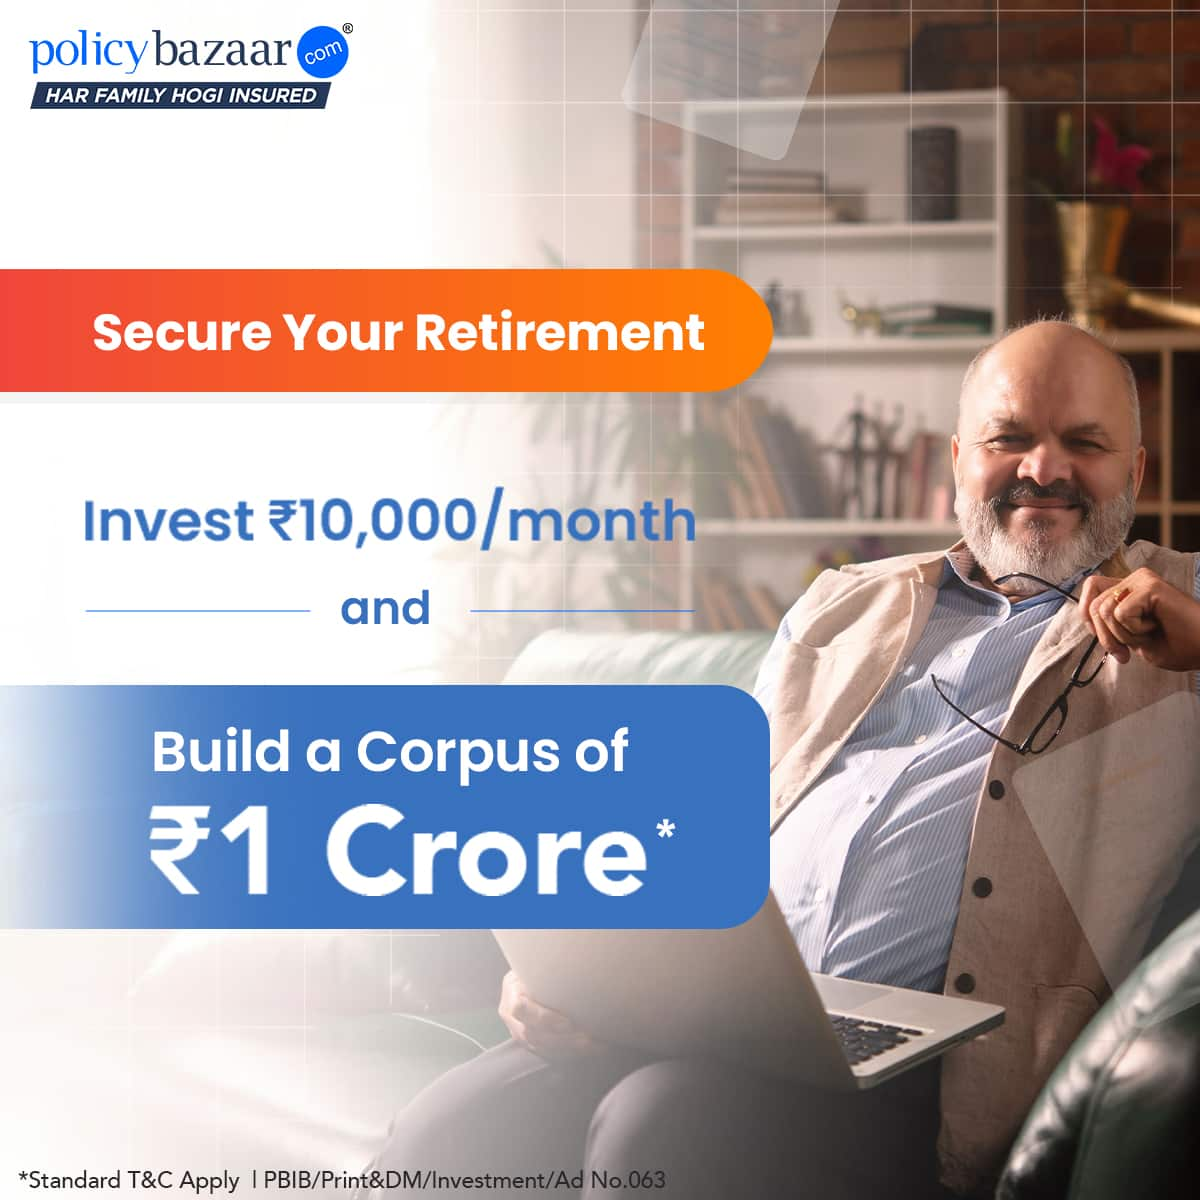
Start Investing ₹10k/Month & Build a corpus of ₹1 Crore# on Retirement

A 10-year retirement plan is designed for individuals looking to accumulate a retirement corpus within a decade. It often involves systematic contributions either through lump-sum or annual/monthly premiums into a professionally managed portfolio that uses compounding returns to grow the corpus. Such investment plans generally provide guaranteed income post-retirement in the form of annuities, ensuring lifelong financial support. Many plans also include life insurance coverage to protect beneficiaries in case of premature demise.
Individuals pay premiums for a fixed term of 10 years. The contributions grow through the power of compounding and sometimes through bonuses or market-linked returns, depending on the plan. Upon maturity, the accumulated corpus can be used to purchase an annuity, which pays regular income for life. The plan can also provide death benefits, paying out the accumulated fund to the nominee in unforeseen circumstances. This approach ensures disciplined investing and wealth accumulation even if retirement is less than a decade away.
Below are the reasons why you should choose a retirement plan for 10 years:
10-year pension plans often qualify for tax deductions under Sections 80C and Section 80CCC, reducing taxable income annually. Equity-oriented retirement plans may offer long-term capital gains (LTCG) tax benefits, making them not only a wealth-building tool but also a tax-efficient instrument. Strategic withdrawal or staggered annuity payouts further optimize tax liabilities post-retirement.
A 10-year retirement plan should complement other instruments like EPF, PPF, NPS, or real estate investments. It acts as a medium-term growth instrument bridging short-term savings and long-term retirement goals with a disciplined, flexible approach. This diversification helps reduce dependency on any single income stream and enhances financial security.
A 10-year retirement plan offers a strategic, achievable pathway to secure one's financial future during the critical mid-career years. By combining disciplined investing, compound growth benefits, balanced risk, and tax efficiency, it empowers individuals to plan smartly, safeguard their retirement corpus, and enjoy a financially independent life post-retirement. Choosing the right pension plan tailored to personal goals and risk tolerance, while regularly tracking progress, will help ensure a comfortable and confident retirement.
18 Aug 2026
A salary of ₹30,000 a month covers essential expenses in most
21 Sep 2023
Planning for retirement requires smart financial choices, and
04 Sep 2023
The Mahila Samman Savings Certificate is a savings scheme
˜The insurers/plans mentioned are arranged in order of highest to lowest first year premium (sum of individual single premium and individual non-single premium) offered by Policybazaar’s insurer partners offering life insurance investment plans on our platform, as per ‘first year premium of life insurers as at 31.03.2025 report’ published by IRDAI. Policybazaar does not endorse, rate or recommend any particular insurer or insurance product offered by any insurer. For complete list of insurers in India refer to the IRDAI website www.irdai.gov.in
*All savings are provided by the insurer as per the IRDAI approved insurance
plan.
^The tax benefits under Section 80C allow a deduction of up to ₹1.5 lakhs from the taxable income per year and 10(10D) tax benefits are for investments made up to ₹2.5 Lakhs/ year for policies bought after 1 Feb 2021. Tax benefits and savings are subject to changes in tax laws.
+Returns Since Inception of LIC Growth Fund
¶Long-term capital gains (LTCG) tax (12.5%) is exempted on annual premiums up to 2.5 lacs.
++Source - Google Review Rating available on:- http://bit.ly/3J20bXZ
^^The information relating to mutual funds presented in this article is for educational purpose only and is not meant for sale. Investment is subject to market risks and the risk is borne by the investor. Please consult your financial advisor before planning your investments.
Insurance
Calculators
Payment Methods


Secured With

Follow us on


