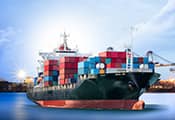
Intermediate storage in marine insurance plays a crucial role in safeguarding your cargo during the transportation process. It refers to the temporary storage of goods at various points along the logistics chain, often between different modes of transport. This temporary pause can be vital for smooth operations, but it also introduces additional risk factors for your cargo. This article delves into the importance of intermediate storage coverage within your marine insurance.
Thank you for showing your interest in marine-insurance. Our relationship manager will call you to discuss the details and share the best quotes from various insurers. In case you have any query or comments, please contact us at corporateinsurance@policybazaar.com
While in transit, cargo is generally well-protected within containers or on ships. However, during intermediate storage, goods are more susceptible to:
Damage: Improper handling during loading/unloading or inadequate storage facilities can lead to physical damage.
Theft: Increased accessibility at storage locations creates opportunities for theft.
Fire and Natural Disasters: Warehouses and storage yards are vulnerable to fire, floods, or other natural disasters.
Role of Intermediate Storage in Facilitating Smooth Transfer between Transportation Modes
Port Congestion: Ports can become congested due to high volumes of incoming and outgoing cargo. Intermediate storage allows for temporary holding of goods until space becomes available on the next vessel or mode of transport. This prevents delays in the overall shipment schedule.
Change in Transportation Mode: Goods might need to switch between different modes of transport during their journey (e.g., ship to train). Intermediate storage facilities at ports, terminals, or rail yards provide a crucial staging ground for such transitions.
Customs Clearance: Customs inspections can sometimes delay the onward movement of goods. Intermediate storage allows for temporary holding while customs formalities are completed, ensuring a smoother flow of cargo through the process.
Role of Intermediate Storage in Enabling Consolidation and Deconsolidation of Goods
Consolidation: Goods from multiple origins might need to be combined into a single shipment for cost-efficiency. Intermediate storage facilities allow for the accumulation of these individual consignments before they are consolidated into containers or larger units for onward transportation.
Deconsolidation: Conversely, large shipments might need to be broken down into smaller units for final delivery to various destinations. Intermediate storage allows for the safekeeping and organisation of cargo before it's deconsolidated for distribution to individual customers.
Inclusions in Intermediate Storage Cover in Marine Insurance
Marine insurance with intermediate storage coverage offers protection against various perils that can occur during this temporary holding period. Here's a breakdown of some key inclusions:
Inland Transit: This covers the movement of goods from the initial warehouse or factory to the port of loading, and vice versa, at the final destination. This ensures seamless coverage throughout the entire journey, even for overland transportation legs.
Warehousing: This covers loss or damage to the cargo while stored at designated facilities like port warehouses, bonded warehouses, freight forwarder's warehouses, or even customer-owned or rented storage spaces. The specific locations covered will depend on the policy wording.
Loading/Unloading: This covers risks associated with the handling of cargo during these critical stages. This includes damage caused by dropping, improper forklift operation, or inadequate securing during transport within the storage facility.
Storage Risks: Depending on the policy, coverage might extend to specific risks associated with storage, such as fire, theft, pilferage, or spoilage due to inadequate temperature control. Some policies might offer optional add-ons for these specific perils.
Customisation Options Based on Specific Needs
The beauty of marine insurance lies in its adaptability. You can tailor your intermediate storage coverage to fit your specific needs. Here are some customization options:
Value of Goods: The declared value of your cargo determines the premium amount. High-value goods might require additional coverage or specific endorsements.
Type of Cargo: Different cargo types have varying susceptibility to damage. Policies can be customised to address specific risks associated with perishables, electronics, fragile items, or hazardous materials.
Duration of Storage: Standard policies might offer a set timeframe for intermediate storage. You can opt for policies with more flexible coverage periods depending on your anticipated storage requirements.
Peril Extensions: While some basic perils are included, you might choose to add riders or endorsements for specific risks depending on the storage location and potential threats.
Exclusions from Intermediate Storage Cover in Marine Insurance
It's crucial to understand the exclusions in your marine insurance policy to avoid coverage gaps during intermediate storage. Here's a breakdown of some common exclusions:
War and Civil Commotion: Damage caused by war, riots, or strikes is typically not covered under standard policies. You might need to purchase additional war risk insurance for such situations.
Inherent Vice: Damage caused by the inherent nature of the cargo itself (e.g., perishable goods spoiling naturally) is not covered by marine insurance. Proper packaging and temperature control remain your responsibility.
Inadequate Packing: If improper packaging contributes to damage during storage, your claim might be denied. It's essential to ensure packaging meets industry standards and is suitable for the cargo and anticipated storage conditions.
Delay: Basic marine insurance typically doesn't cover financial losses due to delays caused by unforeseen circumstances during storage. However, some policies might offer optional coverage for specific delay scenarios.
Duration of Coverage for Intermediate Storage in Marine Insurance
The duration of intermediate storage coverage varies depending on the specific policy terms. Some policies might offer a set timeframe (e.g., 30 days), while others might provide coverage until the cargo reaches its final destination. It's crucial to carefully review your policy and consider extending coverage if your storage needs exceed the standard duration.
Marine Insurance Premium Calculator
New machinery or equipment for industrial use
Iron & steel rods, metal pipes, tubes
Electronic and white goods
All types of FMCG commodities
All kinds of food like oils essence flavours and other various packed items
Automobiles
New machinery machine tools and spares in closed ISO containers
Solar panel
Machinery machine tools spares duly packed/lashed
Stationery items
Timber and wood products
Edible oil in tanker
Aggregators/Transporters
All types of containers
All types of paints duly packed
Auto spare parts
Ceramic products and tiles
Edible vegetables or fruits and nuts or peel of citrus fruits
Granite and marble
Metal hand tools
Metal scrap in ISO container
Metals of all types excluding precious metals
Non hazardous chemicals in bags
Pharmaceuticals and bulk drugs
Rough marble in blocks
Toys, games and sports equipment
Used CPM machines and equipments
Used machinery machine tools and spares in closed ISO container
But, we have offline plans ready.
Connect with our advisor to explore more
Re-calculate
Proactive Risk Assessment and Management for Intermediate Storage
The first step is to identify potential threats specific to your situation. Here are some key factors to consider:
Location: Is the storage facility in a high-crime area? Does it have adequate security measures and is it located in a region prone to natural disasters or political unrest?
Cargo Type: Are your goods fragile, perishable, or high-value, requiring specific handling or storage conditions to prevent damage or theft?
Storage Period: The longer the cargo is stored, the higher the risk. Consider the planned duration and potential for unforeseen delays that could extend the storage timeframe.
Once you've identified potential risks, you can take proactive steps to mitigate them:
Insurance Coverage: A comprehensive marine insurance policy like cargo insurance with intermediate storage coverage is essential. Ensure the policy terms align with your identified risks and storage duration requirements.
Inspections: Schedule regular inspections of the storage facility to ensure proper security measures, adequate environmental controls, and overall cargo integrity.
Security Measures: Work with the storage provider to ensure appropriate security measures are in place. This could involve requesting additional security features like enhanced access control, intruder detection systems, or guard patrols.
Environmental Protections: For temperature-sensitive cargo, verify that the storage facility has the necessary climate control systems to maintain appropriate storage conditions. For certain types of goods, specific packaging materials or moisture control measures might be necessary.
Communication and Documentation: Maintain clear communication with all parties involved in the logistics chain, including the storage provider, your insurer, and any freight forwarders. Ensure proper documentation of the cargo's condition upon entering and exiting storage.
Conclusion
Navigating the complexities of intermediate storage can seem daunting, but with a clear understanding of the risks involved and by implementing effective risk mitigation strategies, you can ensure your cargo reaches its destination safely. Remember, a comprehensive marine insurance policy with intermediate storage coverage acts as a safety net, providing financial protection in case of unforeseen events. To explore marine insurance options tailored to your specific needs, visit Policybazaar.com and talk to an expert.
Marine insurance is essential for protecting goods during...Read more
23 Oct 2024 by Policybazaar4416 Views
Disclaimers+
*Savings of 42% are based on the comparison between the highest and lowest premiums for a Rs 50 lakh sum insured under Inland Transit Clause B or Institute Cargo Clause B for single transit cover of auto spare parts with shipment type of Inland(Domestic) and road as mode of transport. Premium varies on the basis of Occupancy, Business Activity & Coverage Type By clicking on "View Plans" you agree to receive assistance and agree to our Privacy Policy and Terms Of Use and also provide us a formal mandate to represent you to the insurer and communicate to you the grant of a cover. The details of insurance coverage, inclusions and exclusions are subject to change as per solutions offered by insurance providers. The content has been curated based on the general practices in the industry. Policybazaar is not responsible for the factual correctness of these details.
Your call has been scheduled successfully.
Expert advice made easy
Date
Time
When do you want a call back?
Today
Tomorrow
21 Oct
22 Oct
23 Oct
24 Oct
25 Oct
What will be the suitable time?
11:00am - 12:00pm
12:00pm - 01:00pm
01:00pm - 02:00pm
02:00pm - 03:00pm
03:00pm - 04:00pm
04:00pm - 05:00pm
05:00pm - 06:00pm
Tell us the number you want us to call on
Your privacy matters. We wont spam you
Call scheduled successfully!
Our experts will reach out to you on Today between
2:00 PM - 3:00 PM


 We don't spam



 Expert advice made easy