



₹ 20,000
Download the Policybazaar app
to manage all your insurance needs.
While putting together all the personal Financial Planning, one takes a lot of time to think about risks, dream, goals and fear. If we talk about a resilient financial planning for retirement then it is determined by much more than Rupees and Cents. Resilience can be described as the ability tackle life events and other necessities.
Peaceful Post-Retirement Life
Tax Free Regular Income
Wealth Generation to beat Inflation

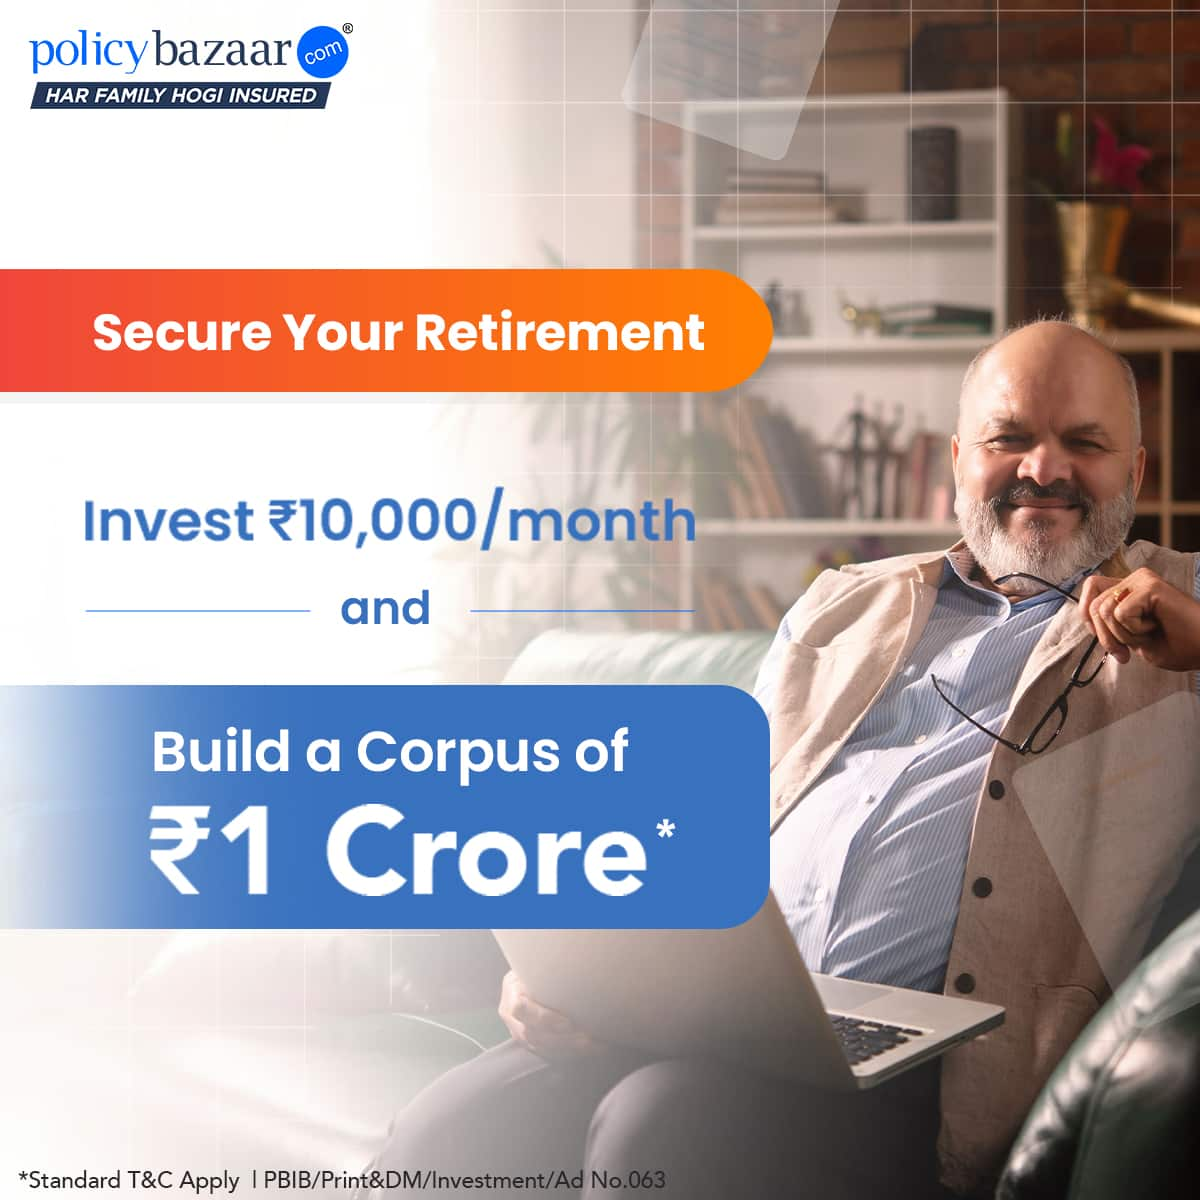
Start Investing ₹10k/Month & Build a corpus of ₹1 Crore# on Retirement

When we think about the events that affect the flexibility of future financial planning then it can end up being positive and negative both like the birth of child, new job or medical problems, etc. The way you choose to react to these potential obstacles while creating a retirement planning highly influence on the overall financial well-being of yours. While doing the financial planning we often overlook the capacity to recover from difficulties.
Keep your goals aside for a second, think what is the worst that can happen? Or how much you can withstand your worst problems?
Well, answering these questions can be difficult but it can be equally eye-opening too. But wait, before we talk about how to do a flexible retirement planning it is important to know what it means to have a resilient retirement plan.
Being resilient represents a dynamic process of learning. Financial resiliency is an ability to endure major setbacks of life that creates an impact on your income and assets. Moreover, the sense of financial planning can be improved by following these simple steps-
Stick to low debt to income ratio
To cover at least 3 months of expenses keep an emergency fund.
Create a healthy lifestyle and pay attention to your physical health and well-being.
Purchase an adequate life insurance and health insurance plan in order to secure the future of your loved ones against any type of emergency situation.
In order to have a successful retirement purchase a proper pension plan so that you can have continues flow of income after retirement.
You have an Ultimate Financial life Goal that Comprises your Long Term Plan for Financial Freedom a.k.a. Retirement
Setting financial planning steadily can positively affect your ability to take a smart economical decision. Financially focused persons use to priorities their goals and stay dedicated to it no matter what. Setting a proper financial planning also helps you to prepare for any emergencies or off the track event.

By listing your short and long-term goals you can create your own retirement egg nest. These are the questions that you should ask yourself while planning for your retirement.
Why having a pension plan is so important?
What should you look forward to do after retirement?
Why is it so important to accomplish all your retirement goals?
How much income will be required to live a good lifestyle after retirement?
Once you get an answer to all these financial planning questions, you can plan your retirement successfully.
So, on the journey to craft a resilient financial planning for retirement, here are 6 important aspects that you can consider.
Take Step to secure your Family and Wealth: To deal with the eventuality in life it is very important to have a financial protection plan by your side. One of the best ways you can start doing that is to create an emergency saving account. Meanwhile, you can protect yourself and your family against catastrophic health-related problems with a proper health insurance plan. If you are in your 60’s or older, then having a life insurance plan or pension plan becomes more important.
The bottom line is to safeguard yourself and your family from any type of financial crunch after retirement.
Evaluate your Health: In today’s life style the health complication starts knocking the door as soon as a person reaches its forties or fifties. In old age the maximum money is spent on medical treatments and hospital bills. With the help of pension plans all the medical expenses can be taken care of once you reach your retirement age. So, as while you are doing financial planning for your retirement, don’t forget to evaluate your health that how much fit or unfit you are.
Know your Asset and how much you need for future: Your expenses can be endless but you can definitely control your asset and savings. You can invest in annuity plans and secure your retirement future. As you reach your retirement age, the returns on your short and long term investment will help you to keep a backup so that in case of any emergency situation you can use these amounts wisely.
Create a Retirement Saving Plan to Meet your Ultimate Income Goals: In order to meet the ultimate financial planning at the later stage in your life, it is important to invest in pension plans and retirement plans at the early stage of your life while being in service. This way you can create an egg nest for your future and deal with the major essentials of life simultaneously. It is often advised that calculating your retirement fund once per year should be part and parcel of your enduring financial plan.
The goal set for retirement can be adjusted according to your retirement lifestyle. Once you have an abundant of retirement saving, you can live the rest of your golden days in a relaxed way.
Form Your Own Retirement Budget-: First and foremost, any salaried individual should create a budget that covers almost all your retirement expenses. An individual can start with major expenses like a mortgage payment or rent, home or renters insurance, monthly property taxes and can also plan the budget based on the utility like water, electric, sewer, phone, grocery etc. Secondly, an individual can create a budget according to their variable expenses like clothing, food, and transportation. As people grow old, naturally the health expenses and other major expenses like the reconstruction of home, etc. increases. So, one should make sure that while planning for the retirement he/she should also include all medical expenses, loans and other things in their budget.
Watch out of Inflation: Keeping in mind the inflation is crucial prior you plan your retirement. It is not necessary that the amount you have saved today will be sufficient to secure your future in 25-30 years later. So, while you are doing a retirement planning make sure that you have ample corpus saved with you so that you can fight the inflation after retirement. Try to make investments through which you can get good returns in near future.
If you are planning for secured retirement then don’t miss to make full use of different pension calculators available online. Hence it can be understood that these pension calculators are very important for retirement planning and should be favorably used to plan a bright and good future ahead. Thus, with the guidance of pension calculator, you can choose the most beneficial pension plan for yourself.
Consider secluding few moments to give a thought on what stands in the mid of you living your current life and the way you want to. Now think forward to your retirement years. Think about what are the obstacles that can come in between of you to reach the most significant life goals for retirement? The more resilient you become towards your difficulties, the less likely these barriers will become a perpetual blockade.
18 Aug 2026
A salary of ₹30,000 a month covers essential expenses in most
21 Sep 2023
Planning for retirement requires smart financial choices, and
04 Sep 2023
The Mahila Samman Savings Certificate is a savings scheme
˜The insurers/plans mentioned are arranged in order of highest to lowest first year premium (sum of individual single premium and individual non-single premium) offered by Policybazaar’s insurer partners offering life insurance investment plans on our platform, as per ‘first year premium of life insurers as at 31.03.2025 report’ published by IRDAI. Policybazaar does not endorse, rate or recommend any particular insurer or insurance product offered by any insurer. For complete list of insurers in India refer to the IRDAI website www.irdai.gov.in
*All savings are provided by the insurer as per the IRDAI approved insurance
plan.
^The tax benefits under Section 80C allow a deduction of up to ₹1.5 lakhs from the taxable income per year and 10(10D) tax benefits are for investments made up to ₹2.5 Lakhs/ year for policies bought after 1 Feb 2021. Tax benefits and savings are subject to changes in tax laws.
+Returns Since Inception of LIC Growth Fund
¶Long-term capital gains (LTCG) tax (12.5%) is exempted on annual premiums up to 2.5 lacs.
++Source - Google Review Rating available on:- http://bit.ly/3J20bXZ
^^The information relating to mutual funds presented in this article is for educational purpose only and is not meant for sale. Investment is subject to market risks and the risk is borne by the investor. Please consult your financial advisor before planning your investments.
Insurance
Calculators
Payment Methods


Secured With

Follow us on


