




Download the Policybazaar app
to manage all your insurance needs.
Pradhan Mantri Awas Yojana-Urban (PMAY-U) is the mission the Ministry of Housing and Urban Affairs (MoHUA) launched on 25 June 2015, setting out to house every eligible urban family by 2022 under the broader banner of Housing for All.Nearly a decade on, it stands as one of the largest urban housing programmes anywhere by beneficiary count, and its core structure now lives on, revised, inside PMAY-Urban 2.0. Approved by the Union Cabinet on 9 August 2024 and effective from 1 September 2024, PMAY-Urban 2.0 is the currently active phase of India's flagship urban housing mission. It targets one crore additional urban families over five years, backed by ₹10 lakh crore in total investment, of which ₹2.30 lakh crore is a direct government subsidy.


The original PM Awas Yojana Urban mission didn't offer a single route to a house. It offered four, built around how a family already lived.
Families in slums got In-situ Slum Redevelopment (ISSR), which used the slum land itself as the resource, redeveloping it with private sector participation so residents could be rehoused on the same site they had always occupied, rather than relocated elsewhere in the city.
Families ready to take a home loan got the Credit Linked Subsidy Scheme (CLSS), an interest subsidy on loans for EWS, LIG and MIG households buying or building a house.
Families without land of their own but wanting to buy in could turn to Affordable Housing in Partnership (AHP), where states, Urban Local Bodies and private developers built projects together with central assistance covering part of the cost.
And families who already owned land simply needed help building on it, which is what Beneficiary-led Individual House Construction and Enhancement (BLC) provided directly.
Every statutory town under Census 2011, along with towns notified since, fell under the mission's coverage. Three of the four components ran as a Centrally Sponsored Scheme; CLSS alone ran separately as a Central Sector Scheme, funded entirely by the Centre.
Central assistance under the mission was never a flat, nationwide number. It moved with the region:
Most states split the cost 60:40, Centre to State
North Eastern Region states, Himachal Pradesh, Uttarakhand and Union Territories with a legislature split 90:10
Union Territories without a legislature had the Centre cover the full cost
This same regional logic, largely unchanged, still governs funding under PMAY-Urban 2.0.
First, the four components hadn't built in a real answer for migrant workers and the urban poor who needed a roof but weren't looking to own one. Second, a fresh cohort of eligible families had emerged beyond what the 2015 estimates had accounted for, and the scheme needed renewed financial firepower to reach them. Both gaps shaped the design of PMAY-U 2.0, cleared by the Cabinet on 9 August 2024.
Nothing built under the original mission was abandoned mid-way. ISSR and CLSS were discontinued as standalone components, but their intent didn't disappear. CLSS's role was absorbed into a redesigned Interest Subsidy Scheme (ISS), and the rental gap ISSR and AHP had never quite closed became its own new vertical, Affordable Rental Housing (ARH).
BLC and AHP continued under their original names, just with updated assistance amounts and eligibility bands. Any house still under construction when the transition happened simply continued to completion, tracked under the new mission's monitoring system rather than restarted from scratch.
PMAY-Urban 2.0 retains the ownership-focused routes of the original mission while adding a dedicated rental housing vertical. The four current verticals are:
| Vertical | Who It's For | Central Assistance |
| Beneficiary Led Construction (BLC) | EWS families building on land they already own | ₹2.50 lakh/unit (most states) |
| Affordable Housing in Partnership (AHP) | EWS families buying into jointly built projects | ₹2.50 lakh/unit (most states) |
| Affordable Rental Housing (ARH) | Migrant workers, students, working women needing rental housing | Technology Innovation Grant, ₹5,000/sq.m combined |
| Interest Subsidy Scheme (ISS) | EWS/LIG/MIG households taking a home loan | 4% subsidy on first ₹8 lakh, capped at ₹1.80 lakh |
A beneficiary can draw benefit from only one vertical at a time. Landless BLC beneficiaries can be granted land rights by their State or UT, and AHP buyers purchasing from private projects receive redeemable housing vouchers.
Under the Interest Subsidy Scheme (ISS), the subsidy applies to loans up to ₹25 lakh for houses valued up to ₹35 lakh, over a tenure of up to 12 years, released in five yearly instalments.
| Feature | PM Awas Yojana Urban (PMAY-U) | PMAY-Urban 2.0 |
| Launch | 25 June 2015 | Approved on 9 August 2024 |
| Main objective | Housing for All in urban areas | Provide affordable housing support to eligible urban families |
| Mission period | 2015 onwards, with the original mission period extended to December 2024 for completion of sanctioned houses | 2024–2029 |
| Original components | ISSR, CLSS, AHP and BLC | BLC, AHP, Affordable Rental Housing (ARH) and Interest Subsidy Scheme (ISS) |
| Rental housing | No dedicated rental housing vertical | ARH introduced as a dedicated vertical |
| Credit-linked support | CLSS | Redesigned as the Interest Subsidy Scheme (ISS) |
| Beneficiary focus | EWS, LIG and MIG households, depending on the component | EWS, LIG and MIG families meeting the revised eligibility conditions |
| Central assistance | Varied by component and region | Revised assistance structure, with support of up to ₹2.50 lakh per unit under BLC/AHP |
| Overall target | Targeted housing for all eligible urban families | 1 crore additional urban families over five years |
| Current status | Fresh applications under the original mission are closed | Current urban housing mission |
The funding structure under PMAY-Urban 2.0 broadly follows the regional pattern of the original mission:
60:40 Centre: State for most states
90:10 for North Eastern states, Himachal Pradesh, Uttarakhand, Delhi, J&K and Puducherry
100:0 for Union Territories without a legislature
ISS lies apart from this entirely, running as a Central Sector Scheme funded fully by the Centre.
There's no fixed target handed down from Delhi. States and UTs assess local demand through their Urban Local Bodies, and proposals move through the State Level Sanctioning and Monitoring Committee, chaired by the Chief Secretary, before the Central Sanctioning and Monitoring Committee (CSMC) releases funds.
The eligibility conditions under PMAY-Urban 2.0 include:
The household, husband, wife and unmarried children must not own a pucca house anywhere in India.
Annual household income must fall within the defined band:
EWS: Up to ₹3 lakh
LIG: ₹3 lakh–₹6 lakh
MIG: ₹6 lakh–₹9 lakh
A beneficiary can avail the benefit of only one vertical.
Coverage spans all statutory towns under Census 2011, towns notified since, and areas under notified planning or development authorities.
Eligible applicants can apply through the PMAY-U 2.0 Unified Web Portal or approach their local Urban Local Body.
The general process is:
Register on the PMAY-U 2.0 Unified Web Portal, or approach the local Urban Local Body.
Submit household, income and property details for the chosen vertical.
Get the details validated by the State, UT or ULB against the eligibility criteria.
BLC/AHP applications move through SLSMC to CSMC; ISS applications go directly to the Primary Lending Institution.
Disbursement follows in instalments tied to construction progress, tracked through geo-tagging on the Ministry's MIS.
By the time the Ministry reported to the Rajya Sabha on 27 July 2026, cumulative sanctions across PMAY-U and its successor had reached 127.68 lakh houses, with 121.03 lakh grounded and 99.07 lakh completed and delivered. Almost all of that scale traces back to the original PMAY-U years; PMAY-U 2.0's own sanctions, 16.20 lakh as of that same reply, only began adding to the total more recently.
PMAY-U has crossed a major milestone, with over 1.25 crore houses sanctioned under PMAY-U and PMAY-U 2.0. More than 1 crore houses have been completed and delivered, while 1 crore houses have been allotted to women, either in the name of the female head of the household or through joint ownership.
The 8th Central Sanctioning and Monitoring Committee (CSMC) meeting, held on 6 August 2026, approved over 2.09 lakh additional houses across 16 States and UTs. Of these, around 1.42 lakh houses were sanctioned under the Beneficiary Led Construction (BLC) vertical and 67,045 under the Affordable Housing in Partnership (AHP) vertical.
| PMAY-U 2.0 Vertical | Houses Sanctioned |
| BLC | 14.40 lakh |
| AHP | 2.48 lakh |
| ISS | 1.36 lakh |
| ARH | 13,046 |
| Total | 18.38 lakh+ |
With the latest approvals, PMAY-U 2.0 has crossed 18.38 lakh sanctioned houses, further expanding the government's ongoing urban housing programme.
PM Awas Yojana Urban established the framework that has shaped Indian urban housing policy for the past decade, with multiple pathways to homeownership, shared funding responsibilities across levels of government, and a demand-driven approach rather than centrally determined targets. PMAY-Urban 2.0 keeps the ownership-focused routes its predecessor offered while adding a dedicated answer for renters, something the original mission never fully solved. The four current verticals, BLC, AHP, Affordable Rental Housing (ARH) and Interest Subsidy Scheme (ISS), are designed to address different housing needs across EWS/LIG/MIG households. As the original PMAY-U is no longer accepting fresh applications, applicants seeking information on current eligibility and application procedures should refer to the dedicated PMAY-U 2.0 portal and verify the latest status before applying, since sanction figures and state-level terms can change.
If yes, Please rate us.

˜The insurers/plans mentioned are arranged in order of highest to lowest Sum Assured(SA) offered by Policybazaar’s insurer partners offering term insurance plans on our platform, as per ‘first year premium of life insurers as at 31.03.2025 report’ published by IRDAI.
Policybazaar does not endorse, rate or recommend any particular insurer or insurance product offered by any insurer. For complete list of insurers in India refer to the IRDAI website www.irdai.gov.in
+On the basis of your profile
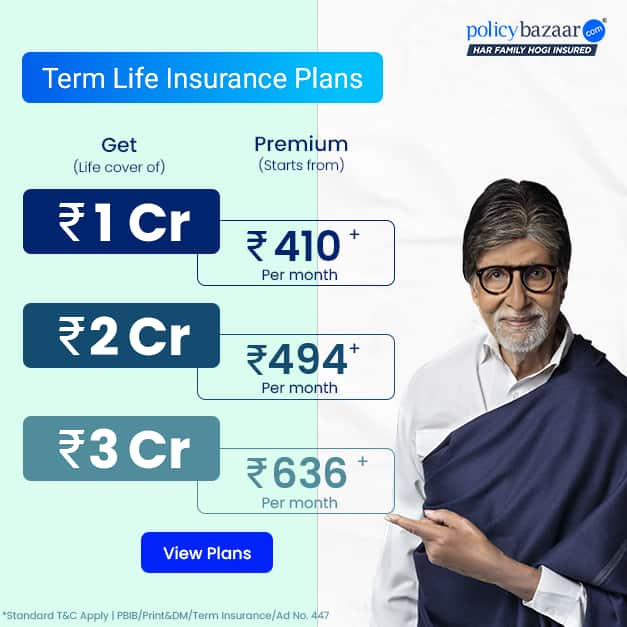
+Rs. 410/month is starting price for a 1 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age, rounded off to nearest 10
+Rs. 410/month (Rs.14/day) is starting price for a 1 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age rounded off to nearest 10
+Rs. 245 is starting price for a 50 lakhs term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 8/day is starting price for a 50 lakhs term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age, rounded off to nearest 10
+Rs. 15/day is starting price for a 75 lakhs term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age, rounded off to nearest 10
+Rs. 504/month is starting price for a 1.5 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 494/month is starting price for a 2 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 636/month is starting price for a 3 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 918/month is starting price for a 5 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 1,286/month is starting price for a 7 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 453/month is starting price for a 1 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs.582/month is starting price for a 2 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 786/month is starting price for a 3 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 1,374/month is starting price for a 5 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 1,592/month is starting price for a 7 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 525/month is the starting price for a 1 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 68 years of age.
+Rs. 668/month is starting price for a 2 crore term life insurance for an 25 year-old male, non-smoker, with no pre-existing diseases, cover upto 45 years of age.
+Rs. 1,200/month is starting price for a 2 crore term life insurance for an 35 year-old male, non-smoker, with no pre-existing diseases, cover upto 55 years of age.
+Rs. 410/month is starting price for a 1 crore term life insurance for an 18 year-old Female, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 577/month is starting price for a 1 crore term life insurance for an 18 year-old Male, self employed, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
*The full refund of premium is available on availing the one-time option of refund of premium. Total premium paid for policy (paid for add-ons) will be the special exit value, payable on availing the one-time option of refund of premium if you wish to completely exit the policy.
+Rs. ₹361/month is the starting price for a ₹1 crore loan cover with an 8% interest rate for an 18-year-old male, non-smoker, with no pre-existing diseases, loan tenure up to 20 years, rounded off to the nearest 10
Prices offered by the insurer are as per the approved insurance plans | #All savings and online discounts are provided by insurers as per IRDAI approved insurance plans | Standard Terms and Conditions Apply | **Tax Benefits are subject to changes in tax laws.| Policybazaar Insurance Brokers Private Limited
We will respond in the first instance within 30 minutes of the customers contacting us. 30-minute claim support service is for the purpose of giving reasonable assistance to the policyholder in pursuance of the claim. Settlement of claim (including cashless claim) is the responsibility of the insurer as per policy terms and conditions. The 30-minute claim support is subject to our operations not being impacted by a system failure or force majeure event or for reasons beyond our control. For further details, 24x7 Claims Support Helpline can be reached out at 1800-258-5881
For more details on risk factors, terms and conditions, please read the sales brochure carefully before concluding a sale
Policybazaar Insurance Brokers Private Limited | CIN: U74999HR2014PTC053454 | Registered Office - Plot No.119, Sector - 44, Gurgaon, Haryana – 122001 | Registration No. 742, Valid till 09/06/2027, License category- Composite Broker Visitors are hereby informed that their information submitted on the website may be shared with insurers. Product information is authentic and solely based on the information received from the insurers.
© Copyright 2008-2026 policybazaar.com. All Rights Reserved
˜ Policybazaar Promise reflects the guarantee offered by insurers. Price assurance is based on certifications shared by insurers with us.
The Namami Gange programme was initiated by the Government of
Read more
The Indian government launched the Atal Bhujal Yojana or Atal
Read more
The Public Health Engineering Department (PHED), Haryana, looks
Read more
One Stop Centre (OSC), popularly known as Sakhi, is a scheme
Read moreInsurance
Calculators
Payment Methods


Secured With

Follow us on


