








Download the Policybazaar app
to manage all your insurance needs.
If you are 30, this is a good year to buy term insurance. You are young enough to get low premiums and healthy enough to clear the medical check without trouble. Most people also have real responsibilities by now: a spouse, a child on the way, parents who depend on them, or a home loan.


A non-smoking 30-year-old male can get ₹1 crore coverage starting at around ₹691 and that premium stays the same for the whole policy term. Wait till 35 or 40 and the same cover costs noticeably more, sometimes with extra medical tests.

Term Plans
| Insurer | Plan | CSR (FY 2025-26) in % | Monthly Premiums for a 30-year-old male | Monthly Premiums for a 30-year-old female |
| Aditya Birla Sun Life | ABSLI Super Term Plan Plus | 98.86 | ₹750 | ₹812 |
| Ageas Federal Life | Super Protect Plus | 99.80 | ₹894 | ₹914 |
| Aviva Life | Signature 3D Term Plan – Platinum | 99.07 | ₹926 | ₹994 |
| Axis Max Life | Smart Term Plan Plus | 99.80 | ₹794 | ₹825 |
| Bajaj Life | eTouch II | 99.33 | ₹764 | ₹791 |
| Bandhan Life | iTerm Elite | 99.73 | ₹824 | ₹899 |
| Canara HSBC Life | Promise2Secure | 99.52 | ₹810 | ₹801 |
| Digit Life | Glow Plus | 99.29 | ₹710 | ₹689 |
| Edelweiss Life | Zindagi Protect Plus | 99.29 | ₹859 | ₹892 |
| HDFC Life | Click 2 Protect Supreme Plus | 99.72 | ₹794 | ₹870 |
| ICICI Life | iProtect Smart Plus | 99.34 | ₹831 | ₹852 |
| IndusInd Nippon Life | Super Suraksha Plus | 98.94 | ₹853 | ₹858 |
| Kotak Life | Protect Advantage | 99.50 | ₹754 | ₹795 |
| PNB MetLife | DigiProtect Term Plan | 99.81 | ₹691 | ₹784 |
| SBI Life | Smart Shield Plus | 98.56 | ₹958 | ₹944 |
| Star Union Dai-ichi Life | SUD Life Assured Term Plan | 99.01 | ₹773 | ₹838 |
| Tata AIA Life | Sampoorna Raksha Promise | 99.45 | ₹773 | ₹831 |
Premiums sourced from the Policybazaar.com quote journey on 30-Sep-2026 for a healthy, non-smoking, salaried individual with ₹1 crore cover till age 60, with no riders. Individual term insurance premiums are exempt from GST. CSR figures are individual death claims by number, FY 2025-26. Insurers are listed alphabetically.
The premiums shown are indicative. Your actual premium may be different depending on your age, gender, location, medical history, existing health conditions, lifestyle habits (such as smoking or alcohol use), income, occupation, cover amount, policy term and the insurer's underwriting decision. Policybazaar does not endorse, rate or recommend any particular insurer.
Secure Your Family Future Today
₹1 CRORE
Term Plan Starting @
Get an online discount of upto 15%#
Compare 40+ plans from 15 Insurers
Your 30s are usually when responsibilities pile up fastest. Term insurance makes sure those responsibilities do not fall on your family if something happens to you.
Your family keeps its lifestyle. The payout can cover rent or EMIs, groceries, school fees and your parents’ medical costs.
Loans do not pass to your family. A home loan, car loan or personal loan can be cleared from the death benefit.
Premiums are low and locked in. The rate you get at 30 stays the same for the full term, even if your health changes later.
Medical checks are easier. Fewer health issues at 30 means faster approval and fewer exclusions.
Nobody plans for an accident or a sudden illness, but a term plan makes sure your family is not left struggling for money if one happens. Here is what a term plan does for you in your 30s.
It Protects Your Family’s Future
By 30, many people are supporting a spouse, young children or ageing parents. If you are not around, a term plan pays your family a lump sum so they can keep running the house, pay school fees and stay in the same home. Term insurance is the simplest form of life insurance, and it gives you a large cover for a small premium.
It Stops Your Loans from Becoming Your Family’s Problem
A home loan or car loan does not disappear when the borrower does. Without cover, your family may have to repay it from their savings or sell assets. The death benefit from a term plan can clear the loan so your family keeps the home and the car.
It Gives High Cover at a Low Cost
A term plan only pays on death, with no savings or investment part mixed in. That is why it costs far less than other life insurance for the same cover. You can name your spouse, child or parent as nominee, and Policybazaar lets you compare plans from 20+ insurers to find the one that fits your budget.
You Can Add Riders for Wider Protection
For a small extra premium, you can add term insurance riders to your base plan. These cover critical illness, accidental total and permanent disability, hospice care, waiver of premium and terminal illness, so you are protected against more than just death.
It Helps You Save Tax
Under the Income Tax Act, 1961, you get term insurance tax benefits in two ways. Premiums you pay can be claimed as a deduction under Section 80C if you file under the old tax regime, and the payout your family receives is tax-free under Section 10(10D).
For a healthy non-smoker male, ₹1 crore of cover for 30 years costs ₹691 a month. Smokers usually pay 30% to 100% more for the same insurance cover.
Example: Mukesh is 30, a salaried non-smoker earning ₹10 lakh a year. He bought a ₹1 crore term plan for 30 years and pays about ₹691 a month. If he dies during the policy term, his nominee gets ₹1 crore.
Each year you wait, the premium for the same cover goes up, and that higher rate stays with you for the rest of the policy. Take a look at the below table to understand:
| Age of the Policyholder | ||||
| 30 years | 35 years | 40 years | 45 years | |
| Monthly Premium for a Male | ₹691 | ₹927 | ₹1,195 | ₹1,698 |
| Monthly Premium for a Female | ₹784 | ₹920 | ₹1,257 | ₹1,297 |
**Monthly premiums for PNB MetLife DigiProtect Term Plan for a male and female of the ages shown, ₹1 crore cover till age 60, non-smoker, as on 30-Sep-2026. Information sourced from Policybazaa
You can use Policybazaar’s term insurance calculator to check the premium for your age, income and habits.
| Type | How it works | Best for |
| Regular term plan | Pays the sum assured if you die during the term. Nothing is paid if you survive. | Maximum cover at the lowest premium |
| Term Return of Premium (TROP) | Term Return of Premium (TROP) pays the death benefit, or returns the base premiums paid if you outlive the term. | People who want money back and can afford a higher premium |
| Zero-cost term plan | Lets you exit the policy at a set age or year and get back the premiums you paid. | People unsure how long they will need cover |
*Note: Most term plans offer optional riders, such as critical illness or accidental death cover, for an extra premium. The benefit you get depends on the rider you choose
There's no one "best" term plan for every 30-year-old. What's right for you depends on how much you earn, who depends on you, any loans you have, and what you can afford each month. If your spouse, kids or parents rely on your income, go for the biggest cover you can comfortably pay for, not the cheapest plan out there. A good rule is cover worth at least 10 to 15 times your yearly income. Some experts even suggest 15 to 20 times, to be safe (Source: Policybazaar's "How India Buys Insurance 2.0" report, 2025).
If you have people depending on you, a pure term plan usually makes the most sense at 30. It only gives you life cover, with no investment mixed in, so you get more cover for your money. Premiums are still low at this age, and once you lock them in, they stay the same for the whole term. Wait until your late 30s or 40s and you'll pay more for the same cover.
Short answer: Buy a plain (regular) term plan online with level cover of 10 to 15 times your yearly income, usually ₹1 crore to ₹1.5 crore, running till age 60 or 65. Add only a critical illness or waiver of premium rider, and pay yearly if you can, since it usually works out slightly cheaper. Skip return of premium plans for now, since they cost far more for the same cover.
When you compare plans, look at these things:
Enough cover, at least 10 to 15 times your yearly income
A good record of paying claims
A premium you can keep paying for years
Cover till at least 60 or 65
Helpful riders like critical illness or waiver of premium, if you need them
How well the insurer treats its customers
Say you earn ₹10 lakh a year and have a wife and a child. A cover of ₹1 crore to ₹2 crore would be a good place to start, depending on your loans and future plans.
To see how this works in real life, meet Rahul. He is 30, earns ₹10 lakh a year, and is the only earner at home. His wife looks after their two-year-old son, and he is paying off a home loan. He wants to protect his family without stretching his monthly budget. Here are the decisions he makes, in order.
When money is tight, every rupee of premium should buy protection. A regular term plan does exactly that and nothing else, which is why it is the cheapest way to get a large cover. Rahul looks at a return of premium plan too, but it costs far more for the same cover, so he sets it aside.
Rahul adds up what his family would need if he were not around, then subtracts what he already has.
| What to count | Amount |
| Income replacement (10 times yearly income) | ₹1 crore |
| Home loan still owed | ₹40 lakh |
| Son's higher education (future cost) | ₹20 lakh |
| Minus: savings and existing life cover | – ₹10 lakh |
| Cover Rahul needs | ₹1.5 crore |
If you have no loans or children yet, 10 times your income is usually enough.
Rahul's home loan ends when he is 50, and his son should be financially independent by the time Rahul is around 55. He picks cover till age 60, which gives him a buffer. For most 30-year-olds, a term of 30 to 35 years, ending at 60 or 65, fits the same way.
Rahul adds a critical illness rider, since a serious illness could stop his income even if he survives it. He skips the others to keep the premium low. A waiver of premium rider is another good pick on a tight budget, because it keeps the policy running if he cannot pay due to illness or disability.
Insurers set a minimum income for high cover amounts, often around ₹3 to 5 lakh a year for ₹1 crore. At ₹10 lakh, Rahul clears this easily, but if your income is lower, check the insurer's limit before you apply.
Because Rahul has a home loan, he buys his policy under the Married Women's Property Act (MWPA). This means the payout goes only to his wife and son, and lenders or relatives cannot claim it.
Paying the premium once a year usually works out slightly cheaper than paying monthly. If a lump sum is hard to manage, monthly payments are fine, as long as they are never missed.
Rahul's final plan: a regular term plan with ₹1.5 crore cover till age 60, a critical illness rider, bought under MWPA and paid yearly. You can check the premium for your own profile using Policybazaar's term insurance calculator.
Buying a term plan takes a few minutes online, but a few checks before you pay can save your family trouble later.
Check the Claim Settlement Ratio
The claim settlement ratio (CSR) shows how many death claims an insurer paid out of all the claims it received. Every insurer in the table above has a CSR above 98%. Even so, look at an insurer's record over the last three years, not just one, to see if it stays steady.
Work Out How Much Cover You Really Need
Start with 10 to 15 times your yearly income. Then add what you still owe on your home loan, car loan or personal loan, and big goals like your child's education. Use an EMI calculator to get the exact loan figures, so your family can clear the debt and still have enough to live on.
Buy While You Are Healthy
Your health decides your premium. At 30, most people have no major illnesses, so you get lower rates and fewer medical tests. If you develop diabetes or high blood pressure later, the same cover can cost more, or the insurer may add exclusions.
Tell the Insurer the Truth
Declare your medical history, smoking, alcohol use and income correctly in the proposal form. Hiding details may lower your premium today, but it is one of the most common reasons claims get rejected.
Choose How Your Family Gets the Money
Most plans let you pick how the death benefit is paid: a lump sum, a monthly income, or part of each. A lump sum helps clear loans at once. A monthly income suits families who would find it hard to manage a large amount.
Read the Exclusions and Waiting Periods
Every plan lists situations it does not cover, such as suicide within the first year. Riders like critical illness cover also have waiting periods and a fixed list of illnesses. Read these before you buy, not when you claim.
Compare Premiums for Your Profile
Use a term insurance premium calculator with your age, gender, income, cover amount, policy term and tobacco habits. It shows quotes from several insurers side by side, so you can compare price along with CSR and features.
At 30, term insurance costs less than it will at any later age, and your family is likely to need it more than ever. As the age-wise table shows, the same ₹1 crore cover that starts at about ₹691 per month for a 30-year-old male costs ₹1,195 per month at 40. Work out how much cover you need, choose a term that lasts till your responsibilities end, and lock in the premium while it is low. You can compare term plans from 20+ insurers on Policybazaar in a few minutes and pick the one that suits your family and your budget.
If yes, Please rate us.

˜The insurers/plans mentioned are arranged in order of highest to lowest Sum Assured(SA) offered by Policybazaar’s insurer partners offering term insurance plans on our platform, as per ‘first year premium of life insurers as at 31.03.2025 report’ published by IRDAI.
Policybazaar Insurance Brokers Private Limited does not endorse, rate or recommend any particular insurer or insurance product offered by any insurer. For complete list of insurers in India refer to the IRDAI website www.irdai.gov.in
+On the basis of your profile
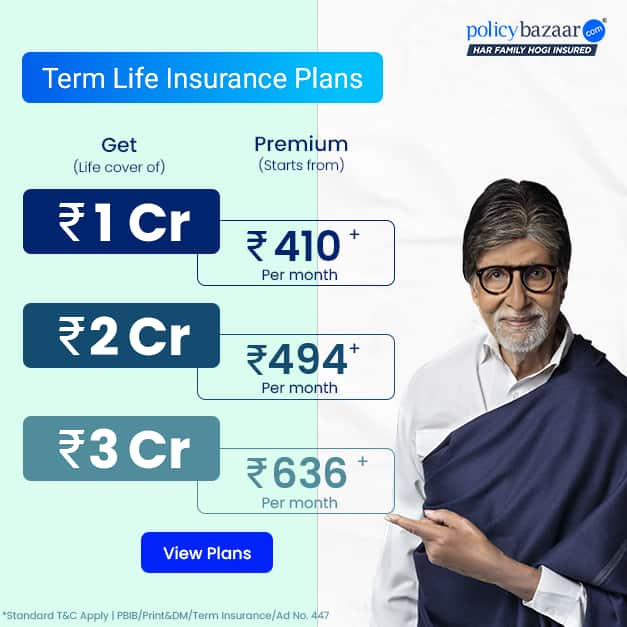
+Rs. 410/month is starting price for a 1 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age, rounded off to nearest 10
+Rs. 410/month (Rs.14/day) is starting price for a 1 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age rounded off to nearest 10
+Rs. 245 is starting price for a 50 lakhs term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 8/day is starting price for a 50 lakhs term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age, rounded off to nearest 10
+Rs. 15/day is starting price for a 75 lakhs term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age, rounded off to nearest 10
+Rs. 504/month is starting price for a 1.5 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 494/month is starting price for a 2 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 636/month is starting price for a 3 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 918/month is starting price for a 5 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 1,286/month is starting price for a 7 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 453/month is starting price for a 1 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs.582/month is starting price for a 2 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 786/month is starting price for a 3 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 1,374/month is starting price for a 5 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 1,592/month is starting price for a 7 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 525/month is the starting price for a 1 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 68 years of age.
+Rs. 668/month is starting price for a 2 crore term life insurance for an 25 year-old male, non-smoker, with no pre-existing diseases, cover upto 45 years of age.
+Rs. 1,200/month is starting price for a 2 crore term life insurance for an 35 year-old male, non-smoker, with no pre-existing diseases, cover upto 55 years of age.
+Rs. 410/month is starting price for a 1 crore term life insurance for an 18 year-old Female, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 577/month is starting price for a 1 crore term life insurance for an 18 year-old Male, self employed, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
*The full refund of premium is available on availing the one-time option of refund of premium. Total premium paid for policy (paid for add-ons) will be the special exit value, payable on availing the one-time option of refund of premium if you wish to completely exit the policy.
+Rs. ₹361/month is the starting price for a ₹1 crore loan cover with an 8% interest rate for an 18-year-old male, non-smoker, with no pre-existing diseases, loan tenure up to 20 years, rounded off to the nearest 10
Prices offered by the insurer are as per the approved insurance plans | #All savings and online discounts are provided by insurers as per IRDAI approved insurance plans | Standard Terms and Conditions Apply | **Tax Benefits are subject to changes in tax laws.| Policybazaar Insurance Brokers Private Limited
We will respond in the first instance within 30 minutes of the customers contacting us. 30-minute claim support service is for the purpose of giving reasonable assistance to the policyholder in pursuance of the claim. Settlement of claim (including cashless claim) is the responsibility of the insurer as per policy terms and conditions. The 30-minute claim support is subject to our operations not being impacted by a system failure or force majeure event or for reasons beyond our control. For further details, 24x7 Claims Support Helpline can be reached out at 1800-258-5881
For more details on risk factors, terms and conditions, please read the sales brochure carefully before concluding a sale
Policybazaar Insurance Brokers Private Limited | CIN: U74999HR2014PTC053454 | Registered Office - Plot No.119, Sector - 44, Gurgaon, Haryana – 122001 | Registration No. 742, Valid till 09/06/2027, License category- Composite Broker Visitors are hereby informed that their information submitted on the website may be shared with insurers. Product information is authentic and solely based on the information received from the insurers.
© Copyright 2008-2026 policybazaar.com. All Rights Reserved
˜ Policybazaar Promise reflects the guarantee offered by insurers. Price assurance is based on certifications shared by insurers with us.
ABSLI Life Shield Plan Premium starts
Read more
ABSLI Life Shield Plan Premium starts
Read more
ABSLI Life Shield Plan Premium starts
Read more
ABSLI Life Shield Plan Premium starts
Read more
ABSLI Life Shield Plan Premium starts
Read moreInsurance
Calculators
Payment Methods


Secured With

Follow us on


