






Download the Policybazaar app
to manage all your insurance needs.
Term insurance is a pure protection type of life insurance that provides a death benefit for a fixed period, whereas life insurance is a broader category that includes savings, investment, or whole-life plans with maturity benefits. In this term insurance vs life insurance article, we compare the two on cover, premium returns and tax so you can choose the one that fits your needs.


In this article, let us understand term insurance vs life insurance in detail so you can decide which one fits your needs.

Term Plans
The table below shows the term insurance and life insurance difference by comparing a regular term plan with savings-linked life insurance plans such as endowment, money-back, ULIP and whole life policies.
| Basis | Term Insurance | Life Insurance (Savings-Linked Plans) |
| Purpose | Financial protection for your family | Protection plus savings or investment |
| What it pays | Death benefit only, if death occurs within the policy term | Death benefit, plus maturity or survival benefit |
| Maturity benefit | Not payable in regular plans; available in return of premium (TROP) variants | Payable in most plans |
| Premium | Affordable premiums | Much higher for the same sum assured |
| Policy tenure |
|
|
| Flexibility | Inflexible | Flexible |
| Surrender and paid-up value | None in regular-pay plans; the policy lapses if premiums stop | Plan becomes paid-up after a minimum number of premiums; surrender value is payable |
| Loan against policy | Not available | Available on most traditional plans once they acquire a surrender value |
| Tax benefits | Deduction on premium; tax-free death benefit | Deduction on premium; tax-free death and maturity benefit, subject to conditions |
| Best suited for | Earning members with dependents or loans who need high cover | People who want guaranteed savings or a long-term corpus along with some cover |
The above representation of the difference between term insurance and life insurance will help you understand how both these policies work and if they suit your needs or not.
Term insurance is the simplest form of life insurance. In simple terms, the term insurance definition is a pure protection policy that pays only if the insured person dies during a fixed period. You pick a cover amount and a policy term, and pay a premium for it. If you die during the term, your nominee receives the sum assured as a lump sum, a monthly income, or a mix of both. If you survive the term, the cover ends. That is the basic term insurance policy meaning. Any term life insurance policy, whatever the insurer calls it, works on this principle.
Moreover, Policybazaar’s How India Buys Insurance 2.0 report highlights a 58% surge in term insurance purchases among self-employed individuals in India, significantly outpacing purchases by salaried individuals. This growth is largely driven by Millennials and Gen Z, who increasingly view term insurance as a crucial financial protection tool.
High cover at low cost: A cover of ₹1 crore or more is affordable, especially if you buy young.
Flexible payout: Your nominee can receive the money as a lump sum, a monthly income, or both.
Riders: You can add critical illness, accidental death, disability or waiver of premium riders for wider protection.
Premium payment options: Pay regularly, for a limited number of years, or as a single premium.
Return of premium option: A TROP plan refunds the premiums you paid if you survive the term, but costs more than a regular term plan.
Below mentioned are the types of term insurance plans. Take a look:
Level term plan: The sum assured stays the same throughout the policy term.
Increasing term plan: The cover rises every year at a fixed rate to keep pace with inflation.
Decreasing term plan: The cover reduces over time, often in line with an outstanding loan.
Convertible term plan: You can convert the policy into an endowment or whole life plan later, as per the policy terms.
Term plan with return of premium: You get your premiums back if you outlive the policy.
Secure Your Family Future Today
₹1 CRORE
Term Plan Starting @
Get an online discount of upto 15%#
Compare 40+ plans from 15 Insurers
Life insurance is a contract in which the insurer pays a sum to your nominee if you die during the policy period. It is a broad category, and term insurance is one type within it. When people compare term insurance with life insurance, they usually compare savings-linked plans that pay you if you survive the term.
In these plans, a part of your premium pays for life cover and the rest goes into savings or investments. That is why premiums are higher and the sum assured is lower than in a term plan with the same premium.
Endowment plan: Pays the sum assured plus bonuses on maturity, or to your nominee on death. Suits people who want low-risk, disciplined savings.
Money-back plan: A type of life insurance plan that provides both life insurance coverage and guaranteed periodic cash payouts (called survival benefits) at regular intervals during the policy term.
Whole life plan: Covers you up to age 99 or 100 and is often used for legacy planning.
ULIP: Invests part of the premium in equity, debt or balanced funds of your choice. Returns depend on market performance, and there is a five-year lock-in.
Child plan: Builds a fund for milestones such as higher education. If the parent dies, future premiums are usually waived and the plan continues.
Pension plan: Builds a retirement corpus that later pays you a regular income.
Now that you know Term Insurance vs Life Insurance, it is essential to look at their examples for better understanding. These two examples show how each plan works for two 30-year-olds.
Term insurance example
Amit, 30, buys a term insurance plan with a cover of ₹1 crore for 30 years and pays about ₹600 a month.
If Amit dies in the 15th year of the policy, his family receives the full ₹1 crore.
If Amit survives till 60, when the policy term ends, the cover stops and no money is paid back.
Life insurance example
Priya, 30, buys a traditional endowment plan and pays ₹5,000 a month.
If Priya dies during the policy term, her nominee receives the death benefit.
If she survives the full term, she receives a lump-sum maturity benefit, including any bonuses earned.
What these examples show:
Amit pays far less and gets a much larger cover, but receives nothing if he outlives the policy. Priya pays more and gets her money back at maturity, but her family receives a much smaller amount if she dies early. In short, term insurance gives maximum protection at a low cost, while life insurance trades a part of that protection for savings. This example helps you analyze the policies through a clear difference between life insurance and term insurance in terms of returns and investments.
Premiums are for illustration only and depend on age, health, lifestyle, cover amount and policy term.
The right choice depends on what you want the policy to do. Start with these questions.
People depend on your income, such as a spouse, children or parents.
You have a home loan, car loan or other liabilities your family would have to repay.
You want the highest cover your budget allows.
You already invest through mutual funds, PPF, NPS or other options.
You want guaranteed returns and are comfortable with lower cover.
You find it hard to save regularly and want the discipline of a fixed premium.
You are planning for a specific goal, such as a child's education or leaving money for the next generation.
Yes, and many families do. A common approach is to get adequate cover through a term plan first, usually 10 to 15 times your annual income. If you still have money to set aside, you can add a savings or investment plan for your goals. Some people prefer to buy term and invest the rest in other instruments, which separates protection from wealth creation and keeps costs clear.
What are the different types of insurance companies in India?
Insurance companies in India fall into a few groups, all regulated by IRDAI.
Life insurers: Sell term plans, endowment and money-back plans, ULIPs, pension plans and whole life policies.
General insurers: Cover health, motor, travel, home, fire and other risks to property and liabilities.
Standalone health insurers: General insurers that sell only health insurance.
Reinsurers: Insure the insurance companies themselves, such as GIC Re.
Both public and private companies operate in the life and general insurance segments.
What is the difference between term insurance and health insurance?
Term insurance protects your family after your death, while health insurance pays your medical bills while you are alive.
Term insurance: Pays a lump sum or a monthly income to your nominee if you die during the policy term.
Health insurance: Covers hospitalisation, surgery, day-care procedures and related costs, often cashless at network hospitals.
Premium: Term premiums usually stay fixed for the whole policy term. Health premiums are paid at each renewal and rise with age.
What are the differences between life insurance and non-life insurance?
Life insurance offers financial protection linked to the policyholder’s life and may also provide savings or investment benefits. Non-life insurance, on the other hand, covers risks related to health, vehicles, travel, home, and other assets for a specific period.
What is the difference between a term plan and life insurance?
A term plan is a type of life insurance that offers pure life cover for a fixed period without maturity benefits in most cases. Life insurance is a broader category that includes term plans, endowment plans, ULIPs, money-back policies, and other plans that may combine protection with savings or investment features.
Despite the various differences between Term Insurance vs Life Insurance, both plans share a common base.
Death benefit: Both pay your nominee if you die during the policy term.
Tax benefits: Premiums qualify for a deduction under the old tax regime, and the death benefit is tax-free in both.
Riders: Both let you add riders such as critical illness, accidental death and waiver of premium.
Underwriting: Premiums in both depend on your age, health, lifestyle and habits such as smoking.
Regulation: Both are regulated by IRDAI and come with a free-look period to cancel the policy if you change your mind after buying.
Term insurance and savings-linked life insurance solve different problems. A term plan gives your family the largest possible safety net for the lowest premium, but pays nothing if you outlive it. Endowment, money-back, ULIP and whole life plans return money to you, but offer far less cover for the same premium. For most earning adults with dependents, a term plan is the base of financial protection. A savings-linked plan can sit on top of it when you have a clear goal and the budget for it. Compare plans, check the claim settlement ratio, and buy early to lock in a lower premium.
If yes, Please rate us.

˜The insurers/plans mentioned are arranged in order of highest to lowest Sum Assured(SA) offered by Policybazaar’s insurer partners offering term insurance plans on our platform, as per ‘first year premium of life insurers as at 31.03.2025 report’ published by IRDAI.
Policybazaar Insurance Brokers Private Limited does not endorse, rate or recommend any particular insurer or insurance product offered by any insurer. For complete list of insurers in India refer to the IRDAI website www.irdai.gov.in
+On the basis of your profile
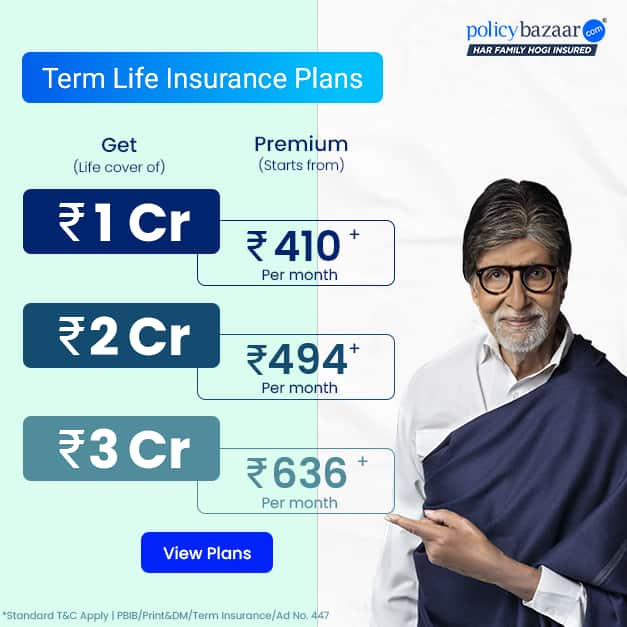
+Rs. 410/month is starting price for a 1 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age, rounded off to nearest 10
+Rs. 410/month (Rs.14/day) is starting price for a 1 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age rounded off to nearest 10
+Rs. 245 is starting price for a 50 lakhs term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 8/day is starting price for a 50 lakhs term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age, rounded off to nearest 10
+Rs. 15/day is starting price for a 75 lakhs term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age, rounded off to nearest 10
+Rs. 504/month is starting price for a 1.5 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 494/month is starting price for a 2 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 636/month is starting price for a 3 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 918/month is starting price for a 5 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 1,286/month is starting price for a 7 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 453/month is starting price for a 1 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs.582/month is starting price for a 2 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 786/month is starting price for a 3 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 1,374/month is starting price for a 5 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 1,592/month is starting price for a 7 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 525/month is the starting price for a 1 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 68 years of age.
+Rs. 668/month is starting price for a 2 crore term life insurance for an 25 year-old male, non-smoker, with no pre-existing diseases, cover upto 45 years of age.
+Rs. 1,200/month is starting price for a 2 crore term life insurance for an 35 year-old male, non-smoker, with no pre-existing diseases, cover upto 55 years of age.
+Rs. 410/month is starting price for a 1 crore term life insurance for an 18 year-old Female, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 577/month is starting price for a 1 crore term life insurance for an 18 year-old Male, self employed, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
*The full refund of premium is available on availing the one-time option of refund of premium. Total premium paid for policy (paid for add-ons) will be the special exit value, payable on availing the one-time option of refund of premium if you wish to completely exit the policy.
+Rs. ₹361/month is the starting price for a ₹1 crore loan cover with an 8% interest rate for an 18-year-old male, non-smoker, with no pre-existing diseases, loan tenure up to 20 years, rounded off to the nearest 10
Prices offered by the insurer are as per the approved insurance plans | #All savings and online discounts are provided by insurers as per IRDAI approved insurance plans | Standard Terms and Conditions Apply | **Tax Benefits are subject to changes in tax laws.| Policybazaar Insurance Brokers Private Limited
We will respond in the first instance within 30 minutes of the customers contacting us. 30-minute claim support service is for the purpose of giving reasonable assistance to the policyholder in pursuance of the claim. Settlement of claim (including cashless claim) is the responsibility of the insurer as per policy terms and conditions. The 30-minute claim support is subject to our operations not being impacted by a system failure or force majeure event or for reasons beyond our control. For further details, 24x7 Claims Support Helpline can be reached out at 1800-258-5881
For more details on risk factors, terms and conditions, please read the sales brochure carefully before concluding a sale
Policybazaar Insurance Brokers Private Limited | CIN: U74999HR2014PTC053454 | Registered Office - Plot No.119, Sector - 44, Gurgaon, Haryana – 122001 | Registration No. 742, Valid till 09/06/2027, License category- Composite Broker Visitors are hereby informed that their information submitted on the website may be shared with insurers. Product information is authentic and solely based on the information received from the insurers.
© Copyright 2008-2026 policybazaar.com. All Rights Reserved
˜ Policybazaar Promise reflects the guarantee offered by insurers. Price assurance is based on certifications shared by insurers with us.
SBI Life Smart Swadhan Supreme is a term insurance plan that
Read more
SBI Life Smart Swadhan Neo (UIN: 111N148V01) is a life insurance
Read more
ABSLI Life Shield Plan Premium starts
Read more
ABSLI Life Shield Plan Premium starts
Read more
ABSLI Life Shield Plan Premium starts
Read moreInsurance
Calculators
Resources
Payment Methods


Secured With

Follow us on


