









Download the Policybazaar app
to manage all your insurance needs.
High net worth individuals (HNIs) are people with a large amount of investable money. In India, an HNI is generally someone with ₹5 crore or more in investable assets. Let us take a look at what HNI means, how HNIs are classified in India, what HNI means in the stock market and in IPOs, how wealth management and estate planning work for high net worth individuals, and what the latest data says about HNI term insurance.


HNI stands for high net worth individuals. In India, a person with ₹5 crore or more in investable assets (excluding the house they live in) is usually considered an HNI. HNIs are also grouped into three levels: HNI, very high net worth individuals (VHNIs) and ultra high net worth individuals (UHNIs).

Term Plans
As we have understood the HNI meaning, let’s now learn about who is HNI in India and its types:
High Net Worth Individuals (HNIs): Investors whose liquid assets are valued between Rs. 5 Lacs and Rs. 5 Crores.
Very High Net Worth Individuals (VHNIs): Investors whose liquid assets are valued between Rs. 5 Crore and Rs. 25 Crore.
Ultra High Net Worth Individuals (UHNIs): Investors whose liquid assets are more than Rs. 25 Crores.
Secure Your Family Future Today
₹1 CRORE
Term Plan Starting @
Get an online discount of upto 15%#
Compare 40+ plans from 15 Insurers
Nobody has an exact count of HNIs in India, because the definition isn't fixed. The ultra high net worth group is easier to track. As per Knight Frank's Wealth Report 2026, India has 19,877 UHNWIs (net worth of US$30 million or more) and 207 billionaires. The number of UHNWIs grew by about 63% between 2021 and 2026, and India now ranks sixth in the world on this count.
Knight Frank expects India to have about 25,217 UHNWIs by 2031. Mumbai has the biggest share, with 35.4% of the country's ultra rich, but the report says wealth is slowly spreading to other cities too.
Wealth Accumulation: Most HNIs built their wealth through a business, investments, inheritance or a well-paid job, and many through a mix of these. That money gives them a comfortable lifestyle and more options when it comes to investing.
Investment Portfolio: The portfolio of a high net worth individual is usually spread across shares, bonds, real estate, private equity and other alternative investments. A lot of HNIs also use a wealth manager to look after it and keep it growing.
Access to Exclusive Services: HNIs often get services that regular customers don’t. Private banking, wealth management advice, tax planning and estate planning are the common ones, and they are built around the HNI’s own situation.
Philanthropy and Giving Back: Many HNIs give to charity. They put money into education, healthcare and other social causes, and some set up a trust or a foundation for it.
Global Reach: Some HNIs have investments or business interests in more than one country. They spread their money across different markets, so they aren’t depending on one economy.
Now that we have learned the HNI full form and HNI meaning let us take a look at the term life insurance plans for HNIs in India:
| Name of the Insurer | Term Insurance Plan | Claim Settlement Ratio | Entry Age | Maximum Maturity Age |
| Aditya Birla Sun Life Insurance Company Limited | ABSLI Income Suraksha Plan | 98.86 | 21-55 years | 70 years |
| Aviva Life Insurance Company India Limited | Aviva Signature 3D Term Plan | 99.07 * | 18-65 years | 80 years |
| Axis Max Life Insurance Company Limited | Max Life Smart Total Elite Protection | 99.8 | 18-65 years | 85 years |
| Bandhan Life Insurance Limited | Bandhan Life iTerm Prime | 98.15 | 18-65 years | 70 years |
| Bajaj Allianz Life Insurance Company Limited | Bajaj Allianz eTouch | 99.33 | 18-55 years | 99 years |
| Bharti Axa Life Insurance Company Limited | Flexi Term Pro | 99.21 | 18-65 years | 99 years |
| Canara HSBC Life Insurance Company Limited | Canara Young Term Plan | 99.52 | 18-45 years | 99 years |
| Edelweiss Life Insurance Company Limited | Edelweiss Life Zindagi Plus | 99.31 | 18-65 years | 80 years |
| Generali Central Life Insurance Company Limited | Generali Central Term Insurance Plan | 99.57 | 18-60 years | 65 years |
| HDFC Life Insurance Company Limited | HDFC Click 2 Protect Super | 99.72 | 18-65 years | 85 years |
| ICICI Life Insurance Company Limited | ICICI iProtect Smart | 99.3 | 18-65 years | 99 years |
| IndiaFirst Life Insurance Company Limited | IndiaFirst Life Elite Term Plan | 98.78 | 18-60 years | 99 years |
| Kotak Mahindra Life Insurance Company Limited | Kotak e Term | 99.50 | 18-65 years | 85 years |
| Life Insurance Corporation of India | LIC New Tech Term Plan | 99.44 | 18-65 years | 80 years |
| PNB MetLife India Insurance Company Limited | PNB MetLife Mera Term Plan Plus | 99.81 | 18-50 years | 80 years |
| Pramerica Life Insurance Company Limited | Pramerica Life Rock Solid Plan | 99.29 | 18-65 years | 85 years |
| SBI Life Insurance Company Limited | SBI eShield Next Plan | 96.81** | 18-65 years | 100 years |
| Shriram Life Insurance Company Limited | Shriram Life Smart Protection Plan | 99.52 | 18-65 years | 75 years |
| Star Union DAI-ICHI Life Insurance Company Limited | SUD Life Protect Shield Plus | 99.01 | 18-60 years | 80 years |
| Tata AIA Life Insurance Company Limited | Tata AIA Maha Raksha Supreme Select | 99.45 | 18-65 years | 100 years |
*Disclaimer: The list of insurers mentioned are arranged according to the alphabetical order of the name of insurance company respectively. Policybazaar does not endorse, rate or recommend any particular insurer or insurance product offered by any insurer. The list of plans listed here comprise of insurance products offered by all the insurance partners of Policybazaar. For complete list of insurers in India refer to the Insurance Regulatory and Development Authority of India website www.irdai.gov.in
CSR is the individual death claim settlement ratio for FY 2025-26, from each insurer’s official sources. * FY 2024-25 figure, as no FY 2025-26 figure was available. ** Q1 FY 2026-27 only.
You can use the term insurance premium calculator to check the premiums you need to pay for the desired life cover.
High cover for a low premium: A best term plan gives you a lot more cover than an endowment or money-back plan for the same premium. That is why a ₹5 crore or ₹10 crore cover is still possible for most high net worth individuals without a big yearly cost.
Your family is covered even when markets are down: Most of an HNI’s money sits in shares, mutual funds, property or a business, and the value keeps moving. A term plan pays a fixed amount if you die during the policy term, whatever the markets are doing.
Tax benefits: You can claim the premium as a deduction under Section 80C, up to ₹1.5 lakh a year, but only if you file under the old tax regime. The death benefit your family gets is tax-free under Section 10(10D), in both regimes. From FY 2026-27, the Income Tax Act, 2025 assigns new section numbers to these provisions: Section 123 for the premium deduction and Section 11, read with Schedule II, for the payout. Check with your tax adviser for your own case.
Zero GST: There has been no GST on individual term insurance premiums since 22 September 2025. It used to be 18%. On a ₹5 crore or ₹10 crore cover, that saving is noticeable every year.
Clears loans and debts: Your family can use the payout to repay home loans, business loans and other liabilities, so they don’t have to sell assets to do it.
Riders for extra cover: You can add riders for critical illness, accidental death, accidental total and permanent disability (ATPD) and waiver of premium.
Yes, most of them do need a life insurance policy. A lot of people think that if you have ₹5 crore or more, you don't need life insurance. But having assets is not the same as having cash your family can use. HNI wealth is often locked in shares, mutual funds, property or a business, and it can take time (or a loss) to sell. At the same time, home loans, business loans, children's education and the family's lifestyle all depend on your income.
A term plan with high cover takes care of that gap. Your family gets a lump sum and doesn't have to sell investments or property in a hurry. If your net worth is not enough to support your family for the rest of their lives without your income, you should think about buying protection for your loved ones in case of your absence.
HNI demand for term insurance in India has grown sharply in both volume and cover size. Based on Policybazaar's data, these are the key trends shaping the segment:
Bookings have doubled: HNI term insurance bookings have grown by roughly 100% since April 2023, and the average ticket size has risen by about 30%.
Younger buyers lead growth: Nearly 50% of HNI customers are below the age of 35. This growth comes not only from existing policyholders topping up their cover, but also from younger HNIs buying higher protection for the first time.
Multi-crore covers are gaining traction: Policies with ₹3 crore and above cover have risen by about 25%. This has accelerated further since the introduction of zero GST on term insurance. Policybazaar also says ₹5 crore-plus policies have nearly tripled under the zero-GST regime.
| Life cover amount | Share of HNI buyers |
| ₹3 crore and above | 25% |
| ₹5 crore and above | 5% |
| ₹7 crore and above | 1.5% |
| ₹10 crore and above | 1% |
Average and highest cover: Salaried HNIs buy an average cover of about ₹2 crore. The highest sum assured bought on the platform by an HNI customer is ₹25 crore.
Riders are in demand: HNIs are adding protection beyond death cover. Accidental Total and Permanent Disability (ATPD) and Critical Illness are the most popular riders.
| Rider | Share of HNI customers |
| Accidental Total & Permanent Disability (ATPD) | 20% |
| Critical Illness | 15% |
| Accidental Death Benefit | 9% |
| Waiver of Premium (WOP) | 8% |
Pure protection over return of premium: As per Policybazaar data, fewer than 5% of HNI customers choose Term Return of Premium (TROP) plans. Most HNIs buy a regular term plan for the cover alone, and smart exit options on newer plans make that choice easier.
Limited pay is gaining ground: As per Policybazaar data, only about 40% of HNI customers choose regular pay. The rest go for limited pay or pay-till-60, so they can finish paying premiums early and not carry the cost through the whole policy term.
City-wise demand: Bengaluru and Hyderabad lead in HNI policy count. Mumbai, Gurgaon, Faridabad and Bengaluru have the highest average sum assured.
Women’s participation: Women made up about 18% of HNI term insurance buyers last year, and men the other 82%.
Source: Policybazaar data, as reported by Insurance Edge on 29 October 2026.
There is no fixed number. Salaried HNIs on Policybazaar buy about ₹2 crore on average, but a business owner with loans and a big family may need a lot more. A simple way to work it out:
Add up your loans: home loan, business loan, personal loans, anything your family would have to pay back.
Add the money your family needs every year to live the way they do now, for the years they would depend on your income.
Add big goals like children's education, a parent's care or a spouse's retirement.
Subtract the investments and existing life cover your family could actually use without selling in a hurry.
Keep a cushion for inflation. Some advisers suggest 5-7% a year, or you can pick a plan where the cover goes up every year.
Whatever number you reach, the insurer has the last word. IRDAI doesn't set one limit for everyone. Each insurer decides based on your income, job, health and the life cover you already have. For high covers, like ₹5 crore and above, expect to share proof of income (ITR for the last few years, Form 16 or salary slips, bank statements) and to do medical tests. Business owners may be asked for business financials as well. Tell the insurer everything honestly at this stage. It makes a claim much easier later.
Financial Protection for Loved Ones: If a policyholder dies, the family still needs money to carry on. Life insurance for HNIs gives them that. An HNI often supports more than a spouse and children. Parents, business partners or a charity may depend on the income too. The payout helps make sure each of them is looked after.
Estate Planning and Wealth Transfer: Life insurance works well alongside estate planning. It gives your family cash for settlement costs, legal fees and other expenses after you pass away. India doesn’t charge estate tax or inheritance tax right now, but moving property, shares and business stakes to legal heirs still takes time and money. Insurance money comes quickly. It can also help split wealth fairly when one asset, like a business or a house, can’t be divided easily. That way the wealth transfer goes the way you planned, and your heirs aren’t left short of cash.
Business Continuity: HNIs often have business interests, such as ownership stakes or leadership roles in companies. Life insurance for HNIs can be instrumental in ensuring the smooth transition of business ownership and maintaining business continuity in the event of their death. It can provide funds to facilitate buy-sell agreements, fund key person insurance, or provide capital for the business to weather the financial impact of the individual's absence.
Philanthropic Objectives: Many HNIs actively engage in philanthropy and charitable giving. Life insurance can be used to create a legacy of giving by designating charitable organizations as beneficiaries. This allows HNIs to support causes they care about while potentially enjoying tax benefits.
Risk Management: While HNIs may have substantial wealth, they are not immune to financial risks. Life insurance can serve as a risk management tool, providing a financial safety net and mitigating potential risks associated with unforeseen events, liabilities, or business ventures. It can offer peace of mind, knowing that financial obligations will be met, and loved ones will be protected.
Once your wealth grows past a point, handling it on your own gets complicated. Wealth management for high net worth individuals means one adviser or one team looks at your investments, taxes, insurance, property, business and family plans together, so they don't get handled in separate pieces. Services for HNIs usually include private banking, investment advice, tax planning, estate planning, insurance, and loans against shares or property. Lets go through it in six parts: financial planning, estate planning, investments, HNI banking and private banking, and the family office.
Financial planning for HNIs starts with goals: when you want to stop working, what you want to leave behind, and how much risk you can take. After that the plan covers where the money is invested, tax planning, emergency funds, insurance and a yearly review. Insurance isn't an extra in this. A term plan covers your family's income, and health insurance keeps a hospital bill from eating into your savings. HNW financial planning is not a one-time job, so most people review it every year, or after a big change like selling a business. Tax planning is part of this too. The new tax regime is now the default, and it does not allow deductions like Section 80C, while the old regime does. Which one works out cheaper depends on your income and how many deductions you actually claim, so it is worth checking every year.
Estate planning is about what happens to your assets when you are no longer around. The basics are simple. Write a will, and register it if you can. Add nominees on every bank account, demat account, mutual fund folio and insurance policy. Some families also set up a private trust. These are the common estate planning strategies for HNIs, and the right mix depends on how many heirs you have and what kind of assets you hold. Many Indian families also use a HUF (Hindu Undivided Family) for family assets. It is open to Hindu, Jain, Sikh and Buddhist families and is taxed as a separate entity. A private family trust is the other common route: the trust deed decides who gets what, and when. A CA or a lawyer can tell you which one fits your family.
One thing people miss: a nominee and a legal heir are not always the same. For some assets the nominee only holds the money, and the will or succession law decides who finally gets it. So keep the will and the nominations in line with each other, and talk to a lawyer or a chartered accountant for your own case.
Life insurance helps here because the money goes to the person you named in the policy, and it usually doesn't have to wait for the rest of the estate to be settled.
HNIs usually spread their money across shares, mutual funds, bonds and fixed income, real estate and gold. Some add products that are only open to bigger investors. Portfolio management services (PMS) need a minimum investment of ₹50 lakh, and alternative investment funds (AIFs) need at least ₹1 crore. Some HNIs also invest abroad, and under the Liberalised Remittance Scheme a resident individual can send up to US$250,000 a year overseas. What suits you depends on your goals, how long you can stay invested and how much risk you can handle. Investments for HNIs don't replace life cover. They solve different problems.
If you are an NRI HNI with money in India, the rules are a bit different. NRIs usually invest through NRE and NRO accounts, and FEMA rules decide what they can invest in and how money moves in and out of India. Their tax is also different from a resident's, so it helps to talk to an adviser who knows both sides.
Most large banks have a separate wealth or private banking service for HNIs. It usually comes with a relationship manager, priority service, investment advice, forex services and loans against shares or property. The entry rules for HNI banking (or HNWI banking) are different at every bank and are often based on how much you keep with the bank in total, so ask your bank what it needs. Private banking, sometimes called HNWI private banking, is usually aimed at VHNIs and UHNIs.
A family office is a private set-up that manages the wealth of one family (a single family office) or a few families together (a multi-family office). It looks after investments, taxes, legal work and succession planning. Running one costs a lot, so it usually makes sense only for UHNIs.
HNI full form is High-Net-Worth Individuals (HNIs) and they are individuals who have amassed significant wealth, generally exceeding a specific threshold of investable assets. They possess a unique financial status that comes with opportunities and challenges. Through effective wealth management, prudent investment strategies, and careful consideration of financial and lifestyle goals, HNIs can leverage their wealth to make a positive impact and secure their financial legacies.
If yes, Please rate us.

˜The insurers/plans mentioned are arranged in order of highest to lowest Sum Assured(SA) offered by Policybazaar’s insurer partners offering term insurance plans on our platform, as per ‘first year premium of life insurers as at 31.03.2025 report’ published by IRDAI.
Policybazaar Insurance Brokers Private Limited does not endorse, rate or recommend any particular insurer or insurance product offered by any insurer. For complete list of insurers in India refer to the IRDAI website www.irdai.gov.in
+On the basis of your profile
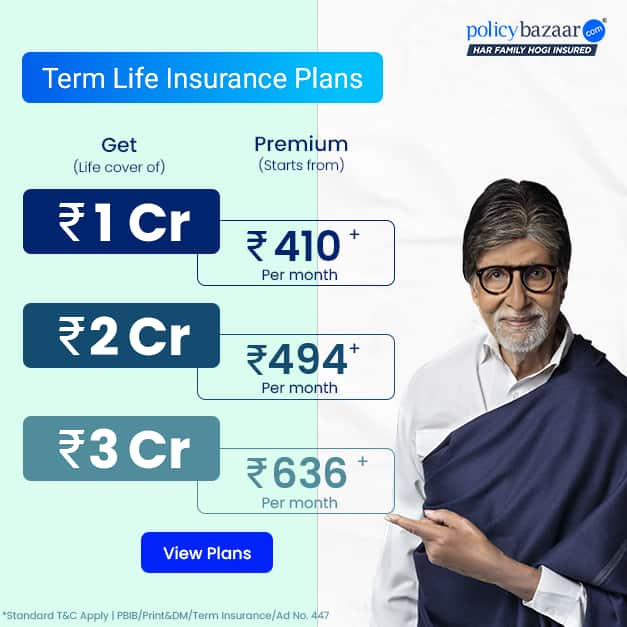
+Rs. 410/month is starting price for a 1 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age, rounded off to nearest 10
+Rs. 410/month (Rs.14/day) is starting price for a 1 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age rounded off to nearest 10
+Rs. 245 is starting price for a 50 lakhs term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 8/day is starting price for a 50 lakhs term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age, rounded off to nearest 10
+Rs. 15/day is starting price for a 75 lakhs term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age, rounded off to nearest 10
+Rs. 504/month is starting price for a 1.5 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 494/month is starting price for a 2 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 636/month is starting price for a 3 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 918/month is starting price for a 5 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 1,286/month is starting price for a 7 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 453/month is starting price for a 1 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs.582/month is starting price for a 2 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 786/month is starting price for a 3 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 1,374/month is starting price for a 5 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 1,592/month is starting price for a 7 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 525/month is the starting price for a 1 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 68 years of age.
+Rs. 668/month is starting price for a 2 crore term life insurance for an 25 year-old male, non-smoker, with no pre-existing diseases, cover upto 45 years of age.
+Rs. 1,200/month is starting price for a 2 crore term life insurance for an 35 year-old male, non-smoker, with no pre-existing diseases, cover upto 55 years of age.
+Rs. 410/month is starting price for a 1 crore term life insurance for an 18 year-old Female, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 577/month is starting price for a 1 crore term life insurance for an 18 year-old Male, self employed, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
*The full refund of premium is available on availing the one-time option of refund of premium. Total premium paid for policy (paid for add-ons) will be the special exit value, payable on availing the one-time option of refund of premium if you wish to completely exit the policy.
+Rs. ₹361/month is the starting price for a ₹1 crore loan cover with an 8% interest rate for an 18-year-old male, non-smoker, with no pre-existing diseases, loan tenure up to 20 years, rounded off to the nearest 10
Prices offered by the insurer are as per the approved insurance plans | #All savings and online discounts are provided by insurers as per IRDAI approved insurance plans | Standard Terms and Conditions Apply | **Tax Benefits are subject to changes in tax laws.| Policybazaar Insurance Brokers Private Limited
We will respond in the first instance within 30 minutes of the customers contacting us. 30-minute claim support service is for the purpose of giving reasonable assistance to the policyholder in pursuance of the claim. Settlement of claim (including cashless claim) is the responsibility of the insurer as per policy terms and conditions. The 30-minute claim support is subject to our operations not being impacted by a system failure or force majeure event or for reasons beyond our control. For further details, 24x7 Claims Support Helpline can be reached out at 1800-258-5881
For more details on risk factors, terms and conditions, please read the sales brochure carefully before concluding a sale
Policybazaar Insurance Brokers Private Limited | CIN: U74999HR2014PTC053454 | Registered Office - Plot No.119, Sector - 44, Gurgaon, Haryana – 122001 | Registration No. 742, Valid till 09/06/2027, License category- Composite Broker Visitors are hereby informed that their information submitted on the website may be shared with insurers. Product information is authentic and solely based on the information received from the insurers.
© Copyright 2008-2026 policybazaar.com. All Rights Reserved
˜ Policybazaar Promise reflects the guarantee offered by insurers. Price assurance is based on certifications shared by insurers with us.

Life insurance fraud is a serious financial crime in India
Read more
High net worth individuals often opt for life insurance plans to
Read more
Yes, ICICI Life is one of the leading life insurance companies
Read more
“I recently bought an HDFC term plan and it is the best
Read more
The life insurance policy in India is a type of life insurance
Read moreInsurance
Calculators
Resources
Payment Methods


Secured With

Follow us on


