






Download the Policybazaar app
to manage all your insurance needs.
When you apply for term insurance, the insurer doesn’t simply issue the policy without assessing certain factors. They follow a process known as underwriting, which evaluates the risk associated with insuring you. Underwriting plays a critical role in determining whether your policy will be approved, how much premium you’ll pay, and the extent of coverage you’ll receive. Let us understand the concept of underwriting in term insurance, how it works, what factors are considered, and how it impacts your policy.


Underwriting is the process by which a term insurance company assesses your health, lifestyle, and other risk factors to determine whether they can provide you with term insurance coverage. This assessment helps insurers decide:
Whether to approve or reject your policy application.
The premium rate you will pay for your policy.
The amount of coverage (sum assured) you qualify for.
The goal of underwriting is to protect the life insurance company from taking on excessive risk by ensuring that the premium you pay reflects your risk profile.

Term Plans
The underwriting process in term insurance typically follows these steps:
You begin by filling out an application form for term or life insurance. The form will require details such as personal information (age, gender, occupation), medical history and family health history, lifestyle choices (such as smoking or drinking habits), and financial details (if applicable).
Many insurance companies require a medical examination as part of the underwriting process. The examination checks your overall health and identifies potential health risks. Tests may include blood pressure measurements, cholesterol levels, and other routine checks. For younger and healthier applicants, some insurers may offer term insurance without medical exam for a relatively low coverage amount.
The underwriter will review the information provided on your application, along with the results of your medical examination. This review helps the insurer assess the level of risk you pose as an applicant. Key factors include existing medical conditions (such as diabetes, hypertension, etc.), family medical history (genetic predisposition to diseases like cancer or heart conditions), and high-risk lifestyle habits (smoking, excessive drinking, etc.).
If you’re applying for a high sum assured, insurers may also assess your financial background to ensure that the coverage aligns with your income. This is done to prevent over-insurance, where the coverage amount is significantly higher than the applicant’s earning capacity. To check the ideal cover amount for your profile, you can use the human life value calculator or the HLV calculator, free of cost online.
After the risk classification, the insurer will either approve or reject your application. If approved, they will offer you a policy with a specific coverage amount and premium.
Secure Your Family Future Today
₹1 CRORE
Term Plan Starting @
Get an online discount of upto 15%#
Compare 40+ plans from 15 Insurers
Several factors come into play during the underwriting process. Understanding these can help you better prepare when buying term insurance.
Age is a major factor in determining your regular and annualised premium. Younger individuals typically pose lower risks, so they tend to pay lower premiums compared to older applicants.
Your current health status is thoroughly evaluated through medical exams and past health records. If you have any chronic conditions (like diabetes or heart disease), it may lead to higher premiums or even rejection of coverage.
Underwriters assess lifestyle choices such as:
Smoking: Smokers are at a higher risk of developing serious illnesses, so they are charged higher premiums.
Alcohol Consumption: Excessive drinking can also lead to higher risks and increased premiums.
Exercise and Diet: A healthy lifestyle may help you qualify for lower premiums.
High-risk jobs (such as construction, mining, or working in hazardous environments) can result in higher premiums since the likelihood of accidents or illness is greater.
If your family has a history of serious illnesses like cancer or heart disease, you may be placed in a higher-risk category, even if you’re currently healthy.
In some cases, gender can play a role in underwriting. For example, women generally live longer than men, which might result in lower premiums for females when buying term insurance for women in India.
There are different types of underwriting methods that insurers use to evaluate applicants. Here are the most common ones:
This involves a detailed review of your medical history and lifestyle, often requiring a medical examination. Medical underwriting is typically used for high-coverage policies.
This is used for low-coverage policies or for individuals who meet specific age and health criteria. It requires minimal medical information, and a medical exam is usually not needed.
This method involves a short questionnaire about your health but does not require a medical exam. It is faster but often comes with higher premiums due to the lack of detailed risk assessment.
No medical exams or health questions are required, and the policy is issued to anyone who applies. This is often used for small-coverage policies but comes with much higher premiums due to the risk for the insurer.
The underwriting process has a direct impact on the following aspects of your term insurance policy:
Your premium is determined based on the risk assessment. The higher the perceived risk (due to factors like health, age, or lifestyle), the higher the premium you’ll pay.
The insurer may limit the sum assured based on your financial profile and risk level. If they believe the coverage is too high in relation to your income or risk profile, they may offer a lower coverage amount.
In cases where the risk is deemed too high, the insurer may reject your application. High-risk factors like severe health conditions or risky lifestyle habits can lead to rejection.
Underwriting is an essential part of the term insurance process, ensuring that insurers can assess and manage the risk of providing coverage. By evaluating factors such as age, health, lifestyle, and occupation, the insurer determines your eligibility, premium rates, and coverage amount. While underwriting may seem complex, it ultimately helps balance the interests of both the insurer and the policyholder. By understanding how underwriting works, you can better prepare yourself for the process and make informed decisions when purchasing term insurance.
Note: You should also check the benefits of term life insurance if you are planning to purchase the term insurance plan.
If yes, Please rate us.

˜The insurers/plans mentioned are arranged in order of highest to lowest Sum Assured(SA) offered by Policybazaar’s insurer partners offering term insurance plans on our platform, as per ‘first year premium of life insurers as at 31.03.2025 report’ published by IRDAI.
Policybazaar Insurance Brokers Private Limited does not endorse, rate or recommend any particular insurer or insurance product offered by any insurer. For complete list of insurers in India refer to the IRDAI website www.irdai.gov.in
+On the basis of your profile
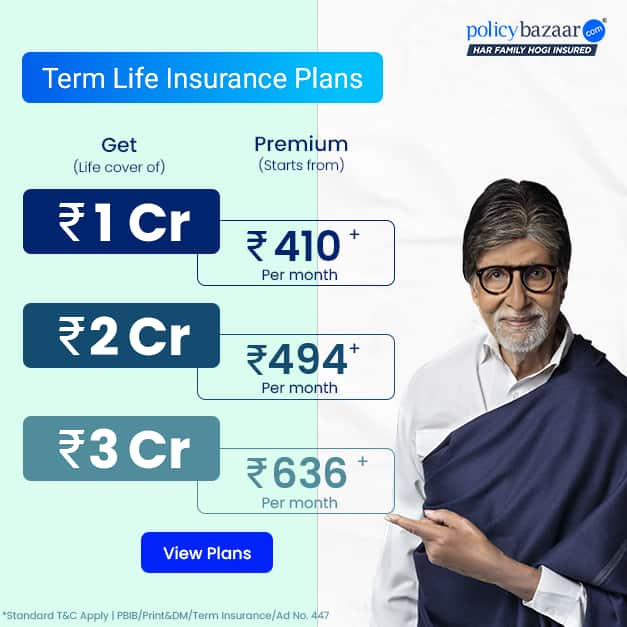
+Rs. 410/month is starting price for a 1 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age, rounded off to nearest 10
+Rs. 410/month (Rs.14/day) is starting price for a 1 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age rounded off to nearest 10
+Rs. 245 is starting price for a 50 lakhs term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 8/day is starting price for a 50 lakhs term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age, rounded off to nearest 10
+Rs. 15/day is starting price for a 75 lakhs term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age, rounded off to nearest 10
+Rs. 504/month is starting price for a 1.5 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 494/month is starting price for a 2 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 636/month is starting price for a 3 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 918/month is starting price for a 5 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 1,286/month is starting price for a 7 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 453/month is starting price for a 1 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs.582/month is starting price for a 2 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 786/month is starting price for a 3 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 1,374/month is starting price for a 5 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 1,592/month is starting price for a 7 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 525/month is the starting price for a 1 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 68 years of age.
+Rs. 668/month is starting price for a 2 crore term life insurance for an 25 year-old male, non-smoker, with no pre-existing diseases, cover upto 45 years of age.
+Rs. 1,200/month is starting price for a 2 crore term life insurance for an 35 year-old male, non-smoker, with no pre-existing diseases, cover upto 55 years of age.
+Rs. 410/month is starting price for a 1 crore term life insurance for an 18 year-old Female, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 577/month is starting price for a 1 crore term life insurance for an 18 year-old Male, self employed, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
*The full refund of premium is available on availing the one-time option of refund of premium. Total premium paid for policy (paid for add-ons) will be the special exit value, payable on availing the one-time option of refund of premium if you wish to completely exit the policy.
+Rs. ₹361/month is the starting price for a ₹1 crore loan cover with an 8% interest rate for an 18-year-old male, non-smoker, with no pre-existing diseases, loan tenure up to 20 years, rounded off to the nearest 10
Prices offered by the insurer are as per the approved insurance plans | #All savings and online discounts are provided by insurers as per IRDAI approved insurance plans | Standard Terms and Conditions Apply | **Tax Benefits are subject to changes in tax laws.| Policybazaar Insurance Brokers Private Limited
We will respond in the first instance within 30 minutes of the customers contacting us. 30-minute claim support service is for the purpose of giving reasonable assistance to the policyholder in pursuance of the claim. Settlement of claim (including cashless claim) is the responsibility of the insurer as per policy terms and conditions. The 30-minute claim support is subject to our operations not being impacted by a system failure or force majeure event or for reasons beyond our control. For further details, 24x7 Claims Support Helpline can be reached out at 1800-258-5881
For more details on risk factors, terms and conditions, please read the sales brochure carefully before concluding a sale
Policybazaar Insurance Brokers Private Limited | CIN: U74999HR2014PTC053454 | Registered Office - Plot No.119, Sector - 44, Gurgaon, Haryana – 122001 | Registration No. 742, Valid till 09/06/2027, License category- Composite Broker Visitors are hereby informed that their information submitted on the website may be shared with insurers. Product information is authentic and solely based on the information received from the insurers.
© Copyright 2008-2026 policybazaar.com. All Rights Reserved
˜ Policybazaar Promise reflects the guarantee offered by insurers. Price assurance is based on certifications shared by insurers with us.
SBI Life Saral Swadhan Supreme is a term insurance plan that
Read more
SBI Life Smart Swadhan Supreme is a term insurance plan that
Read more
SBI Life Smart Swadhan Neo (UIN: 111N148V01) is a life insurance
Read more
ABSLI Life Shield Plan Premium starts
Read more
ABSLI Life Shield Plan Premium starts
Read moreInsurance
Calculators
Resources
Payment Methods


Secured With

Follow us on


