








Download the Policybazaar app
to manage all your insurance needs.
Buying term insurance without a medical test in India is quick and simple, but it is usually limited to certain conditions. Young, healthy people and those who choose a lower sum assured can get a plan with no medical test from several insurers. You need to complete a health self-declaration. If you want a high cover or already have health problems, a physical check-up is required to set the right premium and keep the policy valid at claim time.


Yes, you can buy term life insurance without medical test. Many life insurance providers offer term life insurance without medical tests. Under a term plan without a medical test, the insurance holder is not required to undergo any medical screening when purchasing the policy. The insurer relies on the health and lifestyle answers in your application instead, which is why accurate answers matter later, at claim time. The insurance company allows the policyholder to purchase the term plan without medical tests, considering the policyholder’s age and the sum assured amount they chose. However, if the insurance buyer has any pre-existing medical problems or illnesses, they are likely to be asked to take a medical exam while buying the policy.
Age, lifestyle, and family medical history are some of the important factors that insurers consider when offering term plans without a medical test. A term plan without medical test in India is regulated like any other life insurance policy, so the same disclosure rules apply.

Term Plans
A term plan without medical test in India is a regular term plan where the insurer skips the physical check-up and decides on your declared health, age, income and sum assured. It is still underwritten, so the insurer can ask for a test after you apply. Rules on non-disclosure under Section 45 of the Insurance Act, 1938 apply to these plans in the same way as to plans that need a test. Because limits differ by insurer, compare the no-medical limits of each plan, not just the premium.
Secure Your Family Future Today
₹1 CRORE
Term Plan Starting @
Get an online discount of upto 15%#
Compare 40+ plans from 15 Insurers
Insurers need medical tests to determine the life cover and premium rates based on the medical history and health conditions of an applicant. The results of full body check ups or medical tests help insurance companies check the level of fitness and overall health of policyholders. Based on this information, they can decide the premium rate. Also note that an insurer can reject a death claim if it can show that you hid or misstated a material health fact when buying the policy. A condition you disclosed is not a ground for rejection; one you concealed can be.
Read on to more about the importance of medical tests in term insurance:
Medical tests reduce the difficulties at the stage of claim
Once the insurer is satisfied with the overall health condition of an applicant based on the medical tests, they can decide the life cover and premium rates. It decreases the risk of conflicts over health conditions at the time of claim settlement.
Good medical records help secure lower premium
A healthy individual can buy term plans at a lower premium because of lower risk of getting severe illnesses. Providing proof of good health through a medical test or self-declaration helps the applicant get financial protection at low premiums.
Medical Tests Allow Insurance Companies to Offer a High Life Cover
Some of the insurance companies offer term plans without medical tests which come with some restrictions. A lower sum assured in a term insurance plan without medical test might not be sufficient to cover the dependent’s financial expenses in case of your absence.
Buying a term plan with medical test can help you prove your good medical condition. In exchange, you get the approval for a higher amount of sum assured for wide life insurance coverage.
Medical tests are generally required when you want to buy a higher sum assured, i.e., ₹1 crore and above. Tests may also be required when you are above the age of 40 years. In some cases, if you have a medical history that includes ailments such as diabetes and heart problems, you may be required to go through medical tests. In addition, if you want to buy a longer term insurance plan that is above 30 years, medical tests may be required. Here is a list of some points you need to keep in mind:
Age: Young policy buyers with a low amount of coverage and good medical condition may be eligible for term insurance without medical test.
Common medical tests needed: Some of the medical examinations required by the insurer are:
Blood pressure
Urine Tests
Cholesterol levels
Blood sugar levels
Some additional tests may also be required by the insurer based on the history of lifestyle related health risks and severe diseases.
Term Insurance Without Medical Test
A lot of insurance companies now offer term insurance without medical tests. This means:
Faster policy approval
Minimal health documentation
A simpler route for applicants with no significant health history
To avoid having your claim denied, always be honest about your medical history.
Check the age and sum assured limits for the plan to see if tests are needed.
Compare plans with no medical test if you want hassle-free and fast policy issuance.
When Can You Skip Medical Tests?
Some term insurance plans offer you a facility where you can buy a plan without having to undergo medical tests. This is usually when you opt for a lower amount assured up to ₹50 lakh. In addition, if you are younger than 35 years old and do not suffer from medical conditions, you can opt for such plans. In many cases, you can buy a plan based on the information you provide about your medical history during the application process. Some online or group term insurance plans can be bought without medical tests.
The sum assured you choose is one of the biggest factors in whether an insurer asks for a medical test, so it helps to look at how this works for a specific cover amount.
A 50 lakh term insurance without medical test is one of the most common no-medical options in India. If you are under 35, healthy and have no conditions to declare, many insurers will issue a ₹50 lakh cover on your self-declaration. Cover above ₹50 lakh usually needs a medical test, and the exact cut-off differs from one insurer to the next. Your income also matters, because the insurer checks that the cover is in line with what you earn. If you need more than ₹50 lakh, expect a test, or consider a smaller cover now and a higher one later through a top-up option.
Below are the common types of medical tests in term insurance:
Physical Tests
Insurers usually begin with basic health checks such as height, weight, body mass index (BMI), haemoglobin, blood pressure, and blood sugar levels. Depending on your age and medical profile, additional tests like lipid profile, complete blood count (CBC), HIV screening, urine tests, or echocardiography may also be required.
Telephonic Assessment
In some cases, insurers conduct a tele-medical interview where you are asked questions about your health history and lifestyle. It is important to provide accurate information during this discussion. Keeping your medical reports and prescriptions nearby can help you answer confidently.
Video MER
Some insurers also offer video medical examinations, where a doctor evaluates your health through a video consultation. This process helps verify medical details and identify any existing conditions that may require further assessment.
A physical check-up is only one way for an insurer to verify your health. When you buy a term plan without a medical check-up, the insurer replaces it with other checks:
Self-declaration: the application asks about existing conditions, medicines, surgeries, tobacco and alcohol use, and family history.
Tele-medical interview: a short call with a medical professional, usually only when something in your form needs clarifying.
Occupation and income details: used to decide whether the cover amount makes sense for you.
Cross-checks: the insurer may compare your answers with your other policies and past applications.
Term insurance without a medical test skips the check-up, not the underwriting. The insurer still prices your premium on the health details you declare, and it can ask for a medical test after you apply if your answers raise a question. If you have a pre-existing condition such as diabetes or high blood pressure, expect a test request, a higher premium, a lower sum assured, or in some cases a rejected application.
When you shortlist term insurance plans without medical check-up, compare these points across insurers:
No-medical limits: the maximum age and sum assured up to which the insurer waives the test.
Premium: whether the no-medical route costs more than the standard route for the same cover.
Claim settlement record: the insurer's claim settlement ratio and how it handles non-disclosure cases.
Top-up option: whether you can raise cover later without a test.
Riders: critical illness and waiver of premium options, and any added conditions for no-medical plans.
Life insurance without medical test is most easily available as term insurance. Other kinds of life insurance, such as savings and investment plans, may also be issued on a declaration for smaller covers, depending on the insurer and the plan. Whatever the type, the insurer relies on your declared health details, so accurate answers are what keep the policy valid at claim time.
You can get a better understanding of what is term insurance by taking a look at its benefits. The following are the major benefits offered by the term insurance policy.
Death Benefit: In case of the insured's unfortunate demise during the policy's tenure, a death benefit equal to the total sum assured amount is paid to the policy beneficiary. The term insurance plan ensures financial security for the insured's family against any type of emergency.
Maturity Benefit or Survival Benefit: In a pure-term insurance plan, no maturity benefit is offered to the insured person if he/she survives the entire policy tenure. However, in Term Return of the Premium Plan (TROP), the survival benefit is offered as the premium return to the insured if he/she survives the entire policy term. In the TROP plan, the total premium paid by the insured to date is returned after the completion of the policy term.
Tax Benefit: The premium qualifies for a deduction of up to ₹1.5 lakh a year under Section 80C of the Income Tax Act, 1961. From 1 April 2026 this deduction sits under Section 123 of the Income-tax Act, 2025, and it is available only if you file under the old tax regime, because the new regime is now the default. The death benefit your nominee receives is generally exempt from tax under Section 10(10D) of the 1961 Act, a provision carried into the 2025 Act, subject to the conditions in the law.
Additional Rider Benefits: Additional rider benefits are also provided by most term insurance plans. There are generally four different types of rider options offered by the term insurance plan.
Critical illness rider
Accidental death benefits rider
Waiver of premium rider
Accidental total and partial disability rider
Some insurers in India offer term insurance plans that can be purchased without undergoing medical tests. The process usually involves the following steps.
Application
Start by selecting an insurer that offers term insurance without medical tests. Compare plans based on coverage, premium, and policy benefits. Then fill out the online application with accurate details such as your age, occupation, and health history.
Underwriting
The insurance company checks the details you provided in the application and decides whether you are eligible for the policy. It may follow up on your answers, by phone or by asking for a medical test, before it makes a decision. It can also accept the application as submitted, adjust the premium or sum assured, or decline it.
Approval
If the details are satisfactory, the insurer approves the policy and issues it digitally after the premium payment. These plans may offer slightly lower coverage or higher premiums since no medical test is conducted.
Term Life Insurance plans without medical tests may have limits, such as a lower sum assured, but they suit some buyers well.
Senior Citizens: Plans without a medical test are limited at higher ages, and where offered, the sum assured is usually lower. Most insurers will ask for a medical test or a tele-medical interview, so declare your health history accurately from the start.
Young Adults: If you are in your 20s or 30s and healthy, you can get cover quickly without a medical test.
People in Good Health: If you have no health conditions to declare, you can skip the extra time that medical underwriting takes.
Busy Professionals: If your schedule is tight, a plan with no medical exam saves you the trip to a lab or a home visit.
Senior Citizens: Plans without a medical test are limited at higher ages, and where offered, the sum assured is usually lower. Most insurers will ask for a medical test or a tele-medical interview, so declare your health history accurately from the start.
Assess Your Coverage Needs: Start with your income, your loans and what your family spends in a year. Your sum assured should cover those costs for as long as they would depend on you.
Compare Plans: Check the premium, the sum assured limits and the claim settlement record across insurers. Also check each insurer’s no-medical limits, since they differ from one company to the next.
Be Transparent: Declare your health history, tobacco and alcohol use, and family medical history in full. An incorrect answer is what puts a claim at risk later.
Understand Policy Terms: Read the exclusions, the free look period and the grace period for premium payment before you pay. Note any extra conditions that apply to no-medical plans.
Add Riders for Enhanced Cover: Riders such as critical illness or waiver of premium widen your protection for an added premium. Choose only the ones that match your needs.
Here is a list of pointers that you should keep in mind to avoid any inconsistency with the insurance company in the future:
Transparency About Your Medical Condition: Your health is a key factor in how the insurer assesses risk over the policy term. If you have a pre-existing illness or a serious medical condition, the risk of death is higher, and the insurer prices the policy on that basis. If you do not declare the condition, it can create problems when your nominee files a claim.
Example: A buyer takes a term plan without a medical test and does not disclose an existing heart condition. If the policyholder dies of a heart-related cause within the first three years, the insurer can investigate the claim. If it establishes that a material fact was concealed, it may reject the nominee’s claim. Whether the concealment is treated as a misstatement or as fraud depends on whether it was deliberate.
Transparency About Your Lifestyle: Lifestyle habits affect your health risk. A smoker, for example, faces a higher risk of cancer and heart disease, and insurers price tobacco use separately. If you do not disclose smoking or heavy drinking, the insurer can reject the claim or cancel the policy.
Disclose all medical conditions and lifestyle habits accurately. It is the surest way to protect your family’s claim.
Yes, if the application was inaccurate. Buying term insurance without a medical test does not weaken your claim in itself. An insurer can reject a claim for non-disclosure only when it proves that you hid or misstated a material health fact, and Section 45 of the Insurance Act, 1938 limits how long it has to do so.
Within the First 3 Years: The insurer may challenge the policy if you failed to disclose a material health or lifestyle fact, such as diabetes, a heart condition or tobacco use. It must communicate its grounds in writing to you or your nominee. The three-year period runs from the date of issue, commencement of risk, revival of the policy or addition of a rider, whichever is latest.
After 3 Years: The policy cannot be called into question on any ground. A claim therefore cannot be repudiated for misstatement or non-disclosure once this period has ended.
Genuine Errors: An inaccurate answer cannot be treated as fraud if you can show it was true to the best of your knowledge, or that there was no intention to conceal the fact. Where an insurer cancels a policy for misstatement rather than fraud, it must refund the premiums paid within 90 days.
Answer every health and lifestyle question in full, even if a condition seems minor.
Declare smoking and alcohol use accurately.
Keep a copy of your application and any call recordings or emails from the insurer.
While buying a term insurance policy, many individuals are confused between the choice of a term insurance plan with a medical test and a term insurance plan without a medical test. Fortunately, both types of plans are now available in the market, and the decision depends on your health condition and the need for the policy.
The following table provides the differences between the two plans in simple terms.
| Features | Term Insurance With Medical Tests | Term Insurance Without Medical Tests |
| Application Process | The application process is relatively simpler since it requires basic medical examinations or health screenings for you to be assessed by the insurance company before the issuance of the policy. | The insurer will use the health information provided in your application to assess your condition, eliminating the need for medical tests. |
| Approval Time | The approval may take a little longer since the insurer will need to assess your medical reports to evaluate your health profile. | Approval is usually quicker since the policy is issued without waiting for medical reports or test results. |
| Premium Cost | If the medical reports show that you are healthy, you may qualify for lower premiums because the insurer can assess the risk more accurately. | Premiums may be slightly higher since the insurer is offering coverage without detailed medical verification. |
| Eligibility Criteria | Eligibility depends more closely on your medical history and current health condition, which can influence both approval and premium rates. | The eligibility criteria are generally simpler, which can make it easier for many applicants to obtain coverage. |
| Coverage Amount | The policies with medical tests may provide options for higher sum assured amounts since the insurer knows your risk level well. | The policies may provide options for relatively lower sum assured amounts in order to balance the high level of uncertainty in assessing risk. |
| Who It Is Suitable For | This option is most suitable for individuals who are comfortable with medical tests and want extensive coverage at a premium depending on their health status. | This option may be suitable for individuals who want to apply quickly or do not want to undergo medical tests while seeking basic financial protection. |
Term insurance seekers can buy a term plan without a medical test. However, the cover on offer depends on your age, health declaration and family medical history. If you decide to buy one, be transparent about your medical situation and lifestyle so the claim is not rejected later.
Compare term plans without medical tests on premium and sum assured before you buy, and be ready to take a medical test if you need a higher cover. Disclosing your health conditions honestly keeps your premium accurate and protects your family’s claim.
If yes, Please rate us.

˜The insurers/plans mentioned are arranged in order of highest to lowest Sum Assured(SA) offered by Policybazaar’s insurer partners offering term insurance plans on our platform, as per ‘first year premium of life insurers as at 31.03.2025 report’ published by IRDAI.
Policybazaar Insurance Brokers Private Limited does not endorse, rate or recommend any particular insurer or insurance product offered by any insurer. For complete list of insurers in India refer to the IRDAI website www.irdai.gov.in
+On the basis of your profile
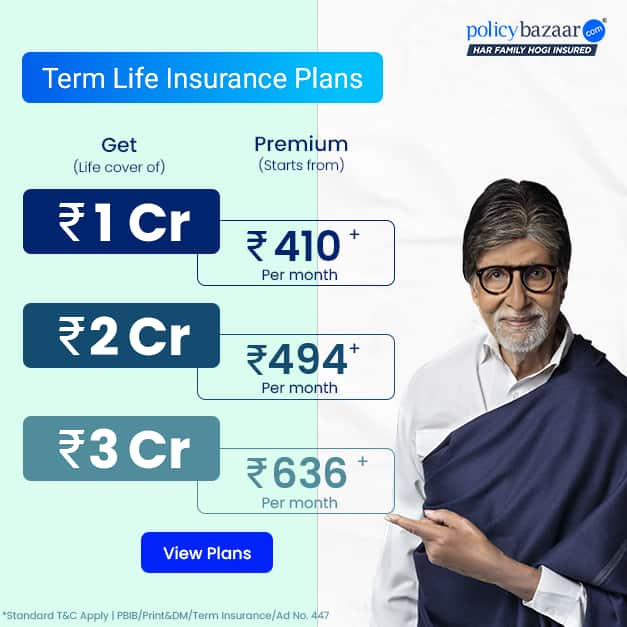
+Rs. 410/month is starting price for a 1 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age, rounded off to nearest 10
+Rs. 410/month (Rs.14/day) is starting price for a 1 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age rounded off to nearest 10
+Rs. 245 is starting price for a 50 lakhs term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 8/day is starting price for a 50 lakhs term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age, rounded off to nearest 10
+Rs. 15/day is starting price for a 75 lakhs term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age, rounded off to nearest 10
+Rs. 504/month is starting price for a 1.5 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 494/month is starting price for a 2 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 636/month is starting price for a 3 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 918/month is starting price for a 5 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 1,286/month is starting price for a 7 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 453/month is starting price for a 1 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs.582/month is starting price for a 2 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 786/month is starting price for a 3 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 1,374/month is starting price for a 5 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 1,592/month is starting price for a 7 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 525/month is the starting price for a 1 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 68 years of age.
+Rs. 668/month is starting price for a 2 crore term life insurance for an 25 year-old male, non-smoker, with no pre-existing diseases, cover upto 45 years of age.
+Rs. 1,200/month is starting price for a 2 crore term life insurance for an 35 year-old male, non-smoker, with no pre-existing diseases, cover upto 55 years of age.
+Rs. 410/month is starting price for a 1 crore term life insurance for an 18 year-old Female, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 577/month is starting price for a 1 crore term life insurance for an 18 year-old Male, self employed, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
*The full refund of premium is available on availing the one-time option of refund of premium. Total premium paid for policy (paid for add-ons) will be the special exit value, payable on availing the one-time option of refund of premium if you wish to completely exit the policy.
+Rs. ₹361/month is the starting price for a ₹1 crore loan cover with an 8% interest rate for an 18-year-old male, non-smoker, with no pre-existing diseases, loan tenure up to 20 years, rounded off to the nearest 10
Prices offered by the insurer are as per the approved insurance plans | #All savings and online discounts are provided by insurers as per IRDAI approved insurance plans | Standard Terms and Conditions Apply | **Tax Benefits are subject to changes in tax laws.| Policybazaar Insurance Brokers Private Limited
We will respond in the first instance within 30 minutes of the customers contacting us. 30-minute claim support service is for the purpose of giving reasonable assistance to the policyholder in pursuance of the claim. Settlement of claim (including cashless claim) is the responsibility of the insurer as per policy terms and conditions. The 30-minute claim support is subject to our operations not being impacted by a system failure or force majeure event or for reasons beyond our control. For further details, 24x7 Claims Support Helpline can be reached out at 1800-258-5881
For more details on risk factors, terms and conditions, please read the sales brochure carefully before concluding a sale
Policybazaar Insurance Brokers Private Limited | CIN: U74999HR2014PTC053454 | Registered Office - Plot No.119, Sector - 44, Gurgaon, Haryana – 122001 | Registration No. 742, Valid till 09/06/2027, License category- Composite Broker Visitors are hereby informed that their information submitted on the website may be shared with insurers. Product information is authentic and solely based on the information received from the insurers.
© Copyright 2008-2026 policybazaar.com. All Rights Reserved
˜ Policybazaar Promise reflects the guarantee offered by insurers. Price assurance is based on certifications shared by insurers with us.
ABSLI Life Shield Plan Premium starts
Read more
ABSLI Life Shield Plan Premium starts
Read more
ABSLI Life Shield Plan Premium starts
Read more
ABSLI Life Shield Plan Premium starts
Read more
ABSLI Life Shield Plan Premium starts
Read moreInsurance
Calculators
Payment Methods


Secured With

Follow us on


