









Download the Policybazaar app
to manage all your insurance needs.
Backdating a life insurance policy means changing the start date of the life insurance policy to a time earlier than the original date of buying the life insurance plan. Let’s say you purchased a plan on 1st January, 2011, but you later realized that if you had bought the policy two months earlier, you could have gotten it at lower premium rates. Backdating allows you to do so. This helps decrease the premium liability for the life assured during the policy term.


Backdating a life insurance policy means setting the policy’s official start date to a date earlier than the date the policy was purchased or issued. The back date life insurance policy is issued at a later date but premium and other policy calculations are based on the earlier date.
In simpler terms, backdating in life insurance policy means changing the start date of the policy to an earlier one. For example, you bought a life insurance policy on 1st June 2013 but later you think that the policy would have generated better returns if you had bought it in April 2013. You and your insurance company agree to change the policy to officially start it from April 2013. In this case, you have backdated the policy.
The process of backdating a life insurance is completely legal and does not put the policyholder in any trouble.

Term Plans
There are rules and conditions that you need to know if you are backdating a life insurance policy. They may vary between insurers, so it’s important to check the policy wording before choosing this option.
Restricted Backdating Window: Backdating is normally only permitted within a limited period by insurers. The exact limit can vary from insurer to insurer and policy to policy.
Premium Payment: The policyholder might have to pay the premium in one lump sum for the period of backdating. There are also a few insurers who might charge interest on this amount.
Waiver of Interest: In some cases, the interest may be waived if the policy is only to be backdated one month. It depends on what the insurer allows.
Lower Premium: If backdating the policy date results in a younger age for the policyholder, the policyholder can benefit from a lower premium.
Shorter Policy Duration: The backdated period falls within the policy term. So if a policy is backdated by two months, then the remaining period of coverage is reduced by two months.
Types of Policies Eligible for Backdating: Backdating can be done on some traditional life insurance policies such as endowment and money-back policies. The availability of the term insurance and ULIP’s depends on the insurer and the policy condition.
Rules Vary by Insurer: Not all insurers allow backdating. Charges and eligibility may differ between insurers and the allowed period.
Documents You May Need: Depending on the insurer, you may need to provide additional details or paperwork to get your backdate request approved.
Secure Your Family Future Today
₹1 CRORE
Term Plan Starting @
Get an online discount of upto 15%#
Compare 40+ plans from 15 Insurers
A lower premium is one of the main reasons for backdating a life insurance policy. If the backdated date puts you in a younger age bracket, the premium may be lower. This can be useful for people who are close to an age at which insurers increase their premium rates.
You can backdate your cover to an earlier date, even if the policy is issued later. So if something happens that you didn’t expect after the backdated date, but before the policy is actually issued, you may still be covered, depending on the terms and conditions of the policy.
The backdating can also be used for tax advantages. This is good for people who want to save taxes but their premium payment date is after the tax filling date. They may choose to backdate the policy and then they will have to pay a lump sum amount. Paying the accrued premium will enable the person to tap into the power of Section 80C to reduce their taxable income.
There may also be a personal reason for choosing an earlier policy date. Some people may want their policy to start on a date that is important to them. Backdating may also be used where the insurer permits it to bring the maturity date in line with a significant date.
Backdating the start date means the policy is considered to have started earlier. In savings-oriented plans, this can mean that the maturity or survival benefits are reached earlier as well.
You should avoid backdating in the following situations:
If you are young: Backdating is not very useful for applicants falling in the age group of 20-25 years because there is no major change in premium. It should be opted by people who are buying life insurance at an older age. As insurers levy high premium rates on applicants above 40-year, backdating allows them to make some savings.
If you have a Shortage of Funds: To backdate the insurance policy, you need to pay the premium of the backdated period along with the interest charges. However, you should exercise this option only if you have sufficient funds.
If you have Term Insurance: Backdating a term policy is a futile exercise because the coverage for the previous backdated period becomes irrelevant.
Backdating will help the applicant get reduced premiums as he falls into an earlier age category. But keep in mind the following things while considering the idea of a back date life insurance policy:
Saving through age factor:u Backdating a life insurance policy may suit the applicants who are approaching the age of 40 or 45 where insurers tend to raise the premium rates.
Types of policies: Backdating life insurance policy suits endowment and money back policies where the survival benefits commence earlier. However, in term insurance, the backdating period does not cover any insurance period.
Extra premiums: The insurer may charge extra premium amounts for the backdated period, thus, decreasing the overall premium saving.
Cost comparison: Before backdating life insurance policy, it should be ensured that the total premium savings are more than the amount charged for backdating.
Backdating works differently in term insurance compared with endowment or money-back plans.
In an endowment or money-back plan, the earlier start date can mean that survival or maturity benefits accumulate earlier. But in term insurance, there is no maturity benefit simply because the policy was backdated. The main thing to consider is the coverage period.
For example, a term insurance policy is having a backdated of 2 months. Now, since this is part of the policy term itself, it will get a shorter coverage period in future.
So, you may get a lower premium because you are younger, but you will also have to pay for the backdated period. The premium saving has to be balanced against what extra premium will be paid and how much the period of cover will be reduced.
Backdating a life insurance policy can be useful when the premium savings are higher than the amount paid for the backdated period. Before choosing it, check the premium you will have to pay for the earlier period, any interest charged by the insurer and how the backdated date will affect your policy tenure.
It is also important to check the type of policy. Backdating may work differently for term insurance, endowment and money-back plans and may not normally be available for ULIPs. Since the rules can vary between insurers, check the applicable conditions before deciding whether you should backdate your life insurance policy.
If yes, Please rate us.

˜The insurers/plans mentioned are arranged in order of highest to lowest Sum Assured(SA) offered by Policybazaar’s insurer partners offering term insurance plans on our platform, as per ‘first year premium of life insurers as at 31.03.2025 report’ published by IRDAI.
Policybazaar Insurance Brokers Private Limited does not endorse, rate or recommend any particular insurer or insurance product offered by any insurer. For complete list of insurers in India refer to the IRDAI website www.irdai.gov.in
+On the basis of your profile
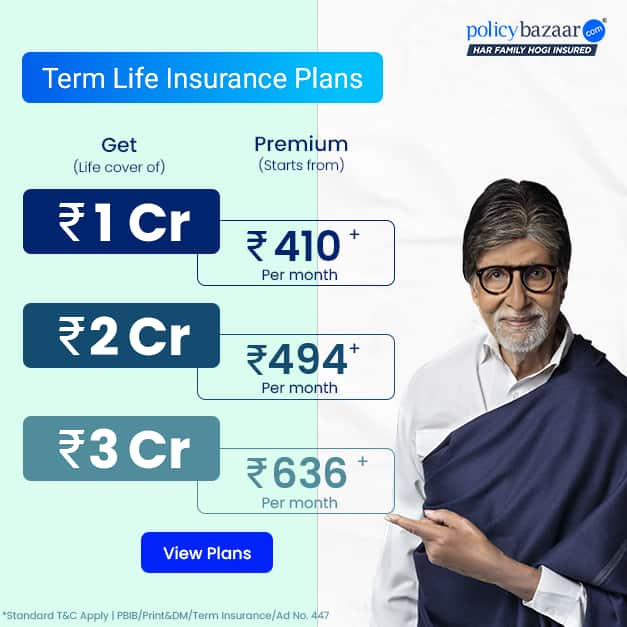
+Rs. 410/month is starting price for a 1 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age, rounded off to nearest 10
+Rs. 410/month (Rs.14/day) is starting price for a 1 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age rounded off to nearest 10
+Rs. 245 is starting price for a 50 lakhs term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 8/day is starting price for a 50 lakhs term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age, rounded off to nearest 10
+Rs. 15/day is starting price for a 75 lakhs term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age, rounded off to nearest 10
+Rs. 504/month is starting price for a 1.5 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 494/month is starting price for a 2 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 636/month is starting price for a 3 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 918/month is starting price for a 5 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 1,286/month is starting price for a 7 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 453/month is starting price for a 1 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs.582/month is starting price for a 2 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 786/month is starting price for a 3 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 1,374/month is starting price for a 5 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 1,592/month is starting price for a 7 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 525/month is the starting price for a 1 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 68 years of age.
+Rs. 668/month is starting price for a 2 crore term life insurance for an 25 year-old male, non-smoker, with no pre-existing diseases, cover upto 45 years of age.
+Rs. 1,200/month is starting price for a 2 crore term life insurance for an 35 year-old male, non-smoker, with no pre-existing diseases, cover upto 55 years of age.
+Rs. 410/month is starting price for a 1 crore term life insurance for an 18 year-old Female, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 577/month is starting price for a 1 crore term life insurance for an 18 year-old Male, self employed, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
*The full refund of premium is available on availing the one-time option of refund of premium. Total premium paid for policy (paid for add-ons) will be the special exit value, payable on availing the one-time option of refund of premium if you wish to completely exit the policy.
+Rs. ₹361/month is the starting price for a ₹1 crore loan cover with an 8% interest rate for an 18-year-old male, non-smoker, with no pre-existing diseases, loan tenure up to 20 years, rounded off to the nearest 10
Prices offered by the insurer are as per the approved insurance plans | #All savings and online discounts are provided by insurers as per IRDAI approved insurance plans | Standard Terms and Conditions Apply | **Tax Benefits are subject to changes in tax laws.| Policybazaar Insurance Brokers Private Limited
We will respond in the first instance within 30 minutes of the customers contacting us. 30-minute claim support service is for the purpose of giving reasonable assistance to the policyholder in pursuance of the claim. Settlement of claim (including cashless claim) is the responsibility of the insurer as per policy terms and conditions. The 30-minute claim support is subject to our operations not being impacted by a system failure or force majeure event or for reasons beyond our control. For further details, 24x7 Claims Support Helpline can be reached out at 1800-258-5881
For more details on risk factors, terms and conditions, please read the sales brochure carefully before concluding a sale
Policybazaar Insurance Brokers Private Limited | CIN: U74999HR2014PTC053454 | Registered Office - Plot No.119, Sector - 44, Gurgaon, Haryana – 122001 | Registration No. 742, Valid till 09/06/2027, License category- Composite Broker Visitors are hereby informed that their information submitted on the website may be shared with insurers. Product information is authentic and solely based on the information received from the insurers.
© Copyright 2008-2026 policybazaar.com. All Rights Reserved
˜ Policybazaar Promise reflects the guarantee offered by insurers. Price assurance is based on certifications shared by insurers with us.

Life insurance fraud is a serious financial crime in India
Read more
High net worth individuals often opt for life insurance plans to
Read more
Yes, ICICI Life is one of the leading life insurance companies
Read more
“I recently bought an HDFC term plan and it is the best
Read more
The life insurance policy in India is a type of life insurance
Read moreInsurance
Calculators
Resources
Payment Methods


Secured With

Follow us on


