







Download the Policybazaar app
to manage all your insurance needs.
Joint life term insurance, also called a joint term plan for husband and wife, is a single term plan that covers two people, usually a married couple. If either partner dies during the term, the plan pays a death benefit to the nominee. Some plans keep the survivor covered afterwards, while others end after the first claim, so the payout structure matters more than the premium.


A joint term plan is most useful when both partners earn, because one death will not leave the other managing the household alone. In India, joint term insurance is usually offered as an option on an individual plan so you buy a term plan with a joint life option, and rules differ by insurer.

Term Plans
A joint life term policy is a type of term life insurance that provides coverage to two people, usually a husband and wife, under one plan. You can usually get it as a term plan with joint life option. Both are covered for a fixed term, and you pay the premium on the schedule you agreed to. If either of you dies during the term, the insurer pays the death benefit to the nominee, as per the policy terms.
What happens after that depends on the plan you pick. With some policies, cover ends once the first death claim is settled. With others, the surviving partner stays covered. Here’s how it generally works.
Pick the sum assured and the policy term
Decide together how much cover you want and for how long. The insurer will look at your ages, income, health and other eligibility factors before issuing the policy.
Pay the premium
You pay at whatever frequency you choose. In most plans, one premium covers both lives.
Claim the death benefit
If one of you dies during the term, the nominee files a claim with the insurer. The insurer then pays the sum assured according to the plan’s payout structure.
Check whether the survivor stays covered
Some policies terminate after the first claim. Others keep the surviving partner’s cover going, and a few also waive their future premiums.
Know what happens when the term ends
If the policy expires while you’re both alive, the cover simply stops. If the surviving spouse wants insurance later, they’ll probably have to buy a new term plan, and it could cost more because of age or health changes.
Let’s understand how Joint Life Insurance works with an example
Say Raj is 35 and buys a joint policy with his wife Seema, who is 30. Raj has ₹2 crore of cover and Seema has ₹50 lakh, running until Raj turns 75. The policy also has a premium waiver for Seema.
If Raj dies first, or is diagnosed with a covered terminal illness: his nominee gets ₹2 crore, subject to the policy conditions. Seema stops paying premiums and her ₹50 lakh cover stays active. If she dies or is diagnosed with a covered terminal illness later in the term, her nominee receives ₹50 lakh.
If Seema goes first: her nominee gets ₹50 lakh, subject to the policy terms. Raj’s ₹2 crore cover continues, and his nominee receives it if he dies or is diagnosed with a covered terminal illness during the remaining term.
If both of them die, or both are diagnosed with a covered terminal illness: each nominee receives the respective amount, ₹2 crore for Raj and ₹50 lakh for Seema, subject to the claim conditions.
In this setup, each partner has their own cover amount, and the survivor stays protected after the first claim. Not every plan works this way. Terminal illness provisions and premium waiver conditions differ between insurers, so read the policy wording before you buy.
Joint cover in India comes in three main structures. Knowing which one a plan uses is the most important step in comparing them.
First-to-die: The policy covers two people and pays the sum assured when the first of them dies. The cover then ends, so the survivor is left without it.
Second-to-die: The sum assured is paid only after both partners have died, to the beneficiaries named in the policy. Some insurers offer this as an option on their joint term plans. It is mainly used in estate planning, not to replace income.
Joint life or spouse cover: Under term insurance for a spouse, one partner holds the main policy and the spouse is added as a secondary life. A term plan with joint life option usually works this way. The details vary by plan. Some plans cover the spouse from the start, with a smaller amount at first that rises after the primary life dies. Others start the spouse's cover only after the primary insured dies.
Secure Your Family Future Today
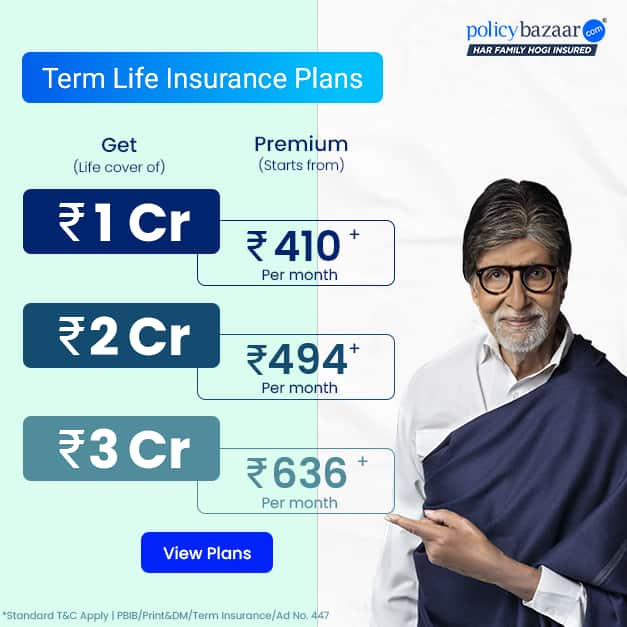
₹1 CRORE
Term Plan Starting @
Get an online discount of upto 15%#
Compare 40+ plans from 15 Insurers
Adding a spouse to a plan can cost relatively little. Some insurers say that covering a spouse in the same plan costs less than buying two individual plans. The savings depend on the plan, your ages, and the cover each partner takes.
The premium for a joint term plan depends on both partners' ages, health, smoking status, and occupation, as well as the sum assured and the policy term. Because the insurer prices both lives, a large age gap or a health condition in one partner can raise the cost. Adding riders also increases the premium.
Note: It is suggested that the term plan premium be calculated using the term insurance calculator online tool by Policybazaar before buying the plan.
Mostly, yes. The joint and spouse options that insurers offer are built for spouses, and some joint life covers are available only for your spouse. Some insurers describe eligibility more broadly, in terms of insurable interest: the death of one person must cause the other a financial loss. That can extend to relationships such as parent and child. Confirm the insurer's rules before you apply. Term insurance pays a death benefit. It does not cover medical expenses.
Note: Know what is term insurance first and then buy a term plan for your loved ones.
A joint life term plan covers both spouses under one policy, so you don’t need to buy two separate ones. What you actually get depends on the insurer, but these plans often come with lower premiums, a choice of payout styles, a premium waiver and some extra support for whoever is left behind.
It usually costs less
Buying one policy for two people can work out cheaper than buying two. Don’t assume a fixed saving, though. The final premium depends on the insurer, the cover amount, and the age and health of both of you.
You can choose how the money is paid out
Insurers handle this differently. Some pay the full sum assured once, when the first spouse dies, and then the policy ends. Others pay out separately for each spouse. Check this before you sign, because it decides whether the surviving partner is still covered after the first claim.
Monthly income instead of a lump sum
Some plans let the nominee take the death benefit as regular monthly income rather than one big amount. A few spread it over 120 instalments, for example. This can make day-to-day household budgeting easier after a loss.
Premium waiver benefit
With some policies, once one spouse passes away the remaining premiums are waived, and the survivor stays covered without paying anything more. In some plans this is built in, and in others it’s an add-on. The conditions vary, so read the fine print.
Support for the family
The payout can cover monthly bills, clear a home loan or other debts, and pay for your children’s education. This matters most when both of you earn, since losing one income can put real pressure on the household.
Extra protection with riders
Many plans let you add a critical illness rider, an accidental death rider or a permanent disability rider. Keep in mind that not every rider applies to both partners. Features like return of premium, increasing cover and top-ups are sometimes limited to the primary insured only.
Tax benefits
Under the Income Tax Act, 2025, eligible premiums can qualify for a deduction under Section 123 (earlier 80C), up to ₹1.5 lakh overall. Premiums on health-related riders may fall under Section 126 (earlier 80D), within the prescribed limits. The death benefit may also be tax-exempt under Section 11. All of this is subject to conditions, and the deductions generally apply only under the old tax regime.
Easier policy management
One policy means one set of documents, one premium date and one renewal to remember. It’s a small thing, but it keeps your insurance details in one place.
Note: Check out the best term insurance plan in India and choose one that suits your requirements.
| Factors | Joint term insurance | Two separate term plans |
| Premium | One premium covers both partners, which can cost less than two separate premiums depending on the insurer and cover. | Two premiums, each based on one person’s age, health and habits |
| Payout | Depends on the plan: a lump sum on one death after which the policy ends, a lump sum with cover continuing for the survivor, or a lump sum plus regular payments | Each policy pays its own sum assured, and the other policy continues |
| If both partners die | Some joint plans pay only one death benefit, while others pay a separate amount for each partner | Each policy pays its own benefit to its nominee |
| Riders | Available, with the rider premium charged on top of the base plan | Each partner chooses their own riders |
| Managing the policy | One policy, and either partner can pay the premium | Two policies, with two premium schedules to track |
| Separation or divorce | The policy may need to be converted into a single policy, and if one partner stops paying, the other carries the cost | No effect on the other policy |
| Age gap and lifestyle | Works best when partners are close in age and have a similar lifestyle | Works better when ages differ widely or one partner smokes |
A joint plan is suitable for:
Couples who share financial commitments such as a home loan or children's education costs.
Households where both partners earn and want a single policy to manage.
Couples where one partner does not earn and the other wants to bring them under cover.
Partners of similar age and health, who may get better rates because the insurer prices both lives together.
Shared income risk. When both partners' incomes support the household, the loss of either one hurts. A payout can cover loan repayments and living costs in the first years afterwards.
Children's plans. The payout can keep education and other long-term goals on track.
Simpler administration. One policy and one premium schedule are easier to track than two.
Estate planning. A second-to-die plan pays only after both partners have died, so it suits families focused on passing wealth to heirs rather than replacing income
A joint term plan can work well for couples who want one policy to manage and are comfortable with the plan's limits. It is not the right choice for everyone, because spouse cover, riders and payouts often come with conditions.
Before you decide, get quotes for a joint plan and for two individual policies with the same cover, then compare the total premium, the spouse's cover amount and the conditions attached.
Note: You should also check the benefits of term life insurance if you are planning to purchase the term insurance plan.
If yes, Please rate us.

˜The insurers/plans mentioned are arranged in order of highest to lowest Sum Assured(SA) offered by Policybazaar’s insurer partners offering term insurance plans on our platform, as per ‘first year premium of life insurers as at 31.03.2025 report’ published by IRDAI.
Policybazaar Insurance Brokers Private Limited does not endorse, rate or recommend any particular insurer or insurance product offered by any insurer. For complete list of insurers in India refer to the IRDAI website www.irdai.gov.in
+On the basis of your profile
+Rs. 410/month is starting price for a 1 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age, rounded off to nearest 10
+Rs. 410/month (Rs.14/day) is starting price for a 1 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age rounded off to nearest 10
+Rs. 245 is starting price for a 50 lakhs term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 8/day is starting price for a 50 lakhs term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age, rounded off to nearest 10
+Rs. 15/day is starting price for a 75 lakhs term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age, rounded off to nearest 10
+Rs. 504/month is starting price for a 1.5 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 494/month is starting price for a 2 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 636/month is starting price for a 3 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 918/month is starting price for a 5 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 1,286/month is starting price for a 7 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 453/month is starting price for a 1 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs.582/month is starting price for a 2 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 786/month is starting price for a 3 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 1,374/month is starting price for a 5 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 1,592/month is starting price for a 7 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 525/month is the starting price for a 1 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 68 years of age.
+Rs. 668/month is starting price for a 2 crore term life insurance for an 25 year-old male, non-smoker, with no pre-existing diseases, cover upto 45 years of age.
+Rs. 1,200/month is starting price for a 2 crore term life insurance for an 35 year-old male, non-smoker, with no pre-existing diseases, cover upto 55 years of age.
+Rs. 410/month is starting price for a 1 crore term life insurance for an 18 year-old Female, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 577/month is starting price for a 1 crore term life insurance for an 18 year-old Male, self employed, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
*The full refund of premium is available on availing the one-time option of refund of premium. Total premium paid for policy (paid for add-ons) will be the special exit value, payable on availing the one-time option of refund of premium if you wish to completely exit the policy.
+Rs. ₹361/month is the starting price for a ₹1 crore loan cover with an 8% interest rate for an 18-year-old male, non-smoker, with no pre-existing diseases, loan tenure up to 20 years, rounded off to the nearest 10
Prices offered by the insurer are as per the approved insurance plans | #All savings and online discounts are provided by insurers as per IRDAI approved insurance plans | Standard Terms and Conditions Apply | **Tax Benefits are subject to changes in tax laws.| Policybazaar Insurance Brokers Private Limited
We will respond in the first instance within 30 minutes of the customers contacting us. 30-minute claim support service is for the purpose of giving reasonable assistance to the policyholder in pursuance of the claim. Settlement of claim (including cashless claim) is the responsibility of the insurer as per policy terms and conditions. The 30-minute claim support is subject to our operations not being impacted by a system failure or force majeure event or for reasons beyond our control. For further details, 24x7 Claims Support Helpline can be reached out at 1800-258-5881
For more details on risk factors, terms and conditions, please read the sales brochure carefully before concluding a sale
Policybazaar Insurance Brokers Private Limited | CIN: U74999HR2014PTC053454 | Registered Office - Plot No.119, Sector - 44, Gurgaon, Haryana – 122001 | Registration No. 742, Valid till 09/06/2027, License category- Composite Broker Visitors are hereby informed that their information submitted on the website may be shared with insurers. Product information is authentic and solely based on the information received from the insurers.
© Copyright 2008-2026 policybazaar.com. All Rights Reserved
˜ Policybazaar Promise reflects the guarantee offered by insurers. Price assurance is based on certifications shared by insurers with us.
ABSLI Life Shield Plan Premium starts
Read more
ABSLI Life Shield Plan Premium starts
Read more
ABSLI Life Shield Plan Premium starts
Read more
ABSLI Life Shield Plan Premium starts
Read more
ABSLI Life Shield Plan Premium starts
Read moreInsurance
Calculators
Resources
Payment Methods


Secured With

Follow us on


