





Download the Policybazaar app
to manage all your insurance needs.
According to Policybazaar's own "How India Buys Insurance 2.0" report, based on behaviour data from over 50 million customers across 60+ insurers, 47.6% of Indians still don't know what term insurance actually is, despite it being one of the most affordable ways to secure a large life cover.
 4.8++74,425 Reviews


However, awareness alone doesn't mean the ones who do buy are choosing well. With several policies offering similar benefits, premiums, and riders, finding the best term insurance plan in India can be confusing.
In this article, we've compared the top term insurance plans in India across claim settlement ratio, sum assured range, and what actually sets each one apart, so you can pick the plan that delivers when your family needs it most.

Term Plans
There is no single term insurance plan that is best for everyone. The right choice depends on your age, income, financial responsibilities, coverage requirements, and long-term goals.
The best term insurance plan in India provides high claim reliability, multiple customisation options, and comes with several unique features. Choosing the best term insurance plan for your family is a crucial decision. Medical costs are going up. Money responsibilities are growing. Daily life also feels more risky than before. A term insurance plan provides financial security to your family in case something unfortunate happens to you.
If you are a young professional, newly married, parent, homeowner, NRI or self-employed / business owner, this article will help you to compare the best term insurance plans in India in 2026 and choose the right cover for your family.
To find the best term insurance plan for your situation -
whether you're a woman looking for lower premium rates,
an NRI comparing plans that work from abroad, or
an HNI who needs a higher sum assured
you don't have to figure it out alone.
And if you're confused about which plan will actually suit your financial needs and budget, it's a good idea to first compare plans from multiple insurers before deciding.
6 core parameters that decide the best plan for you:
Claim reliability: We look at each insurer's claim settlement ratio (CSR) over multiple years, not just the latest one, since a single strong year doesn't guarantee consistent performance. A one-off good number means less than a track record.
Product features: We go through the actual policy wording to check what's genuinely included — is terminal illness cover built in or an add-on? Can you defer a premium if you're short on cash one year? Are the riders comprehensive or bare-minimum?
Policy term: How long the cover actually needs to last — ideally until your dependants are no longer financially reliant on your income, not just whatever the lowest-premium option happens to offer.
Flexibility: How much you can actually customise — premium payment terms, payout structure (lump sum, income, or a mix), and options to increase cover at life stages like marriage or a child's birth.
Pricing: We compare premiums for the same age, gender, sum assured, and smoking status across insurers, so the comparison is apples-to-apples rather than misleading.
Sum assured range and entry age: Whether the plan can actually accommodate your required cover amount and is available at your age, since not every plan suits every profile.
Comparing on the online portal gives you this side by side in minutes. Calling an insurance advisor gets you the same parameters, but walks you through against your specific profile — whether that means finding a woman-friendly premium discount, an NRI-compliant payment and claims process, or a high enough sum assured for an HNI's needs.
Either way, the "best" plan isn't simply the one with the lowest premium. It's the one that holds up well across all of these factors for your specific profile.
Secure Your Family Future Today
₹1 CRORE
Term Plan Starting @
Get an online discount of upto 15%#
Compare 40+ plans from 15 Insurers
The following are the 5 best term insurance plans in India based on their annualised premiums for the FY 2024-25.
| Top 5 Term Insurance Companies in India | Best Term Insurance Plans | Sum Assured | CSR (Claim Settlement Ratio) | What Makes it Different? |
| Life Insurance Corporation of India | LIC Jeevan Amar | 25 Lacs - No Limit | 98.74% | Government-backed insurer, which still matters a lot to conservative buyers
Choice between level cover and increasing cover Joint-life option available for spouses |
| SBI Life Insurance Co. Ltd. | SBI Smart Shield Plus | 25 Lacs - No limit | 98.56% | Backed by India's largest bank, smoother process for existing SBI customers
Lower premiums for women Return-of-premium variant available for those who want maturity payouts |
| HDFC Life Insurance Co. Ltd. | HDFC Click 2 Protect Supreme Plus | 10,000 - No limit | 99.72% | Life-stage benefit auto-increases cover at milestones like marriage or a new child, no fresh medicals needed
4 payout combinations to choose from (lump sum, monthly income, or mixed) |
| ICICI Prudential Life Insurance Co. Ltd. | ICICI iProtect Smart Plus | 50 Lacs - 20 Crores | 99.34% | Single rider bundles critical illness, accidental death, and disability, instead of buying each separately
Sum assured up to 20 crore, which suits high-net-worth buyers Mid-term payment mode switching allowed |
| Axis Max Life Insurance Ltd. | Axis Max Smart Term Plan Plus | 25 Lacs – 20 Crores | 99.80% | Special exit value option if you discontinue after a set period
Wide sum assured range |
** Disclaimer: The insurers mentioned above are ranked from highest to lowest annualised premium based on data from IRDAI Annual Report 2024–25. Policybazaar does not recommend, rate or endorse any specific insurer or insurance product. You can check the complete list of life insurers in India on the IRDAI website.
The following are the 5 best term insurance plans in India based on their annualised premiums for the FY 2024-25.
| Top 5 Term Insurance Companies in India | Best 5 Term Insurance Plans | Sum Assured | CSR (Claim Settlement Ratio) | What Makes it Different? |
| Life Insurance Corporation of India | LIC Jeevan Amar | 25 Lacs - No Limit | 98.74% | Government-backed insurer, which still matters a lot to conservative buyers
Choice between level cover and increasing cover Joint-life option available for spouses |
| SBI Life Insurance Co. Ltd. | SBI Smart Shield Plus | 25 Lacs - No limit | 98.56% | Backed by India's largest bank, smoother process for existing SBI customers
Lower premiums for women Return-of-premium variant available for those who want maturity payouts |
| HDFC Life Insurance Co. Ltd. | HDFC Click 2 Protect Supreme Plus | 10,000 - No limit | 99.72% | Life-stage benefit auto-increases cover at milestones like marriage or a new child, no fresh medicals needed
4 payout combinations to choose from (lump sum, monthly income, or mixed) |
| ICICI Prudential Life Insurance Co. Ltd. | ICICI iProtect Smart Plus | 50 Lacs - 20 Crores | 99.34% | Single rider bundles critical illness, accidental death, and disability, instead of buying each separately
Sum assured up to 20 crore, which suits high-net-worth buyers Mid-term payment mode switching allowed |
| Axis Max Life Insurance Ltd. | Axis Max Smart Term Plan Plus | 25 Lacs – 20 Crores | 99.80% | Special exit value option if you discontinue after a set period
Wide sum assured range |
** Disclaimer: The insurers mentioned above are ranked from highest to lowest annualised premium based on data from IRDAI Annual Report 2024–25. Policybazaar does not recommend, rate or endorse any specific insurer or insurance product. You can check the complete list of life insurers in India on the IRDAI website.
Assess your family’s needs:
Before picking a term plan, you should first figure out what all will be your family's major financial needs in the future. When you are no longer there, your income will also cease. Therefore, if your family depends on your income, consider everyday expenses, debts, education, and long term objectives. Now accordingly choose a life cover that can help your loved ones maintain financial stability even in your absence.
Check your outstanding loans:
Your cover should take into account any outstanding liabilities you may have such as a home loan, car loan or personal loan. A term plan is designed to make sure these loans do not turn into a liability for your family. So, when you are deciding about your sum assured, think of the outstanding loan amount.
Compare term insurance premium:
Compare premiums from different insurance companies using the same age, life cover, and the policy term. This helps make a right comparison and pick the best term insurance plan based on both benefits and cost.
Select suitable riders:
Riders like critical illness, accidental death or waiver of premium shall strengthen your base policy. However, add only those that fit your health and lifestyle because the premium amount increases after adding a rider.
Check the insurer's claim settlement ratio:
The claim settlement ratio (CSR) indicates how many claims an insurance company has settled. While comparing term plans, look for insurance companies with a consistent track record of strong CSR over consecutive years.
Read customer reviews
Feedback from current policyholders can tell you a lot about an insurer's claim experience, customer service and overall reliability – information that doesn't always show up in a brochure. It’s worth taking a few minutes to do this before you make your final decision.
Buying term life insurance at a young age can help you get a high life cover at low premiums.
If you don’t have too many financial responsibilities yet, you can choose a long policy term, such as up to 60 or 65 years of age.
A term insurance plan with 1 crore or more can be chosen based on your future needs and income.
You can also add some important term insurance riders as your financial needs increase,
Financial responsibilities often increase after marriage that makes term insurance for spouse a smart way to protect your partner from financial difficulties.
Take combined expenses, EMIs, future goals, and existing liabilities into consideration when choosing the life cover.
You can also check whether the insurance company offers spouse coverage or joint-life coverage.
Parents need to consider their children's education, daily expenses and their dreams and future goals when choosing term insurance for parents.
A higher life cover can help replace lost income and support your children's needs.
Always look for a policy term that provides protection until your children become financially independent.
Self-employed people may have different income flows and financial responsibilities when compared to salaried employees.
Insurance companies may ask documents like ITR, business financial records to check eligibility.
At the time of choosing a term plan for self-employed, consider the expenses of your family along with business loans, and other financial liabilities.
NRIs can buy term insurance in India to provide financial protection to their families.
Applicants may have to go for the online or video medical exam, depending on the rules of the insurance company and the country of residence of the applicant.
Before selecting the right term insurance plan for NRI,you need to compare the plans available, eligibility criteria, premium rates and policy benefits.
Term insurance for senior citizens is generally more expensive because premiums increase with age.
The choice of plans and coverage may also be more limited.
If you are buying term insurance at an older age, then it is worth considering your outstanding loans, dependent family members and financial needs before selecting the policy term and sum assured.
A term insurance premium calculator lets you compare quotes from HDFC Life, LIC, SBI Life, ICICI Prudential, Axis Max Life, Tata AIA, and other insurers side by side, without filling out a full application for each one. You enter your basic details once You enter your basic details onc like age, gender, sum assured, policy term, and smoking status — and the calculator shows you an estimated premium for each insurer instantly.
Keep every input identical across insurers. Use the same age, same sum assured (say, ₹1 crore), same policy term (say, until age 65), and same smoking status each time you switch insurers on the calculator. Comparing a 20-year term from one insurer against a 30-year term from another isn't a real comparison — the premiums will look different for reasons that have nothing to do with which plan is actually better value.
Add the same riders, or none at all, across every quote. A quote with a critical illness rider added will always look more expensive than a bare base plan. If you want to compare rider costs specifically, do that as a separate step rather than mixing it into your base premium comparison.
Consider the number as an estimate, not a locked-in price. The calculator gives you an indicative premium based on the details you enter. Your final premium can change once the insurer reviews your actual medical history, income proof, and any additional underwriting requirements.
Use it to narrow down, not to decide outright. A premium calculator is great for shortlisting 3–4 insurers with similar pricing. From there, compare claim settlement ratio, features, and riders (covered earlier on this page) before making your final choice — the cheapest quote isn't automatically the best plan.
You can use Policybazaar's term insurance premium calculator to run this comparison across 40+ insurers in one place, using the exact same inputs each time.
Following mentioned are the factors that should be considered before buying the best term insurance plan:
Buying a term plan early can help you get a lower premium.
Calculate your income, loans and other future financial commitments and then decide how much cover you need.
Your medical history, smoking and lifestyle may affect your premium and eligibility.
Select a sum assured that adequately caters to your family’s financial needs, but don’t overpay.
Select a policy term that will run for the years your family will require your income.
Research plans that have flexible features and benefits as you need.
Various plans now include medical-linked features such as term insurance with OPD care or critical illness benefits that can help cover treatment-related expenses.
Compare and choose the right term insurance policy from the list of all term insurance policies in India for 2026. These plans offer different life cover options for different annual incomes. Find the most affordable, high-coverage plan that fits your financial needs.
| Private Insurer | Term Insurance Plan | UIN | Entry Age | Sum Assured |
| HDFC Life Insurance | HDFC Life Click 2 Protect Supreme Plus | 101N189V03 | 18 - 65 years | 10,000 Lacs - No Limit |
| ICICI Prudential Life Insurance | ICICI Pru iProtect Smart Plus | 105N205V04 | 18 - 65 years | 25 Lacs – 20 Crores |
| Tata AIA Life Insurance | Tata AIA Sampoorna Raksha Promise | 110N176V11 | 18 - 65 years | 25 Lacs – No limit |
| SBI Life Insurance | SBI Life Smart Shield Plus | 111N150V01 | 18 - 65 years | 25 Lacs – No limit |
| Bajaj Life Insurance | Bajaj Life eTouch II | 116N198V09 | 18 - 65 years | 50 Lacs – No limit |
| Axis Max Life Insurance | Axis Max Smart Term Plan Plus | 104N132V01 | 18 - 60 years | 25 Lacs – 20 Crores |
| Go Digit Life Insurance | Digit Glow Plus Term Insurance | 165N007V03 | 18 - 65 years | 25 Lacs – 1 Crore |
| Aditya Birla Sun Life Insurance | ABSLI Super Term Plan | 109N153V02 | 18 - 65 years | 25 Lacs – No limit |
| India First Life Insurance | India first Life Plan | 143N007V03 | 18 - 60 years | 1 Lac - 50 Crores |
| Kotak Mahindra Life Insurance | Kotak e-Term Insurance | 107N129V04 | 18 - 65 years | 51 Lacs - No limit |
| Canara HSBC Life Insurance | Canara HSBC Promise2Secure | 136N099V01 | 18 - 60 years | 25 Lacs – No limit |
| Shriram Life Insurance | Shriram Life Online Term Plan | 128N072V01 | 18 - 55 years | 25 Lacs - 10 Crores |
| PNB Met Life Insurance | PNB Mera Term Plan Plus | 117N126V04 | 18 - 60 years | 25 Lacs - No limit |
| Star Union Dai-ichi Life Insurance | SUD Life Assured Term Plan | 142N102V02 | 18 - 50 years | 25 Lacs - No Limit |
| Pramerica Life Insurance | Pramerica Life Saral Jeevan Bima | 140N073V01 | 18 - 65 years | 5 Lacs - 25 Lacs |
| Aviva Life Insurance | Signature 3D Term Plan - Platinum | 122N153V02 | 18 - 65 years | 30 Lacs - 5 Crores |
| Generali Central Life Insurance | Generali Central Care Plus Plan | 133N030V06 | 18 - 60 years | 10 Lacs - No limit |
| Indusind Nippon Life Insurance | INL Super Suraksha Plus | 121N149V02 | 18 - 60 years | 2 Crore - No limit |
| Ageas Federal Life Insurance | Termsurance Life Protection Insurance Plan | 135N040V03 | 18 - 60 years | 5 Lacs - No limit |
| Bandhan Life Insurance | Bandhan Life iTerm Prime | 138N084V03 | 18 - 65 years | - |
| Bharti Axa Life Insurance | Bharti AXA Flexi Term Pro | 130N103V03 | 18 - 65 years | 25 Lacs - No limit |
| Edelweiss Life Insurance | Edelweiss Life Zindagi Protect Plus | 147N080V01 | 18 - 65 years | 50 Lacs – No limit |
| Public Insurer | ||||
| Life Insurance Corporation of India Ltd. | LIC New Jeevan Amar | 512N350V02 | 18 - 65 years | 25 Lacs - No Limit |
Disclaimer: ~The insurers/plans mentioned are arranged in order of highest to lowest Sum Assured(SA) offered by Policybazaar’s insurer partners offering term insurance plans on our platform, as per ‘first year premium of life insurers as at 31.03.2025 report’ published by IRDAI. Policybazaar does not endorse, rate or recommend any particular insurer or insurance product offered by any insurer. For complete list of insurers in India refer to the IRDAI website www.irdai.gov.in
Note: The above table shows the list of term insurance plans for 1 crore life cover for the profile of an 18-year-old, non-smoking male, cover upto 38 years.
Planning to buy best term insurance? Learn what is term insurance, how it works, and who should consider buying it before comparing plans.
Early Exit Value: Get back the total premiums paid on eligible long-term policies.
Cover Continuance: Defer premiums for up to 12 months while keeping the cover active.
Health Management Services: Built in access to health and wellness services with the plan.
Special Discounts: The plan offers special discounts on premiums for women policyholders and on choosing a higher sum assured.
Single Premium Option: The plan allows you to pay the entire premium at once.
Multiple Plan Options: Select which option of protection is best for your finances.
3D Family Plus: Combines a lump-sum payout with monthly income that increases by 8% every year.
3D Accelerated: Pays 50% of the base cover, up to ₹1 crore, on terminal illness diagnosis.
MWP Act Option: Allows eligible policyholders to take the policy under the Married Women’s Property Act.
Special Exit Value: Eligible policyholders can get their premiums back after the specified policy period.
Lifeline Plus: On the death of a spouse, female policyholders are allowed to raise their cover.
Maternity Cover: Cover for some pregnancy complications and congenital anomalies in newborns. This cover is optional.
Special Exit Value: Get back premiums paid when you no longer need the cover. However, it is applicable only for eligible applicants.
Exit at Later Life Stage: The benefit can be availed around age 55 but it is subject to eligibility conditions.
Pay Till 60: One of the premium payment modes of this plan lets you pay premiums until age 60.
Premium Holiday: You can stop paying premiums for 1, 2 or 3 policy years and still keep your life cover.
Early Exit Value: Premiums are paid back as per the policy conditions to the eligible policyholders who choose to exit early.
Auto Cover Continuance: Defer premiums for up to 12 months but the cover will remain active.
Joint Life Cover: Cover your spouse with you in the same policy.
Quit Smoking Benefit: Policyholders with smoking habits are eligible for a 5% premium reduction if they quit smoking.
Stay Fit Benefit: Policyholders with appropriate BMI-related underwriting extras are eligible for premium reduction after improving their health.
Premium Rate Lock: Block your premium rate at purchase while allowing cover to increase later.
Child Care Benefit: Additional cover can continue until the child reaches 21 years.
Special Exit Value: Get premiums back on eligible early exit from the plan.
Better Half Benefit: Extend protection to your spouse under the same plan.
Child’s Future Protect Benefit: Add a dedicated sum assured for your child’s future.
Top-up Benefit: Increase the base sum assured through the plan’s top-up option.
Claim Service Guarantee: The plan has a claim service guarantee of 2 working days.
Extra Life Cover: Offers an extra accidental death benefit on top of the base life cover.
Flexible Payout Option - Select from lump sum, fixed monthly income or a combination and receive the death benefit.
Wellness Benefits: The plan includes wellness benefits for the life assured.
Inbuilt Additional Protection: Accidental death, accidental total and permanent disability and terminal illness benefits are built into the product structure.
Coverage Up to 85: The plan allows a maturity age of up to 85 years following product conditions.
Life Goal Option: The death benefit can vary by policy year based on the chosen level cover period and amortisation rate.
Spouse Cover: After the life assured’s death, the spouse can receive a separate cover for the remaining policy term.
Waiver on Critical Illness & Disability: Future premiums shall be waived off if you are diagnosed with a covered critical illness or total and permanent disability.
12-Month Premium Break: Defer premiums for up to 12 months without blocking your cover.
₹3 Lakh Instant Payout: Receiving an instant payout up to ₹3 lakhs within one working day shall be possible.
60 Critical Illnesses: The plan lists 60 critical illnesses. These are under the optional critical illness protection.
Cover Till 80: Lifelong cover up to age 80.
Installment Death Benefit: Death benefit shall be paid in installments if the policyholder wants.
Large Life Cover: The plan is designed to provide high life cover at affordable premiums.
Step-Up Option: Add additional life cover at certain life milestones.
Three Plan Options: It's your choice to select from the three protection options.
Three Payout Options: Select how the death benefit is paid to the nominee.
Enhanced Cover Sum Assured: Choose a cover which will grow by 10% annually from the 6th year to the 15th year of the policy. However, it will not exceed two times the base cover.
Special Rates for Women: Women policyholders are offered reduced premium rates.
Instalment Payout: The death benefit can be received in instalments, rather than only as a lump sum.
Child Education Support: Add a benefit for your child’s education.
Life Stage Benefit: Boost protection at certain life stages.
Whole Life Cover: Continue to protect up to 99 years of age (under certain options).
Simple Cover Structure: Designed as a standardised Saral Jeevan Bima protection plan.
Policy Term Up to 40 Years: Coverage period (5 – 40 years).
Single, Limited or Regular Pay: Select from single pay, limited pay (5 or 10 years regularly) or regular pay throughout the entire policy term.
Return of Premium: The Life Plus variant returns premiums paid if you survive the policy term.
Milestone Cover Increase: Increase the life cover at milestones such as marriage or having children.
Flexible Death Payout: Choose a lump sum, income or a combination of both.
Future Proofing Benefit: Choose a specific option designed to increase protection as your financial responsibilities grow.
Better Half Benefit: Add protection for your spouse under the plan.
Whole Life Cover: Eligible customers can continue life cover up to age 100.
Inbuilt Terminal Illness Cover: Terminal illness protection is built into all base options.
Inbuilt Disability Premium Waiver: Future premiums are waived after accidental total and permanent disability.
50:50 Payout Option: Combination of payout mode as you shall receive 50% of the cover as lump sum and the remaining 50% as monthly income.
Long Term Protection: Cover shall continue until the age of 80.
High Cover: You get a sum assured of up to ₹2 crore.
Multiple Premium Payment Structures: Choose from single, limited period or regular premium payment term options.
FlexiPay: This option lets you pause premiums for up to 12 months without losing your cover
Instant Claim Payout: Get an instant ₹3 lakh payout the moment a claim is intimated, while the rest of the claim is processed
Terminal Illness payout: Diagnosed with a terminal illness? You're paid 50% of your sum assured right away
Term insurance provides you pure life cover at a low price for a certain period of time. Other life insurance plans combine risk coverage with savings or investment which gives you a higher payout or maturity benefit but at a very high premium. Below are the key difference of term insurance vs other life insurance plans
| Parameter | Term Insurance | Other Life Insurance Plans |
| Core Purpose | Term insurance focuses solely on replacing income and protecting your family if you die during the policy term. | Other plans (like endowment, whole life, or ULIPs) aim to build a financial corpus or savings alongside providing insurance coverage. |
| Premium | Lower, as it covers only the risk of death | Higher, as it includes savings or investment components |
| Maturity Benefit | None, unless a Return of Premium (TROP) variant is chosen | Payout provided on surviving the policy term |
| Sum Assured | Typically higher for the same premium | Comparatively lower for the same premium |
| Investment Component | Not applicable | Present, as bonuses, fund value, or guaranteed returns |
Term Plans are more affordable than the other types of Life Insurance starting at ₹14/day, and makes it easier to secure your family’s future while also supporting long-term goals like FIRE (Financial Independence, Retire Early).
0% GST on individual life insurance premiums from September 2025
Coverage up to 100 years is available with select term insurance plans
Fixed premiums throughout the policy term, unless you choose to increase your cover
Tax benefits up to 46,800 may be available under Section 80C for premiums and Section 10(10D) for death benefits, subject to applicable conditions
NRIs can buy term insurance in India, with some insurers offering video or tele-medical examinations without requiring a visit to India
To buy a good term insurance plan, you should go with Policybazaar for the following reasons:
Easily Compare Term Insurance Plans
You can see all the plans side-by-side in one place, and actually find out which one gives you the best coverage for your budget.
Clear, Simple Information
The coverage amount, premium and add-ons are all clearly laid out so you know what you are paying for before you commit. None of the fine print is unexpected.
An Easy Buying Experience
Skip the paperwork. Most of the journey — from choosing a plan to completing your purchase — happens online, so you're not stuck filling out forms or visiting a branch.
Easy Access to Your Policy
Once you have purchased your term insurance policy, you can access your details at any time – no need to dig through old emails or retrieve documents.
Advisor Support When You Want It
Confused which plan suits you? Give us a call and an advisor will help you select best term insurance plan as per your needs.
Claims Support for Your Family
And when it matters most, our team can help your family navigate the claims process — clearly, and without the usual confusion.
A Trusted Place to Purchase Term Insurance
A no-nonsense, trustworthy place to compare and buy the best term insurance plan - built to make the process easier, not harder.
Every financial plan needs risk protection in place before wealth creation. And that’s where term insurance begins. If you’re in your 30s and 40s with loans to pay, children to educate and parents to care for, having enough life cover provides you the solid base from which the rest of your financial plan such as investments, savings, long-term goals can easily operate uninterrupted if something were to happen to the breadwinner.
For your Dependants: The more people you support on one income, the more coverage you need. According to a Swiss Re report referred to in a PIB backgrounder, the penetration of life insurance is only 2.7% of GDP and a large chunk of Indian families are still uninsured and still have not planned for this risk.
For homemakers: A homemaker’s contribution like childcare and household management holds a real financial value. If those duties had to be outsourced it would cost a lot. Term cover for homemakers is to cover the dependents, which are often ignored.
For debt protection: A long-term loan such as a ₹50 lakh home loan is a commitment that lasts for decades. Term insurance will ensure that your family does not have to deal with your debt if you die.
Tax Benefit: Premiums paid can be claimed for deduction up to ₹1.5 lakh under Section 123 (Schedule XV) of the Income Tax Act, 2025, the new version of the popular Section 80C, available only in the Old Tax Regime. Section 126 may also qualify for health riders (up to Rs 1 lakh, subject to limits). The death benefit itself is fully exempt from tax under section 11 (schedule II) – the new replacement of section 10(10D).
For the primary earning member of a family, term insurance is one of the smarter financial decisions you can make — but choosing the best plan matters just as much as buying one. The right plan offers adequate life cover, a policy term that lasts as long as your responsibilities do, and an insurer with a strong claim settlement record. Get these three right, and you've secured your family's long-term financial future.
If yes, Please rate us.

˜The insurers/plans mentioned are arranged in order of highest to lowest Sum Assured(SA) offered by Policybazaar’s insurer partners offering term insurance plans on our platform, as per ‘first year premium of life insurers as at 31.03.2025 report’ published by IRDAI.
Policybazaar does not endorse, rate or recommend any particular insurer or insurance product offered by any insurer. For complete list of insurers in India refer to the IRDAI website www.irdai.gov.in
+On the basis of your profile
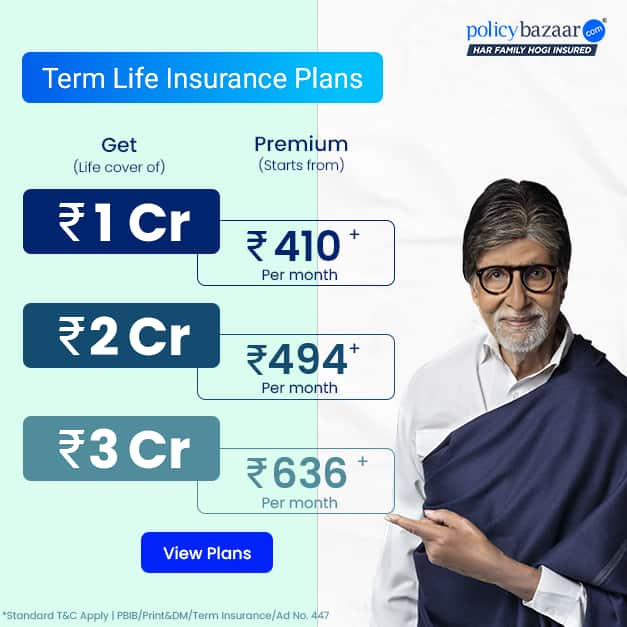
+Rs. 410/month is starting price for a 1 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age, rounded off to nearest 10
+Rs. 410/month (Rs.14/day) is starting price for a 1 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age rounded off to nearest 10
+Rs. 245 is starting price for a 50 lakhs term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 8/day is starting price for a 50 lakhs term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age, rounded off to nearest 10
+Rs. 15/day is starting price for a 75 lakhs term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age, rounded off to nearest 10
+Rs. 504/month is starting price for a 1.5 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 494/month is starting price for a 2 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 636/month is starting price for a 3 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 918/month is starting price for a 5 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 1,286/month is starting price for a 7 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 453/month is starting price for a 1 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs.582/month is starting price for a 2 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 786/month is starting price for a 3 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 1,374/month is starting price for a 5 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 1,592/month is starting price for a 7 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 525/month is the starting price for a 1 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 68 years of age.
+Rs. 668/month is starting price for a 2 crore term life insurance for an 25 year-old male, non-smoker, with no pre-existing diseases, cover upto 45 years of age.
+Rs. 1,200/month is starting price for a 2 crore term life insurance for an 35 year-old male, non-smoker, with no pre-existing diseases, cover upto 55 years of age.
+Rs. 410/month is starting price for a 1 crore term life insurance for an 18 year-old Female, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 577/month is starting price for a 1 crore term life insurance for an 18 year-old Male, self employed, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
*The full refund of premium is available on availing the one-time option of refund of premium. Total premium paid for policy (paid for add-ons) will be the special exit value, payable on availing the one-time option of refund of premium if you wish to completely exit the policy.
+Rs. ₹361/month is the starting price for a ₹1 crore loan cover with an 8% interest rate for an 18-year-old male, non-smoker, with no pre-existing diseases, loan tenure up to 20 years, rounded off to the nearest 10
Prices offered by the insurer are as per the approved insurance plans | #All savings and online discounts are provided by insurers as per IRDAI approved insurance plans | Standard Terms and Conditions Apply | **Tax Benefits are subject to changes in tax laws.| Policybazaar Insurance Brokers Private Limited
We will respond in the first instance within 30 minutes of the customers contacting us. 30-minute claim support service is for the purpose of giving reasonable assistance to the policyholder in pursuance of the claim. Settlement of claim (including cashless claim) is the responsibility of the insurer as per policy terms and conditions. The 30-minute claim support is subject to our operations not being impacted by a system failure or force majeure event or for reasons beyond our control. For further details, 24x7 Claims Support Helpline can be reached out at 1800-258-5881
For more details on risk factors, terms and conditions, please read the sales brochure carefully before concluding a sale
Policybazaar Insurance Brokers Private Limited | CIN: U74999HR2014PTC053454 | Registered Office - Plot No.119, Sector - 44, Gurgaon, Haryana – 122001 | Registration No. 742, Valid till 09/06/2027, License category- Composite Broker Visitors are hereby informed that their information submitted on the website may be shared with insurers. Product information is authentic and solely based on the information received from the insurers.
© Copyright 2008-2026 policybazaar.com. All Rights Reserved
˜ Policybazaar Promise reflects the guarantee offered by insurers. Price assurance is based on certifications shared by insurers with us.
HDFC Life Click 2 Protect Elite Pro is a pure term insurance
Read more
Kotak Protect Advantage is a Non-Participating, Non-Linked
Read more
Generali Central Saral Ashray Yojana is an individual pure risk
Read more
ICICI Pru iProtect Smart Her is a term insurance variant offered
Read more
Canara HSBC Life Insurance Promise2Secure is a non-linked
Read moreInsurance
Calculators
Payment Methods


Secured With

Follow us on


