








Download the Policybazaar app
to manage all your insurance needs.
Your life insurance policy allows you to borrow against it by taking a loan from your insurer, with the policy's accumulated cash value serving as collateral. Depending on your policy's surrender value, lenders approve a loan amount ranging from 50% to 90% of that value. It is a quick, low-hassle way to get money without surrendering your policy. Your life cover continues as usual. Let us understand how the loan against your life insurance policy works in the article below.


A loan against a life insurance policy is a secured loan that lets you borrow money against your policy's surrender value without losing your life cover. The size of the loan depends on the accumulated surrender value over time. However, traditional life insurance plans such as endowment, money-back or whole life policies that have completed the required lock-in period may be eligible for a loan.
One of the main advantages of this option is that the policy itself is security and therefore the interest rate is lower than on personal loans or credit cards. There is also very little paperwork involved as the lender doesn’t need to carry out extensive credit checks due to the low risk nature of these loans.

Term Plans
You can take a loan against eligible endowment or ULIP policies to meet different financial needs.
You can access the funds without surrendering your policy, so your life cover generally continues.
You have the flexibility of taking out a loan based on your insurance policy, such as an endowment or a ULIP policy, allowing you to make several withdrawals and pay interest only on the amount you use.
After the lock-in period has ended, borrowers of loans that were subject to the lock-in period may pay both the principal and the interest at that time.
The approved loan limits vary from small to large amounts in order to meet the different needs of the policyholders. The maximum loan amount may be up to 90% of the policy's surrender value. .
You have the option of paying off your loan at any time without having to pay any extra fees.
The process for applying for the loan involves very little paperwork and simply requires your basic identification, proof of address, your bank details, and your insurance policy documents.
Secure Your Family Future Today
₹1 CRORE
Term Plan Starting @
Get an online discount of upto 15%#
Compare 40+ plans from 15 Insurers
Follow the steps below to get a loan against life policy:
Step 1: Get in touch with your life insurance company to find out about policy loan options.
Step 2: Fill out the required forms and send in any requested documents.
Step 3: Find out about the loan terms, the interest rate, and the repayment process.
Step 4: Decide how much you want to borrow based on your policy's cash value
Step 5: Make sure to pay on time so that your policy's benefits or coverage don't change.
*Note: If you have any questions about your life insurance policy or the loan you took out against it, you can call the insurance advisor to get answers.
When you borrow money against your life insurance policy, the insurance company or the lender will use the surrender value of the policy as security. Policies that build a cash or surrender value, such as eligible ULIPs and endowment plans, may qualify for a loan. After approval you will get the money without having to cash in the policy, and the policy will remain in force.
If you are not able to repay the loan, the amount you owe will be taken out of your claim or your maturity payment.
You can borrow from permanent life insurance policies that build cash value, like Whole Life and Universal Life, as well as Endowment and Money-Back plans. These loans use your own money, don't require a credit check, and stay active as long as the loan plus interest doesn't go over the cash value. If you don't pay them back, the death benefit will be less.
On the other hand, a loan against term insurance is usually not possible, as they do not accumulate cash or have a surrender/maturity value.
The life insurance plan should be approved by the lender.
This loan is available to individuals, companies, partnerships, sole proprietorship, and HUFs.
To get a loan against life insurance policy, you need to show these documents:
A passport sized photograph
A copy of your ID, like your Aadhaar Card, Passport, or Voter's ID
A copy of the PAN card
Insurance policy papers
A bank statement or a copy of a canceled check (as proof of a bank account)
More documents, as the insurance company asked for to confirm
There are several factors that one needs to bear in mind before opting for a loan against life policy:
Loan Amount
The loan amount under a loan against insurance policy depends on the policy’s surrender value. Usually, a percentage of this value is approved, after which the policy is assigned to the lender as security. The amount received is not treated as taxable income.
Interest Charged
Interest on a loan against life insurance policy is based on the premiums paid and the total number of premiums completed. Higher paid-up value often means a lower rate. Banks generally link the rate to their base lending rate.
Waiting Period
You cannot apply immediately after buying the policy. Most insurers require a waiting period of at least 3 years of premium payments before you can apply for a loan
Premiums
Even after taking a loan against life policy, you should continue paying premiums. If you stop paying the premiums, the insurer might terminate the policy, which can affect both the cover and the loan arrangement. You can use a term insurance calculator to see how much premiums you have to pay for your desired life cover.
Repayment of Loan
A loan against life policy should ideally be repaid within the policy term. You may repay both principal and interest, or only interest. If unpaid, the outstanding amount is deducted from the final claim payout.
Deed of Assignment
To process a policy loan insurance request, the policy must be formally assigned to the lender. This is done through an assignment deed, and the endorsement is recorded on the policy document.
Charges
Insurers or banks may levy nominal processing charges when approving a loan against insurance.
*Note: It is recommended that you first know what is term insurance and understand its features, benefits and exclusions before you buy term plan or get loan against life insurance policy.
The death benefit will be reduced by any loans that have not been paid off together with the interest, meaning that your family will receive an amount that is less than the original value of the policy.
There is a risk of the policy lapsing: if the amount of the loan plus the interest owed exceeds the cash value still available, the policy could lapse without your knowing and you would then be left without insurance coverage.
The cash value will grow more slowly since the fund is used as security for the loan and therefore part of your fund is tied up in the loan and so the amount it earns over time is reduced, as a result of which your future bonuses or dividends will be less than they would have been.
A loan against your life insurance policy makes sense when you need cash quickly and don't want to touch your savings or take an unsecured loan at a higher rate. It's fast, doesn't need a credit check, and your policy stays in your name throughout. That said, it isn't free money. Failure to make repayment will result in the outstanding loan and interest being adjusted against your claim or maturity amount and in some cases, the policy may even lapse if the loan amount exceeds the surrender value. So before you go ahead, weigh up how urgently you need the funds, against how it could affect your family's payout later. If you are confident of repaying it on time, it is a practical choice. Otherwise, it is worth looking at other options first.
Note: You should also check the benefits of term life insurance if you are planning to purchase the term insurance plan.
If yes, Please rate us.

˜The insurers/plans mentioned are arranged in order of highest to lowest Sum Assured(SA) offered by Policybazaar’s insurer partners offering term insurance plans on our platform, as per ‘first year premium of life insurers as at 31.03.2025 report’ published by IRDAI.
Policybazaar does not endorse, rate or recommend any particular insurer or insurance product offered by any insurer. For complete list of insurers in India refer to the IRDAI website www.irdai.gov.in
+On the basis of your profile
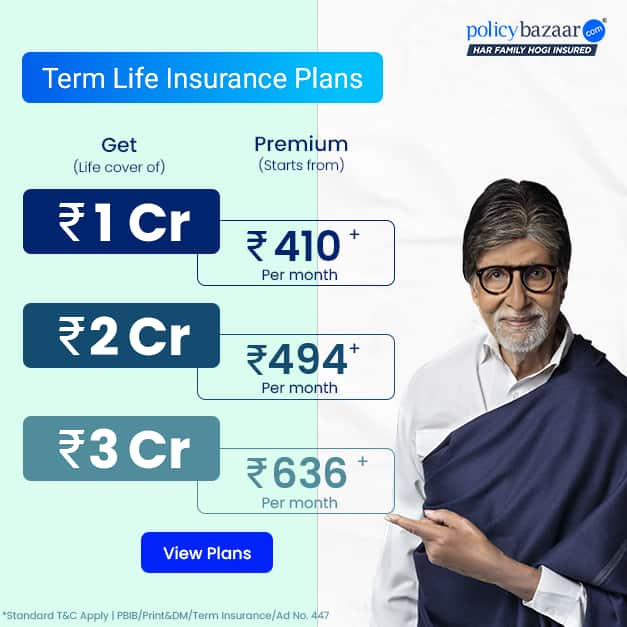
+Rs. 410/month is starting price for a 1 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age, rounded off to nearest 10
+Rs. 410/month (Rs.14/day) is starting price for a 1 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age rounded off to nearest 10
+Rs. 245 is starting price for a 50 lakhs term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 8/day is starting price for a 50 lakhs term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age, rounded off to nearest 10
+Rs. 15/day is starting price for a 75 lakhs term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age, rounded off to nearest 10
+Rs. 504/month is starting price for a 1.5 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 494/month is starting price for a 2 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 636/month is starting price for a 3 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 918/month is starting price for a 5 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 1,286/month is starting price for a 7 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 453/month is starting price for a 1 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs.582/month is starting price for a 2 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 786/month is starting price for a 3 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 1,374/month is starting price for a 5 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 1,592/month is starting price for a 7 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 525/month is the starting price for a 1 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 68 years of age.
+Rs. 668/month is starting price for a 2 crore term life insurance for an 25 year-old male, non-smoker, with no pre-existing diseases, cover upto 45 years of age.
+Rs. 1,200/month is starting price for a 2 crore term life insurance for an 35 year-old male, non-smoker, with no pre-existing diseases, cover upto 55 years of age.
+Rs. 410/month is starting price for a 1 crore term life insurance for an 18 year-old Female, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 577/month is starting price for a 1 crore term life insurance for an 18 year-old Male, self employed, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
*The full refund of premium is available on availing the one-time option of refund of premium. Total premium paid for policy (paid for add-ons) will be the special exit value, payable on availing the one-time option of refund of premium if you wish to completely exit the policy.
+Rs. ₹361/month is the starting price for a ₹1 crore loan cover with an 8% interest rate for an 18-year-old male, non-smoker, with no pre-existing diseases, loan tenure up to 20 years, rounded off to the nearest 10
Prices offered by the insurer are as per the approved insurance plans | #All savings and online discounts are provided by insurers as per IRDAI approved insurance plans | Standard Terms and Conditions Apply | **Tax Benefits are subject to changes in tax laws.| Policybazaar Insurance Brokers Private Limited
We will respond in the first instance within 30 minutes of the customers contacting us. 30-minute claim support service is for the purpose of giving reasonable assistance to the policyholder in pursuance of the claim. Settlement of claim (including cashless claim) is the responsibility of the insurer as per policy terms and conditions. The 30-minute claim support is subject to our operations not being impacted by a system failure or force majeure event or for reasons beyond our control. For further details, 24x7 Claims Support Helpline can be reached out at 1800-258-5881
For more details on risk factors, terms and conditions, please read the sales brochure carefully before concluding a sale
Policybazaar Insurance Brokers Private Limited | CIN: U74999HR2014PTC053454 | Registered Office - Plot No.119, Sector - 44, Gurgaon, Haryana – 122001 | Registration No. 742, Valid till 09/06/2027, License category- Composite Broker Visitors are hereby informed that their information submitted on the website may be shared with insurers. Product information is authentic and solely based on the information received from the insurers.
© Copyright 2008-2026 policybazaar.com. All Rights Reserved
˜ Policybazaar Promise reflects the guarantee offered by insurers. Price assurance is based on certifications shared by insurers with us.

Life insurance fraud is a serious financial crime in India
Read more
High net worth individuals often opt for life insurance plans to
Read more
Yes, ICICI Life is a highly reliable and top-rated life
Read more
“I recently bought an HDFC term plan and it is the best
Read more
The life insurance policy in India is a type of life insurance
Read moreInsurance
Calculators
Payment Methods


Secured With

Follow us on


