





Download the Policybazaar app
to manage all your insurance needs.
Term insurance with Return of Premium (TROP) is a term life insurance plan that refunds all premium amount paid (minus some charges) if the policyholder survives the policy term. If the policyholder passes away during the term, the plan still pays the full death benefit to the nominee.


This is specifically designed for those who want life cover but don’t want to lose their premium if nothing happens to them during the policy term. In exchange for this refund benefit, TROP plans generally charge a noticeably higher premium than the regular term plan.

Term Plans
Term insurance with return of premium is a life insurance plan that pays the full life cover to your nominee if you die during the policy term, and refunds all the premiums you have paid in case you outlive the policy term. It is a variant of a pure term insurance plan. By paying an additional premium, policyholders can take advantage of TROPs. You can choose the required life cover and policy term and then proceed to pay the premiums. This plan is suitable for:
Those who are looking to get their money back after surviving the policy term
Those who need life insurance to financially protect their families in case of their death.
Secure Your Family Future Today
₹1 CRORE
Term Plan Starting @
Get an online discount of upto 15%#
Compare 40+ plans from 15 Insurers
Below mentioned are the best term plan with return of premium:
˜The insurers/plans mentioned are arranged in order of highest to lowest Sum Assured(SA) offered by Policybazaar’s insurer partners offering term insurance plans on our platform, as per ‘first year premium of life insurers as at 31.03.2025 report’ published by IRDAI.Policybazaar does not endorse, rate or recommend any particular insurer or insurance product offered by any insurer. For complete list of insurers in India refer to the IRDAI website www.irdai.gov.in
You can use a term insurance calculator to check the estimate of the premiums you need to pay regularly for the desired life cover. You can also use the HLV Calculator to know the ideal life cover.
A standard term insurance plan allows you to pay premium regularly, and if you pass away during the policy term, your family gets the death benefit (sum assured). But if you survive the full policy term, you get nothing back in return.
Term insurance with Return of Premium works in a different way. It has two possible scenarios:
If you pass away during the policy term: Your nominee gets the full life cover, just like a regular term insurance plan.
If you survive the policy term: You get back all the premium amounts you paid (excluding taxes, rider charges and extra premiums charged due to health, occupation, or lifestyle factors) as a maturity benefit.
The refund is paid along with other benefits, such as interest and bonuses, as per the policy tenure. Once the amount has been processed, the TROP plan terminates and the benefits of this policy cease.
To calculate the premium amount, you can use a term insurance premium calculator which helps compare different plans based on duration, coverage, and premium cost.
Let’s understand this with the help of an example:
Mr. Sharma is a 25 year old male earning 9 LPA, planning to buy a term plan for himself. He is healthy, no smoking history, no health problems. He buys a TROP plan with a life cover of ₹1 crore. For a policy term of 35 years, the annual premium payable is ₹14,095.
Scenario 1: Death of Mr. Sharma in the policy term
In case of Mr. Sharma’s death in the policy term, his nominee will receive a death benefit of ₹1 crore, and the policy will terminate
Scenario 2: Survival of Mr. Sharma till the end of the policy term
If Mr. Sharma survives till the end of the period of the policy, he will receive the eligible premiums payable as a maturity benefit, as specified in the policy terms. GST, rider premiums and other charges are generally excluded from this refund.
There are several benefits of term insurance that an individual should take into consideration, and a term insurance with return of premium plan has all those benefits with an additional one, i.e. return of all premiums upon maturity of the plan. Let’s understand some of these benefits of the best term plan with return premium below:
Full Refund of Premium Benefit
Term Return of Premium (TROP) plans offer the added advantage of refunding all premiums paid if the policyholder survives the policy term. With various TROP plans, customers can receive their premiums back (minus nominal charges), which helps them ensure the financial protection of their loved ones, along with the benefit of receiving their premiums back on survival.
Protect Your Family Against Life's Uncertainties
Return of Premium term life insurance protects your family financially if something happens to you during the policy term, giving them the sum assured to cover expenses and secure their future. If you survive the term, you get back every premium you paid — so your family stays protected either way.
Helps Build Savings
The refund amount that is received from a TROP can serve as a savings or can be used as a policyholder’s retirement corpus. The lump sum payout may also be re-invested to take care of your family’s financial needs.
Death Benefit to Nominees
TROP plans provide lump sum payout to the designated beneficiaries of the policyholder upon their untimely death, also called the death benefit. This is the life cover amount chosen by the policyholder, and this amount makes sure that loved ones receive financial support and coverage as intended by the policy.
Increased protection through Riders
TROP plans allow the addition of term insurance riders such as critical illness cover, accidental death benefit, and waiver of premium. These riders enhance the return of premium term life insurance by providing customized and comprehensive protection against various uncertainties.
Choose Return Option
Term insurance with return of premium plans allows customers to choose the most suitable refund option, like receiving the maturity benefits in a lump sum, as monthly installments, or as a combination of both.
Assurance of No Wasted Premiums
Many customers wonder if, with regular term plans, if they outlive the policy, the premiums they paid would be wasted, as no benefit is payable on survival. In TROP plans, the plan provides cover during the policy term and upon outliving the policy, the premiums paid throughout the policy are returned at the end of the policy term.
Flexible Premium Payments
You can choose the most suitable premium payment mode and term in a term insurance with return of premium by selecting the monthly, quarterly, half-yearly, and yearly modes. You can also choose to pay the premiums in regular, limited, or single premiums.
Save Tax Every Year With Tax Benefits
Buying the best term insurance with return of premium makes an individual eligible for the tax benefit. You can get term insurance tax benefits as per the prevailing laws of the Income Tax Act, of 1961. The premium amount paid towards the term insurance plan can be claimed as a deduction under Section 80C, and the benefit payout is free of taxes under Section 10(10D), provided your annual premium does not exceed ₹5 lakh for policies issued on or after April 1, 2023.
Note: Section 80C deductions are not valid under the New Tax Regime.
Earlier, when GST on Term Insurance was allowed to be deducted, the refund amount received under a TROP policy was less than the total amount of premium paid. The reason was that the GST part of the premium was paid to the government and not refunded to the policyholder.
Let’s say
If you have paid ₹2 lakh as a premium over the policy tenure, that includes GST, you would only get back the base premium (after GST deduction) at the end of the policy term.
But now with the introduction of the recent GST Council Announcement, policyholders are now entitled to receive the entire premium amount paid when they surrender the TROP policy. This makes TROP plans more efficient. Simply put, you will enjoy both sum assured amount and a full refund of your payment (minus some charges, and tax), making those plan more convenient than before.
A term plan with return of premium provides the best way for individuals looking for protection and an investment return. Unlike standard term plans, return of premium term life insurance provides a lump sum amount of all premiums paid (minus other nominal charges) in case you survive the policy term. This option helps individuals who want peace of mind, along with the money-back option.
With the availability of a comprehensive range of insurance products, selecting the right one can be challenging for a policy buyer. Choosing plans based on factors like cost or policy duration might not be optimal. It's crucial to weigh the comprehensive benefits of a term plan with return of premium to ensure satisfaction with the decision.
There are three variants of term insurance that provide a return of premiums. Term insurance with return of premium plan, No Cost term insurance, and special exit benefits in regular term insurance. You can assess your needs and requirements, understand term insurance and find the best plan for yourself and your family.
A return of premium term life insurance, also known as TROP, is different from a term plan as it provides a survival benefit as a premium return in addition to the death benefit. Here is a list of all the features of the Term plan return of premium:
| Features of Term Insurance with Return of Premium (TROP) Plans | Details |
| Affordability | Term plan with return of premium may be slightly more expensive than a regular term plan. However, under the Term Plan with Return of Premium, the premiums paid are returned as maturity benefits. |
| Premium Payment Options | You can also choose the right premium payment option from:
|
| Guaranteed Premium Return | With a term plan with return of premium, the policyholders don’t have to panic about the return of their paid amount, as it is assured under the plan. This plan offers guaranteed returns on the total premium paid, excluding the extra premium amount paid for the riders and add-ons (if any). |
| Maturity Benefits as Refund Amount | In the best term insurance with return of premium, the refund of the premium amount is offered at maturity, if the life assured survives the policy term. This means that the life assured does not lose the premium amount paid over the years. |
| Surrender Value | If you want to discontinue the payments of premium or surrender the term plan after buying the term plan with return of premium (TROP), you will get a surrender amount. The surrender value of the TROP generally varies depending on the payment option.
|
| Paid-Up Option | If premium payments are discontinued after a minimum policy period, some plans offer a paid-up option. Under this, the policy continues with reduced benefits rather than lapsing entirely.
Insurers usually require a minimum number of years of premium payment before this option becomes available. |
When it comes to fulfilling financial commitments like buying the best term plan with return of premium (TROP), every individual may have different goals. Selecting this plan depends on age, income, lifestyle, and health conditions. Evaluating your financial situation based on these criteria is crucial for choosing the right plan. TROP Plans can be a good choice for people falling under these categories if you are planning to buy the best term insurance with return of premium.
Unmarried: If unmarried, you may have specific financial responsibilities for your parents, especially if they are aged. Hence, in the event of your unfortunate demise, how term insurance works is that it will provide a death benefit to secure them financially. And, if you outlive the policy, you will receive all your premiums paid during the policy term.
Married: If you’re married and your partner solely depends on your income source, term insurance with return of premium (TROP) may be the ideal solution for you. How term insurance works is that it provides financial support for your spouse against life’s uncertainties.
Married with Kids: If you are married and have children, it is your main responsibility to protect your children's future. TROP ensures that your loved ones and kids are financially protected in case of any eventualities in the future, thereby with term insurance, your children’s education and career are not hampered.
Senior Citizens and Retirees
A term plan with a money back feature is advantageous for senior citizens or those individuals who are planning for retirement.
NRIs
NRIs can buy TROP to support their loved ones in India. In addition to this, as per Double Taxation Avoidance Agreement (DTAA) of India, NRIs can claim a tax deduction in case of term plan maturity, with certain T&Cs.
Before buying a right return of premium plan you can use a Term Return of Premium Calculator to estimate your premiums and understand how the plan fits your financial goals.
A Term Return Of Premium Calculator is an online tool that helps you determine the maturity amount that you can receive based on the various options that you select. The Term Return Of Premium Calculator is simple to use and you just need to enter a few necessary details to use it, such as:
Gender
Tobacco Consumption
Age
Required Life Cover
Age Until Which You’re Covered
Below are some of the best term plan with return of premium riders available in India:
| Term Insurance Riders | Details |
| Critical Illness Rider | Covers certain illnesses such as heart attacks, stroke, cancer, certain cardiovascular surgeries, etc. The number of illnesses covered by different companies varies, and people should take note of the ones the rider covers before they opt for it |
| Waiver of Premium Rider | Waives future premium payments under specific conditions, like job loss due to disability or critical illness, in return of premium term life insurance |
| Accidental Death Benefit Rider | This rider is an optional addition to the base life insurance plan that policyholders can choose for increased coverage at affordable premiums |
| Accidental Total and Permanent Disability Rider | Provides financial protection for policyholders in case of a permanent disability caused by an accident during the policy term |
| Terminal Illness Rider | In this rider, the policyholder receives a part of their death benefit when they are alive, in case he/she is diagnosed with a terminal illness. |
Here is why you should buy the best term insurance with return of premium from Policybazaar:
Dedicated claim support for family FREE
Discounts up to 15% for buying online
100% calls recorded to ensure no mis-selling
Advisors available in your city
Refund at the click of a button
| Parameter | Pure Term Insurance Plan | Term Plan with Return of Premium (TROP) |
| Definition | A pure term insurance plan is the simplest form of life insurance. Its only purpose is to pay a death benefit to the nominee if the life insured dies during the policy term. It offers no survival or maturity benefit. | TROP is a variant of term insurance that offers a survival benefit. If the life insured outlives the policy term, the insurer refunds the base premiums paid. |
| Benefits | The only benefit is the death benefit paid to the nominee if the life insured dies during the term. | Offers both the death benefit if death occurs during the term and a refund of base premiums paid if the policyholder survives the full term. |
| Premium Cost | Since the insurer covers only mortality risk and there is no refund component, premiums are lower for the same sum assured. | Usually higher than the pure term insurance plans. |
| Best Suited For | Individuals who want to provide financial protection to their family should consider buying this plan. | Term insurance with return of premium is best suited for individuals who want to receive the premiums paid along with the benefit of insurance coverage. |
In order to find the right term insurance plan with return of premium, it is always important to check a few points. Following are some points that you should consider before choosing a term plan with return of premium:
Before buying TROP, always assess the coverage amount as per your requirements in case of your unforeseen death
Ensure that the premium you have to pay fits your budget so that you don’t skip any premium payments or compromise on other expenses.
Check if your insurance company's claim settlement ratio is high. High CSR indicates the fast settlement of claims.
Check for an insurance company that has a good solvency ratio.
Your TROP plan should provide yearly, half-yearly, quarterly, or monthly premium payment options.
Step 1: Visit the Term Insurance with Return of Premium Form
Step 2: Fill in the basic details like name, age, and contact number, and then click on ‘View Plans’.
Step 3: Answer the questions about chewing or smoking habits, annual income, type of occupation, and language.
Step 4: After submitting all the details, a list of all available term insurance plans will be displayed.
Step 5: Filter out the return of premium plans
Step 6: Choose the best term plan with return of premium that suits you and proceed to pay
Return of Premium V/s Zero Cost Term Plan: Which is better?
Both Return of Premium (ROP) and Zero Cost Term Plans serve individuals with different needs. In a term insurance with return of premium plan, you get all your premiums back at the end of the policy if you survive the term. In a Zero Cost Term Plan, you can exit the policy after a few years and get your premiums back, but coverage also ends there. If you're looking for guaranteed return of premiums, term plan with return of premium is better. If you want flexibility to exit early, a Zero Cost Term Plan may suit you more.
What is Refund of Long Term Insurance Premium?
Refund of Long-Term Insurance Premium is another name for a term plan with return of premium, and means you get back the total premiums you paid over the years if you outlive the policy term. This is available in plans like Return of Premium term life insurance, where survival benefits are offered along with life cover.
Is there a company that offers return of premium term life insurance?
Yes, many life insurance companies in India offer Return of Premium term life insurance. You can check and compare the best term insurance with return of premium plans across various insurers to find the one that suits your needs the best. These plans give you the dual benefit of life cover and a refund of premiums at the maturity of the policy.
Term insurance is one of the most preferred plans due to its affordability. However, the fact that regular term insurance plans do not provide maturity benefits may discourage customers from purchasing them. The term insurance with return of premium benefit allows customers to receive the entire premium paid at the end of the policy as a maturity benefit. Therefore, unlike regular term plans, TROP plans provide both death and maturity benefits within the same plan.
Term insurance with return-of-premium plans comes with tax benefits under the Income-tax Act, 1961. Premiums paid towards these plans are eligible for a deduction under Section 80C, up to ₹1.5 lakh per year. The payout you receive, whether it is the death benefit or the return of premium on survival, is usually tax-free under Section 10(10D).
However, this tax-free benefit is not available for policies issued on or after April 1, 2023, if your annual premium exceeds ₹ 5 lakh.
The premium rates for term insurance with return of premium plans are slightly higher than regular term plans. However, they return the entire premiums paid towards keeping the policy active at the end of the policy term on survival. Thus, in case of untimely death, your nominee will be financially secured, and in case you outlive the policy term, you will receive the premiums paid, which can help you take care of your post-retirement life.
While looking for term insurance with return of premium option, keep the following factors in mind:
Life cover should be enough to cover your family’s financial needs in your absence
The premium rates should be affordable enough to fit your budget
Buy term insurance with return of premium from an insurer with good Claim Settlement Ratio (over 95%)
Select the most suitable premium payment option (single, monthly, quarterly, bi-annually, or yearly)
The term insurance with return of premium plans are available under MWP (Married Women’s Property) Act. This ensures that only the wife or kids of the policyholder will be eligible to receive the death benefit in case of an eventuality. Not only that, on survival of the policy, the return of premiums can only be claimed by the wife and children.
If yes, Please rate us.

˜The insurers/plans mentioned are arranged in order of highest to lowest Sum Assured(SA) offered by Policybazaar’s insurer partners offering term insurance plans on our platform, as per ‘first year premium of life insurers as at 31.03.2025 report’ published by IRDAI.
Policybazaar does not endorse, rate or recommend any particular insurer or insurance product offered by any insurer. For complete list of insurers in India refer to the IRDAI website www.irdai.gov.in
+On the basis of your profile
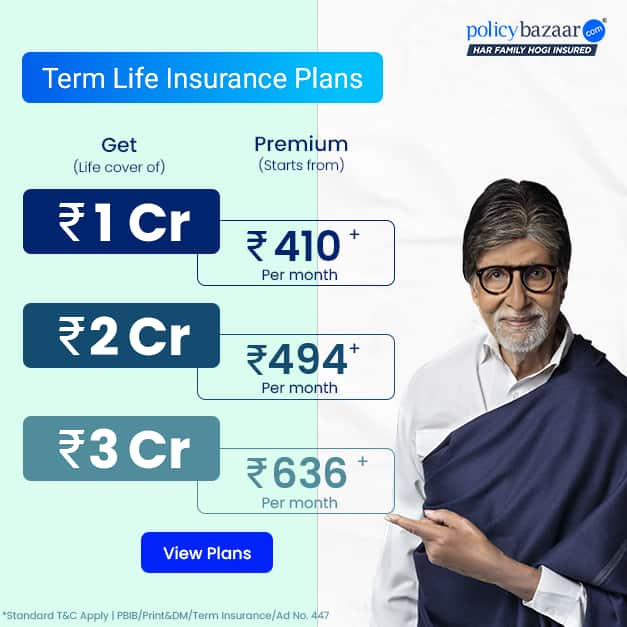
+Rs. 410/month is starting price for a 1 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age, rounded off to nearest 10
+Rs. 410/month (Rs.14/day) is starting price for a 1 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age rounded off to nearest 10
+Rs. 245 is starting price for a 50 lakhs term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 8/day is starting price for a 50 lakhs term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age, rounded off to nearest 10
+Rs. 15/day is starting price for a 75 lakhs term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age, rounded off to nearest 10
+Rs. 504/month is starting price for a 1.5 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 494/month is starting price for a 2 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 636/month is starting price for a 3 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 918/month is starting price for a 5 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 1,286/month is starting price for a 7 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 453/month is starting price for a 1 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs.582/month is starting price for a 2 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 786/month is starting price for a 3 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 1,374/month is starting price for a 5 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 1,592/month is starting price for a 7 crore term life insurance for an (NRI) 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 525/month is the starting price for a 1 crore term life insurance for an 18 year-old male, non-smoker, with no pre-existing diseases, cover upto 68 years of age.
+Rs. 668/month is starting price for a 2 crore term life insurance for an 25 year-old male, non-smoker, with no pre-existing diseases, cover upto 45 years of age.
+Rs. 1,200/month is starting price for a 2 crore term life insurance for an 35 year-old male, non-smoker, with no pre-existing diseases, cover upto 55 years of age.
+Rs. 410/month is starting price for a 1 crore term life insurance for an 18 year-old Female, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
+Rs. 577/month is starting price for a 1 crore term life insurance for an 18 year-old Male, self employed, non-smoker, with no pre-existing diseases, cover upto 30 years of age.
*The full refund of premium is available on availing the one-time option of refund of premium. Total premium paid for policy (paid for add-ons) will be the special exit value, payable on availing the one-time option of refund of premium if you wish to completely exit the policy.
+Rs. ₹361/month is the starting price for a ₹1 crore loan cover with an 8% interest rate for an 18-year-old male, non-smoker, with no pre-existing diseases, loan tenure up to 20 years, rounded off to the nearest 10
Prices offered by the insurer are as per the approved insurance plans | #All savings and online discounts are provided by insurers as per IRDAI approved insurance plans | Standard Terms and Conditions Apply | **Tax Benefits are subject to changes in tax laws.| Policybazaar Insurance Brokers Private Limited
We will respond in the first instance within 30 minutes of the customers contacting us. 30-minute claim support service is for the purpose of giving reasonable assistance to the policyholder in pursuance of the claim. Settlement of claim (including cashless claim) is the responsibility of the insurer as per policy terms and conditions. The 30-minute claim support is subject to our operations not being impacted by a system failure or force majeure event or for reasons beyond our control. For further details, 24x7 Claims Support Helpline can be reached out at 1800-258-5881
For more details on risk factors, terms and conditions, please read the sales brochure carefully before concluding a sale
Policybazaar Insurance Brokers Private Limited | CIN: U74999HR2014PTC053454 | Registered Office - Plot No.119, Sector - 44, Gurgaon, Haryana – 122001 | Registration No. 742, Valid till 09/06/2027, License category- Composite Broker Visitors are hereby informed that their information submitted on the website may be shared with insurers. Product information is authentic and solely based on the information received from the insurers.
© Copyright 2008-2026 policybazaar.com. All Rights Reserved
˜ Policybazaar Promise reflects the guarantee offered by insurers. Price assurance is based on certifications shared by insurers with us.
HDFC Life Click 2 Protect Elite Pro is a pure term insurance
Read more
Kotak Protect Advantage is a Non-Participating, Non-Linked
Read more
Generali Central Saral Ashray Yojana is an individual pure risk
Read more
ICICI Pru iProtect Smart Her is a term insurance variant offered
Read more
Canara HSBC Life Insurance Promise2Secure is a non-linked
Read moreInsurance
Calculators
Payment Methods


Secured With

Follow us on


