• City & RTO
  • Registration Year
  • Car Brand
  • Car Model
  • Car Fuel Type
  • Car Variant
Get Car Insurance starting at only ₹2,094/year #
Lowest Price Guaranteed^ on Car Insurance
  • Renew policy in 2 minutes*

  • 21+ Insurers to choose

  • 1.2Cr+ Vehicles Insured

Processing
    Other models
    Other variants
    Secure
    We don’t spam
    View Prices
    Please wait..
    By clicking on “View Prices”, you agree to receive assistance and agree to our Privacy Policy & Terms of Use

    We have found best plans for you!! Our advisor will get in touch with you soon.

    Please wait ...
    Can You Switch from Third-Party to Comprehensive Car Insurance?

    Yes, you can switch from third-party to comprehensive car insurance either during your current policy period or at renewal, depending on the insurer's terms. Here's how the process works and important things to consider when upgrading your car insurance coverage.Read more

    Important Points to Remember Before Switching to Comprehensive Car Insurance

    Third-party car insurance covers your legal liability for injury, death or property damage caused to others, but it does not cover damage to your own car. If you want broader protection, you can switch to comprehensive coverage. However, when considering switching from a third-party cover to a comprehensive policy, keep these crucial factors in mind:

    • Premium Cost: Switching to a comprehensive policy provides enhanced coverage since it also financially protects you against damages to your own car. But it also increases your policy cost. The premium for a comprehensive policy depends on your car's make & model, age, vehicle registration location and any additional coverage options you choose.
    • Insured Declared Value (IDV): In car insurance, IDV is the maximum amount the insurer pays you in case your car gets stolen or is damaged beyond repair. When setting the IDV for your car, ensure that it is accurate and reflects the current market value.
    • No Claim Bonus (NCB): When you renew your comprehensive policy without raising a claim, you qualify for NCB in car insurance, which is a discount that applies to the own damage part of your policy. NCB can reach up to 50% after five consecutive years of no claims.

    Steps to Convert Third-Party to Comprehensive Car Insurance

    Here is the straightforward process to convert your third-party policy to comprehensive car insurance:

    1. Step 1: Check Your Existing Policy

      Verify the validity and expiry date of your current third-party insurance. This will help you decide whether to switch at renewal or purchase own-damage cover during the existing policy period.

    2. Step 2: Compare Plans Online

      Compare car insurance online and review coverage, premium prices, IDV, deductibles, exclusions, claim services and add-ons before choosing a policy.

    3. Step 3: Provide Your Car and Policy Details

      You may need to provide your car's registration number, make, model, variant and existing policy details.

    4. Step 4: Complete Vehicle Inspection

      The insurer may inspect your car before providing own-damage insurance cover. This is particularly necessary when you switch during your existing third-party policy term or when there is a break in insurance.

    5. Step 5: Choose Relevant Add-ons

      Depending on your vehicle requirements, select the relevant add-on covers to enhance the coverage of your standard comprehensive car insurance.

    6. Step 6: Pay the Premium

      Review the final premium and make the payment online via cards, net banking, or UPI.

    7. Step 7: Download & Review Your New Policy

      Once your comprehensive car insurance policy is issued, download and check the policy document to ensure the details and coverage are correct.

    Why You Should Upgrade to Comprehensive Car Insurance

    Upgrading to a comprehensive policy provides total peace of mind since it also covers your financial losses that may arise from:

    • Accidental Damage: The insurer pays for the expensive repair bills after an accident or collision causing damage to your car.
    • Theft: If your car is stolen and untraceable, you receive its IDV, which is the current market value.
    • Natural Disasters: Protection against unpredictable weather like floods, earthquakes, cyclones, and landslides.
    • Man-Made Calamities: Covers damages to your car from vandalism, riots, strikes, or fire.

    Essential Add-Ons to Consider with Comprehensive Coverage

    When you switch to a comprehensive policy, you can enhance your coverage further by opting for add-ons in car insurance for an additional premium amount. Some of the most valuable options are:

    • Zero Depreciation Cover: Standard comprehensive policies deduct money for a car's wear and tear during a claim. A zero-dep cover ensures that the insurer pays the complete cost of replaced parts in case of an accidental claim, subject to policy terms.
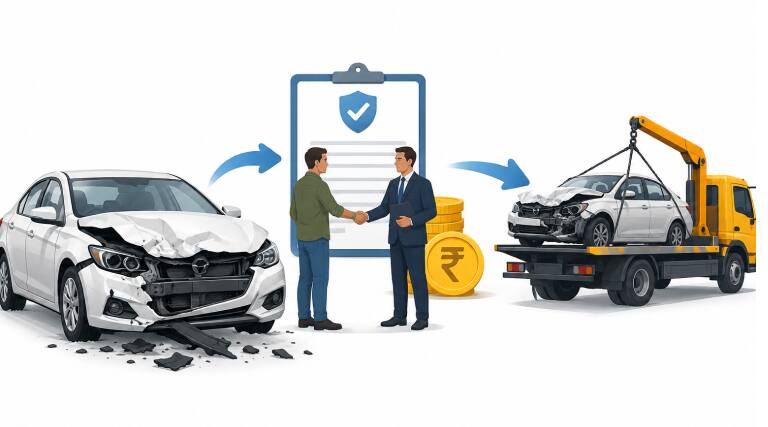
    • Return to Invoice (RTI): In case of a total loss of your car (when theft or damage beyond repair), the return to invoice cover makes sure you get back the original invoice amount of the car (including registration fees and road taxes), instead of just the depreciated IDV.
    • Engine Protection Cover: Standard comprehensive plans do not cover engine damage caused by waterlogging (hydrostatic lock). The engine protection add-on ensures your engine repairs are fully covered.
    • Roadside Assistance (RSA): The RSA in car insurance gives you 24x7 access to emergency towing services, flat-tire assistance, battery jumpstarts, and fuel delivery if your car breaks down and you are stranded on the road. Since availing these services does not count as a claim, it doesn't affect your NCB.

    Conclusion

    If your coverage needs have changed, switching from third-party insurance to comprehensive car insurance can give you broader financial protection for your vehicle. However, before making the switch, compare the premium, coverage and policy terms. It will make sure you have the right car insurance protection that suits your needs and budget.

    FAQs

    • Do I need to buy comprehensive insurance from the same insurer?

      No. You can choose a different insurer, subject to its underwriting and policy requirements.
    • Will my car be inspected when I switch to comprehensive insurance?

      The insurer may require a vehicle inspection before providing own-damage cover. This is particularly true when you add it during an existing policy term or after a break in insurance.
    • Should I cancel my existing third-party policy after buying comprehensive insurance?

      No, you should not cancel it without confirming how the new policy is structured. Your car must have continuous third-party liability coverage as mandated under Indian motor laws.
    • Can I get NCB when switching from third-party to comprehensive insurance?

      NCB applies to the own-damage portion of a motor policy. If you previously had only third-party insurance, you would not have accumulated NCB under that policy.
    • Is comprehensive car insurance mandatory in India?

      No, only third-party liability insurance is mandatory, while comprehensive insurance is optional.
    • Is comprehensive car insurance worth buying for an old car?

      It depends on the car's current value, premium and potential repair costs. Compare the cost of the own-damage cover with the protection it provides before deciding.
    Save upto 91% on Car Insurance
    Search
    Disclaimer: The list mentioned is according to the alphabetical order of the insurance companies. Policybazaar does not endorse, rate or recommend any particular insurer or insurance product offered by any insurer. This list of plans listed here comprise of insurance products offered by all the insurance partners of Policybazaar. For complete list of insurers in India refer to the Insurance Regulatory and Development Authority of India website www.irdai.gov.in
    Claim Assurance Program

    Car Insurance Articles

    • Recent Article
    • Popular Articles
    29 Sep 2026

    Imported Car Insurance

    Buying an imported car is a major milestone. Whether you bring in

    Read more
    25 Sep 2026

    Is Engine Protection Add-on Worth it for an Old...

    No, opting for the engine protection add-on with your car

    Read more
    21 Sep 2026

    Car Warranty vs Insurance: Key Differences

    A car's warranty and insurance can both help you pay for

    Read more
    15 Sep 2026

    Is Car Insurance Mandatory for a Parked Car in...

    Yes, car insurance is mandatory in India even for a parked car if

    Read more
    07 Sep 2026

    Salvage in Car Insurance: How it Affects Your...

    When it comes to car insurance, most people are familiar with

    Read more

    How to Get Your Duplicate Car Insurance Policy...

    In today's digital age, obtaining a duplicate car insurance policy online has never been easier. Whether you have

    Read more

    How to Transfer Car Insurance Policy?

    When you buy or sell the car, transferring the existing car insurance is an important step for both the buyer &

    Read more

    All About Car Fitness Certificate

    A car fitness certificate (FC) ensures that a motor vehicle is fit to be driven on roads. As per the Indian Motor

    Read more

    9 Secrets That Your Motor Insurance Provider...

    While motor insurance companies offer the necessary protection for your car, there are several hidden aspects they

    Read more

    Car Insurance Claim Process- A Step-By-Step Guide...

    Many vehicle owners often struggle with the car insurance claim process and sometimes even face claim rejections. To

    Read more

    #Rs 2094/- per annum is the price for third-party motor insurance for private cars (non-commercial) of not more than 1000cc

    *Savings are based on the comparison between the highest and the lowest premium for own damage cover (excluding add-on covers) provided by different insurance companies for the same vehicle with the same IDV and same NCB. Actual time for transaction may vary subject to additional data requirements and operational processes.

    +Savings are based on the maximum discount on own damage premium as offered by our insurer partners.

    ^Lowest Price Guaranteed is based on certifications shared by insurers with us. Policybazaar will facilitate price matching subject to the terms and conditions of select insurers.

    ##Claim Assurance Program: Pick-up and drop facility available in 1400+ select network garages. On-ground workshop team available in select workshops. Repair warranty on parts at the sole discretion of insurance companies. Dedicated Claims Manager. 24x7 Claim Assistance.

    Claude
    top
    View Plans
    Close
    Download the Policybazaar app
    to manage all your insurance needs.
    INSTALL