• City & RTO
  • Registration Year
  • Car Brand
  • Car Model
  • Car Fuel Type
  • Car Variant
Get Car Insurance starting at only ₹2,094/year #
Lowest Price Guaranteed^ on Car Insurance
  • Renew policy in 2 minutes*

  • 21+ Insurers to choose

  • 1.2Cr+ Vehicles Insured

Processing
    Other models
    Other variants
    Secure
    We don’t spam
    View Prices
    Please wait..
    By clicking on “View Prices”, you agree to receive assistance and agree to our Privacy Policy & Terms of Use

    We have found best plans for you!! Our advisor will get in touch with you soon.

    Please wait ...

    Constructive Total Loss (CTL) in Car Insurance

    If your car is severely damaged in an accident or a natural disaster, repairing it may cost much more than its value. This is known as a Constructive Total Loss (CTL) in car insurance. In these cases, the insurer may pay you the car's insured value rather than paying for repairs. Let's understand how CTL works and what it means for your claim settlement.Read more

    What is Constructive Total Loss (CTL) in Car Insurance?

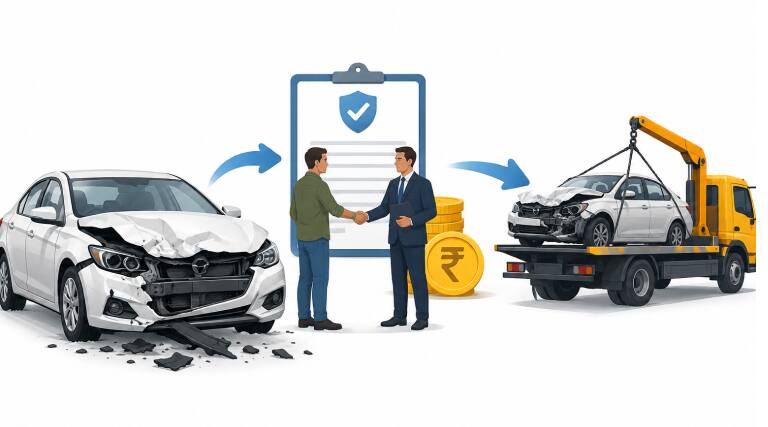
    In car insurance, a Constructive Total Loss (CTL) is a situation where a severely damaged car can technically be repaired, but the cost of parts repair and retrieval is higher than 75% of its Insured Declared Value (IDV). In such cases, car insurance companies declare the car a write-off and settle the claim as per policy terms. Here is an example:

    Particulars Amount
    Car's IDV Rs. 8 lakh
    Estimated Repair Cost Rs. 6.5 lakh
    Repair Cost as % of IDV 81.25%

    Common Reasons Why a Car May Be Declared a CTL

    A vehicle may be declared CTL in the following situations:

    • Major accidents or head-on collisions
    • Car overturning
    • Severe flood or fire-related damage
    • Extensive structural damage
    • Landslides or storms

    Total Loss vs Constructive Total Loss in Car Insurance Claim

    Many policyholders use these terms interchangeably, but they are different.

    Basis Constructive Total Loss (CTL) Total Loss
    Car Condition Repairable but repair cost is very high Damaged beyond repair or completely destroyed
    Repair Possibility Technically possible Not possible
    Cost of Repair Exceeds 75% of IDV Usually exceeds vehicle value or vehicle is irreparable
    Claim Settlement Based on IDV as per policy terms Based on IDV as per policy terms
    Car Usage After Incident Generally not economical to repair Cannot be restored for normal use

    In both cases, the insurer typically settles the claim based on the vehicle's IDV, subject to policy conditions and deductions.

    What is IDV and Why Does It Matter in CTL?

    Insured Declared Value (IDV) is the current market value of your car as determined at the time of policy issuance or renewal. It is important in a constructive total loss insurance claim because:

    • IDV acts as the maximum payable amount for CTL and total loss claims.
    • The insurer compares repair costs against the IDV to decide whether a car qualifies as CTL.
    • Settlement in CTL claims is generally based on the IDV mentioned in the policy.

    Here is a simple formula used by insurers:

    Vehicle Repair Cost ÷ IDV × 100

    If this result exceeds 75%, the insurer may declare the car as a Constructive Total Loss.

    You May Also Like - Total Loss in Car Insurance

    How Do Car Insurers Assess Constructive Total Loss Claims?

    Here is a structured process that most car insurance companies follow before declaring a car as a Constructive Total Loss.

    • Claim Intimation: The policyholder informs the insurer about the accident and registers a claim.
    • Vehicle Inspection: The insurer appoints a surveyor to inspect the damaged vehicle and assess the extent of loss.
    • Repair Estimate: An authorised garage prepares a detailed estimate of repair costs.
    • Comparison with IDV: The surveyor compares the repair estimate with the vehicle's IDV.
    • CTL Decision: If the repair and retrieval costs exceed 75% of the IDV, the insurer may classify the claim as CTL.
    • Claim Settlement: Once approved, the insurer settles the claim according to the policy terms and conditions.

    What Happens When a Car is Declared CTL?

    After a car is declared as a Constructive Total Loss:

    • The insurer calculates the claim amount based on the IDV.
    • Applicable deductibles are adjusted.
    • Ownership-related formalities may need to be completed.
    • The damaged vehicle (salvage) is usually transferred as per the insurer's settlement process.
    • The policyholder receives the approved claim amount.

    Documents Required for a CTL Claim

    The exact requirements for a CTL car insurance claim may vary from insurer to insurer, but here are the commonly required documents:

    • Your car insurance policy document
    • Claim form
    • Registration Certificate (RC)
    • Driving licence
    • PAN card or Aadhaar card
    • FIR (if applicable)
    • Repair estimate
    • Survey report
    • Bank account details

    Does CTL Affect Your No Claim Bonus (NCB)?

    Yes, when you file a CTL car insurance claim, you will lose any accumulated No Claim Bonus (NCB). However, if you have the NCB protection add-on cover in your policy, you might be able to retain your NCB benefits even after raising a CTL claim, subject to the insurer's terms and conditions.

    What Happens to the Vehicle Registration After CTL?

    In total loss and CTL cases, car owners may be required to complete registration-related formalities with their local Regional Transport Office (RTO). You may need to report your car that is destroyed or permanently incapable of use. Your insurance company will usually cancel the vehicle registration before settling the final claim amount.

    Essential Tips to Ensure a Smooth CTL Claim Settlement

    Follow these useful tips for a hassle-free settlement of your car's CTL insurance claim:

    • Inform your insurer immediately after the accident
    • Take photographs of the damage
    • Do not start repairs before your insurer approves it
    • Keep all repair estimates and bills safely
    • Cooperate with the surveyor during inspection
    • Check IDV and deductibles before filing a CTL claim
    • Submit all required documents on time

    FAQs

    • What is the meaning of CTL in car insurance?

      CTL stands for Constructive Total Loss. It is a situation where a car can be repaired, but the repair cost exceeds 75% of its Insured Declared Value (IDV), which makes repairs economically unviable.
    • At what percentage is a car considered a Constructive Total Loss?

      In car insurance, a vehicle is generally considered CTL when the aggregate repair and retrieval cost exceeds 75% of its IDV.
    • Is the constructive total loss the same as the total loss of a car?

      No. In a total loss, the car is destroyed or beyond repair. In CTL, the car can be repaired, but the repair cost is too high compared to its value.
    • How is the claim amount calculated in a CTL case?

      The settlement amount in CTL claims is generally the car's IDV mentioned in the policy, subject to insurer's terms and applicable deductibles.
    • Can a CTL claim be filed under comprehensive car insurance?

      Yes, you can file CTL claims under your comprehensive car insurance. The final decision is subject to policy terms and claim eligibility.
    • Does CTL apply in flood or fire damage cases?

      Yes. If events like floods, fire, accidents, or other covered incidents cause damage to a car and the repair costs exceed the CTL threshold, the insurer may declare the car a Constructive Total Loss.
    Save upto 91% on Car Insurance
    Search
    Disclaimer: The list mentioned is according to the alphabetical order of the insurance companies. Policybazaar does not endorse, rate or recommend any particular insurer or insurance product offered by any insurer. This list of plans listed here comprise of insurance products offered by all the insurance partners of Policybazaar. For complete list of insurers in India refer to the Insurance Regulatory and Development Authority of India website www.irdai.gov.in
    Claim Assurance Program

    Car Insurance Articles

    • Recent Article
    • Popular Articles
    29 Sep 2026

    Imported Car Insurance

    Buying an imported car is a major milestone. Whether you bring in

    Read more
    25 Sep 2026

    Is Engine Protection Add-on Worth it for an Old...

    No, opting for the engine protection add-on with your car

    Read more
    21 Sep 2026

    Car Warranty vs Insurance: Key Differences

    A car's warranty and insurance can both help you pay for

    Read more
    15 Sep 2026

    Is Car Insurance Mandatory for a Parked Car in...

    Yes, car insurance is mandatory in India even for a parked car if

    Read more
    07 Sep 2026

    Salvage in Car Insurance: How it Affects Your...

    When it comes to car insurance, most people are familiar with

    Read more

    How to Get Your Duplicate Car Insurance Policy...

    In today's digital age, obtaining a duplicate car insurance policy online has never been easier. Whether you have

    Read more

    How to Transfer Car Insurance Policy?

    When you buy or sell the car, transferring the existing car insurance is an important step for both the buyer &

    Read more

    All About Car Fitness Certificate

    A car fitness certificate (FC) ensures that a motor vehicle is fit to be driven on roads. As per the Indian Motor

    Read more

    9 Secrets That Your Motor Insurance Provider...

    While motor insurance companies offer the necessary protection for your car, there are several hidden aspects they

    Read more

    Car Insurance Claim Process- A Step-By-Step Guide...

    Many vehicle owners often struggle with the car insurance claim process and sometimes even face claim rejections. To

    Read more

    #Rs 2094/- per annum is the price for third-party motor insurance for private cars (non-commercial) of not more than 1000cc

    *Savings are based on the comparison between the highest and the lowest premium for own damage cover (excluding add-on covers) provided by different insurance companies for the same vehicle with the same IDV and same NCB. Actual time for transaction may vary subject to additional data requirements and operational processes.

    +Savings are based on the maximum discount on own damage premium as offered by our insurer partners.
    ^Lowest Price Guaranteed is based on certifications shared by insurers with us. Policybazaar will facilitate price matching subject to the terms and conditions of select insurers.

    ##Claim Assurance Program: Pick-up and drop facility available in 1400+ select network garages. On-ground workshop team available in select workshops. Repair warranty on parts at the sole discretion of insurance companies. Dedicated Claims Manager. 24x7 Claim Assistance.

    Claude
    top
    View Plans
    Close
    Download the Policybazaar app
    to manage all your insurance needs.
    INSTALL